Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Container Terminal Automation Market | Insight Market Data
Container Terminal Automation Market by Automation Level (Semi-Automated Terminals, Fully Automated Terminals), by Offering (Equipment(Automated Stacking Cranes, Automated Guided Vehicles, Remote Ship-to-Shore Cranes, Terminal Vehicles, Access Systems, Robotic Arms), Software & Integration Services, Services(Maintenance, Support, Consulting)), by Project Type (Brownfield Projects, Greenfield Projects), by Application (Container Yard Operations, Quay Transfer, Rail Exchange, Gate Control), by System Type (Software & Integration Services, Hardware & Equipment), by End-user (Port Authorities/Government Terminals, Private Terminal Operators, Shipping Line-Owned Terminals, Logistics Companies), by Sales Channel (Direct, Integrated, Retrofit, Aftermarket), by Asia Pacific (China, Japan, South Korea, Singapore, India, Vietnam), by Europe (Germany, Netherlands, Belgium, UK, Spain), by North America (United States, Canada, Mexico), by South America (Brazil, Chile, Peru), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Israel) Forecast 2026-2034
The film formers in cosmetics market is valued at USD 1.1 Billion in 2023, growing at 5.7% CAGR to reach USD 1.8 Billion by 2033. Read our full analysis.
Gardening container market valued at $21.0B in 2026, growing at 4.7% CAGR to reach $29.0B by 2033. Explore product, application and regional insights.
Nov 2026|205 pages
$2900.00
Global TPX release film for FPC board market to reach $2.25B by 2032 at 11.0% CAGR from $1.09B in 2025. Strategic analysis and forecasts.
Nov 2026|205 pages
$2900.00
China paper packaging market to grow from USD 96.13B in 2026 to USD 121.31B by 2031 at 4.76% CAGR. Driven by e-commerce & plastic-reduction mandates.
Nov 2026|222 pages
$2900.00
Reefer container shipping market at USD 10.48 billion in 2026, growing at 3.81% CAGR to USD 12.64 billion by 2031. Explore drivers, segments, and regions.
Executive Overview: The Container Terminal Automation Market
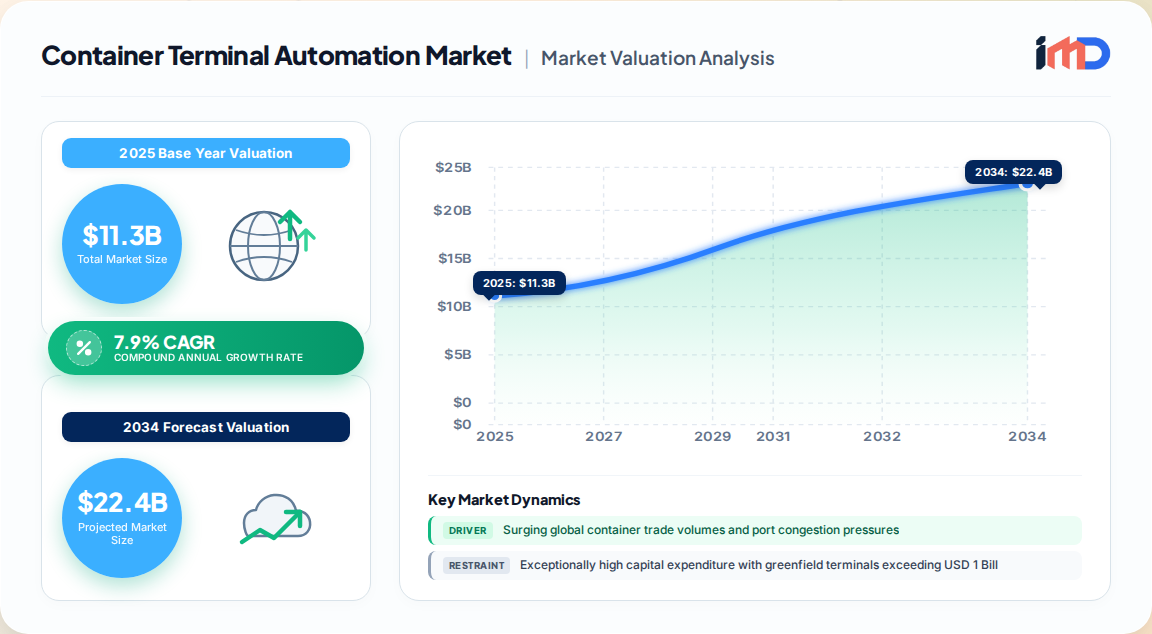
The global container terminal automation market was valued at USD 11.3 Billion in 2025 and is projected to reach USD 22.4 Billion by 2035, expanding at a CAGR of 7.9% across the forecast horizon. This trajectory reflects a structural shift in maritime logistics: manual terminal operations can no longer absorb the throughput demands of mega-vessels carrying beyond 24,000 TEUs per voyage, nor the labour-cost and safety burdens of developed-market port operations.
Container Terminal Automation Market Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
11.30 B
2025
12.19 B
2026
13.16 B
2027
14.20 B
2028
15.32 B
2029
16.53 B
2030
17.83 B
2031
Our proprietary primary research, triangulated across terminal operator interviews and equipment vendor briefings, indicates the market crossed USD 12.1 Billion in 2026 and is accelerating as brownfield retrofit pipelines mature in Europe and greenfield mega-hub programmes scale across Asia Pacific.
Asia Pacific commands the largest regional revenue share, projected at 49.5% by 2035, anchored by high-volume Chinese, Singaporean and South Korean hubs.
Europe is the fastest-growing region, driven by terminal modernisation, automated stacking crane investment and zero-emission port mandates.
Software and integration services are the fastest-compounding system type, forecast to capture 55.7% of segment value as operators layer intelligence atop installed hardware.
Key Market Drivers Reshaping Terminal Economics
Automation economics have crossed an inflection point. Labour accounts for 60–70% of total operating expenditure at conventional container terminals in developed markets, and automation deployments consistently deliver 15–25% improvements in berth utilisation versus manual operations. These are not marginal gains — they translate directly into lower demurrage costs, higher asset turns and measurable payback periods frequently under eight years for large-scale deployments.
Surging container trade volumes: Global containerised trade continues to expand even against softer overall maritime growth, requiring terminals to coordinate quay, yard and gate flows as a single system rather than isolated machine speed.
Escalating labour costs and safety mandates: Rising wages and stringent occupational health and safety benchmarks in the EU and Asia Pacific are compelling robotics-driven replacement of human-intensive yard operations.
Technological maturity: Integration of AI, IoT, 5G networks and digital twin platforms has moved from pilot to production, de-risking procurement decisions for first-time adopters.
Sustainability imperatives: Automated electric equipment configurations reduce emissions and align with green-port financing criteria increasingly demanded by multilateral lenders.
Restraints and Operational Challenges
Capital intensity remains the principal barrier. Greenfield fully automated terminals require investments exceeding USD 1 Billion depending on berth count and equipment specification — a threshold that excludes many port authorities in Latin America, sub-Saharan Africa and parts of South Asia whose balance sheets and concession tenors cannot support such commitments.
Integration complexity: Brownfield projects, which constitute the majority of active deployments, frequently face system interoperability delays of 12–24 months beyond initial estimates when retrofitting modern terminal operating systems onto legacy IT architectures.
Workforce transition friction: Labour union resistance in major European and North American ports requires negotiated retraining commitments that can dilute rollout scope.
Skills gap: Remote crane operation and fleet-management software demand new competencies that many terminal workforces lack.
Segmentation Analysis: Automation Level, Offering and Project Type
The market segments along three commercially decisive axes. Our research indicates that semi-automated terminals hold the dominant degree share at approximately 55% in 2026, reflecting operators' preference for hybrid models that balance capital efficiency with operational risk management. Fully automated terminals represent the fastest-growing degree segment, accelerating as technology costs decline and reference-site performance data builds investor confidence.
Segment Axis
Leading Category
Share (2026)
Fastest-Growing Category
Automation Level
Semi-Automated Terminals
~55%
Fully Automated Terminals
Offering
Equipment (ASCs, AGVs, cranes)
~49–62%
Software & Services
Project Type
Brownfield Projects
~68%
Greenfield Projects
Application
Container Yard Operations
~36%
Quay Transfer
Within equipment, automated stacking cranes lead with roughly 30% share, as dense storage blocks demand frequent, repeatable lift cycles during each vessel call. Software is gaining commercial importance as installed fleets require dispatching and coordination across mixed-vendor systems over decade-long operating lifetimes.
Regional Outlook and Investment Attractiveness
Asia Pacific's dominance is structural rather than cyclical — it hosts the world's highest concentration of mega-hub ports, state-directed smart-port investment programmes, and a competitive domestic automation manufacturing base centred on China and Japan that advantages regional procurement. Shanghai Port's Yangshan Phase IV terminal, a fully automated facility operating 24/7 with remote-controlled quay cranes and AGVs, handled its 50 millionth TEU in December 2024, setting a global throughput record.
Europe's growth is modernisation-led: automated stacking crane and AGV investment across Northern European gateways, combined with EU regulatory pressure on emissions and safety, creates a durable retrofit pipeline. North America presents a concentrated opportunity — the top 25 U.S. container ports handled 96% of all loaded TEUs in 2022, with 570 ship-to-shore gantry cranes deployed as of December 2024, of which 248 are super post-panamax units representing the most productive automation candidates.
Competitive Landscape and Strategic Developments
The vendor landscape splits into three competitive clusters: terminal equipment and fleet control (gantry crane engineering, AGV fleets), crane automation and remote operation specialists, and equipment-neutral software layers that coordinate mixed-vendor estates. Differentiation is shifting from machine performance toward commissioning risk minimisation, interface ownership clarity and sustained operating uptime.
August 2023: Evergreen Marine launched Taiwan's first fully automated container terminal, Terminal 7 at Kaohsiung Port, featuring 24 remote-controlled gantry cranes and smart gates, sized for four 24,000 TEU vessels simultaneously with expected annual throughput of 6.5 million TEU.
August 2024: Shanghai International Port Group launched Phase I of the Luojing terminal, adding design capacity of 2.6 million TEU annually.
2024: India's first semi-automated port at Vizhinjam, Kerala, moved toward operational status, signalling automation diffusion into emerging South Asian gateways.
March 2022: PSA Singapore partnered with A*STAR's Institute of High-Performance Computing to develop advanced AGV fleet management for Tuas Port, targeting roughly 50% carbon reduction.
Value Chain and Procurement Dynamics
The automation value chain runs from quay to gate: ship-to-shore crane automation, horizontal transport (AGVs and terminal vehicles), yard stacking crane systems, gate access control, and the terminal operating system layer that binds them. Procurement decisions increasingly test stacker crane systems against recovery procedures, interface ownership and live-commissioning throughput rather than peak trial performance. Buyers favour suppliers that establish clear accountability across integrated systems and maximise productive operating time during uninterrupted vessel handling.
Strategic White-Space Analysis
The most under-served opportunity lies in AI-powered optimisation and digital twin technology layered onto existing automation hardware. Operators that have already invested in basic automation now face a software upgrade path with materially lower capital intensity and faster payback than new equipment. Secondary white-space exists in emerging-market semi-automation packages paired with multilateral development bank financing instruments structured to match local concession tenors — a gap that currently slows adoption across Latin America, sub-Saharan Africa and South Asia.
Table 67: Saudi Arabia Container Terminal Automation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 68: South Africa Container Terminal Automation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 69: Israel Container Terminal Automation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How big is the container terminal automation market?
The global container terminal automation market was valued at USD 11.3 Billion in 2025 and is projected to reach USD 22.4 Billion by 2035, growing at a 7.9% CAGR. Asia Pacific accounts for the largest regional share, projected at 49.5% by 2035.
2Which region dominates container terminal automation adoption?
Asia Pacific leads with roughly 41% of global revenue in the base year, rising to an estimated 49.5% share by 2035. China, Singapore, South Korea and Japan anchor demand through mega-hub ports and state-directed smart-port investment programmes.
3What is driving investment in automated container terminals?
Labour accounts for 60–70% of operating expenditure at conventional terminals in developed markets, and automation delivers 15–25% improvements in berth utilisation. Rising container trade volumes, safety mandates and sustainability targets reinforce the case.
4Are semi-automated or fully automated terminals more common?
Semi-automated terminals hold the dominant share at roughly 55% in 2026, as operators favour hybrid models balancing capital efficiency with risk management. Fully automated terminals are the fastest-growing category as technology costs decline.
5What is the biggest barrier to container terminal automation?
Exceptionally high capital expenditure is the primary restraint, with greenfield fully automated terminals requiring investments exceeding USD 1 Billion. Brownfield integration complexity can also extend project timelines by 12–24 months.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research constitutes 70–80% of total study input, spanning structured interviews with terminal operators, port authorities, equipment OEMs and software integrators across 14 countries.
Interviewed company types include automated stacking crane and gantry crane OEMs, AGV and terminal vehicle manufacturers, terminal operating system software vendors, port authorities and private terminal operators, and systems integration and aftermarket service providers.
Stakeholder designations interviewed include Chief Operating Officer (Terminal Operations), Head of Automation & Technology, Procurement Director, and Port Infrastructure Planning Manager.
Engagements reference recognised technical and regulatory bodies including the International Association of Ports and Harbors (IAPH), Port Equipment Manufacturers Association (PEMA), the World Bank Container Port Performance Index, and UNCTAD maritime transport statistics.
Every report is refreshed to the date of purchase, incorporating the latest project commissioning milestones and vendor announcements.
Financial and corporate intelligence is validated via standard databases including Bloomberg, Factiva, Hoovers, and PitchBook, alongside recognised non-profit trade association publications.
Trade statistics, TEU throughput records and crane fleet inventories are cross-checked against official port authority disclosures and national maritime ministry filings.
All benchmark data is normalised to a common base year and USD denomination to ensure cross-regional comparability.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation across regional and segment cuts.
Bottom-up estimation is built from specific quantitative metrics: annual TEU throughput per terminal, automated crane and AGV unit installations and average selling prices, terminal operating system licence and integration spend, and retrofit project capex per berth.
Segment shares are modelled at the terminal level and aggregated upward, reconciling against regional throughput capacity constraints.
Forecasts incorporate known project pipelines, concession award timelines and equipment order books rather than pure extrapolation.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, with variance bands disclosed for emerging-market projections.
Findings undergo multi-level triangulation: primary interview consensus, official trade statistics and vendor order-book validation must converge before figures are published.
Outlier responses are re-verified through follow-up interviews and cross-checked against publicly disclosed project specifications.
Final datasets are peer-reviewed by senior analysts prior to release, with revision history maintained for full auditability.