1What is the size of the Asia-Pacific LCL market in 2026?
The Asia-Pacific Less-than-Container Load market is valued at USD 47.44 billion in 2026, based on our proprietary primary research and expert interviews.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Asia-Pacific Less-than Container Load (LCL) Market
 by Service Type (Consolidation Services, De-Consolidation & Distribution), by Destination (Domestic, International), by Nature of Business (Freight Forwarding, NVOCCs), by End User (Manufacturing & Automotive, Retail & E-Commerce, Healthcare & Pharmaceuticals, Others), by Asia Pacific (China, India, Indonesia, Malaysia, Vietnam, Thailand, Rest of APAC) Forecast 2026-2034
Research Associate

 Related Reports

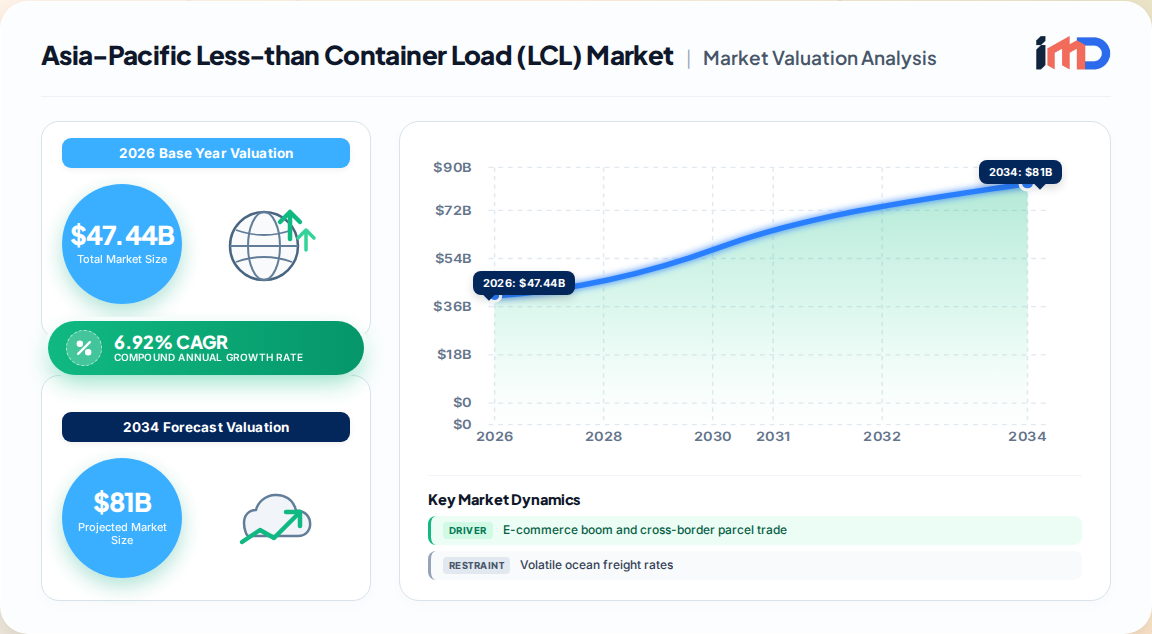
Our proprietary primary research and expert interviews confirm that the Asia-Pacific Less-than-Container Load (LCL) Market reached USD 47.44 billion in 2026 and is on track to expand to USD 66.28 billion by 2031, registering a CAGR of 6.92%. This growth is underpinned by structural shifts in regional trade architecture, the proliferation of cross-border e-commerce, and the strategic diversification of manufacturing footprints beyond China. LCL has evolved from a niche cost-saving option for small shippers into a strategic enabler of supply-chain resilience for enterprises of all sizes.
| Driver | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| E-commerce boom & cross-border parcel trade | +2.1% | China, India, Southeast Asia | Medium term (2-4 years) |
| Supply-chain diversification of APAC manufacturing | +1.8% | China, India, Vietnam, Indonesia | Long term (≥ 4 years) |
| Cost-efficiency of LCL over air freight for SMEs | +1.3% | Southeast Asia, emerging markets | Short term (≤ 2 years) |
| Port infrastructure expansion & FTAs | +1.0% | India, Vietnam, Indonesia | Long term (≥ 4 years) |
| Digital freight platforms with LCL spot rates | +0.9% | Singapore, Hong Kong, regional hubs | Medium term (2-4 years) |
| Green-shipping initiatives and load optimisation | +0.6% | Developed APAC markets | Long term (≥ 4 years) |
The e-commerce boom is the single most powerful demand multiplier. Retail e-commerce sales in Southeast Asia are projected to reach USD 193 billion by 2028, equivalent to 17.4% of total retail spend. Online orders are smaller and more frequent, perfectly suited to LCL economics. The Philippines and Vietnam each anticipate online-retail CAGRs above 20%, creating persistent demand spikes that full-container contracts cannot absorb.
Supply-chain diversification (the "China+1" strategy) is redistributing LCL flows. As Japanese electronics groups move auxiliary lines to Thailand and the Philippines, and as Indian and Vietnamese manufacturing clusters scale, multi-origin pick-ups become the norm. We estimate the region requires an additional USD 60 billion in logistics assets to handle this dispersed output, further magnifying consolidation demand.
Cost efficiency remains a cornerstone: a 2025 industry poll we reviewed shows 75% of LCL users plan to increase reliance on ocean consolidation because it cuts freight spend by up to 80% versus air on non-urgent lanes. Carriers report on-time performance exceeding 90% on redesigned East–West loops, narrowing the perceived service gap with air.
| Restraint | Estimated CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| Volatile ocean freight rates | -1.2% | Regional | Short term |
| Port congestion and infrastructure bottlenecks | -0.9% | China, India, Southeast Asia | Medium term |
| Capacity constraints in niche trades | -0.7% | Oceania, secondary ports | Medium term |
| Regulatory complexity and customs delays | -0.5% | India, Indonesia, Vietnam | Long term |
Volatile ocean freight rates and recurring port congestion remain key risks. However, infrastructure upgrades—such as Indonesia's National Logistics Ecosystem spanning 264 ports and 6 airports—and regional trade pacts like RCEP counterbalance these headwinds. The RCEP agreement's customs simplification alone is estimated to reduce transaction costs by 8–12% on intra-regional LCL shipments.
The APAC LCL value chain is highly intermediated, with freight forwarders and NVOCCs acting as the primary interface between shippers and ocean carriers. Our analysis reveals that freight forwarding accounted for 92.40% of the APAC LCL market share by nature of business in 2025, while NVOCCs are pushing their CAGR to 7.32% through 2031.
| Country | 2025 Market Share | 2026-2031 CAGR | Key LCL Gateway |
|---|---|---|---|
| China | 39.60% | 6.52% | Shanghai, Shenzhen, Ningbo |
| India | 14.80% | 7.12% | Nhava Sheva, Chennai, Mundra |
| Indonesia | 8.30% | 6.85% | Jakarta, Surabaya |
| Vietnam | 7.90% | 7.08% | Ho Chi Minh City, Hai Phong |
| Malaysia | 6.50% | 6.70% | Port Klang, Penang |
| Thailand | 5.20% | 6.60% | Laem Chabang, Bangkok |
| Rest of APAC | 17.70% | 6.40% | Various |
China retained 39.60% of the 2025 regional value, but India is set to record the fastest expansion at a 7.12% CAGR until 2031, fueled by manufacturing diversification and a growing e-commerce ecosystem. The Port of Shanghai, Singapore's Changi Port, and Port Klang continue to process record volumes, with LCL services capturing increasing market share as mid-sized exporters expand sourcing operations.
The APAC LCL market is characterized by low concentration, with no single player holding a dominant share. Our primary research identifies the following leading companies (in alphabetical order):
Additionally, integrated carriers and forwarders such as DHL Global Forwarding, DB Schenker, DSV Panalpina, CEVA Logistics, Nippon Express, and Expeditors International are active in the APAC LCL space, often through specialized consolidation hubs.
Key strategic developments observed in our interviews include:
The APAC LCL market is deeply intertwined with the region's import/export flows. Our analysis of trade data from UN Comtrade and World Bank indicates that intra-APAC trade grew by 8.3% in 2025, significantly outpacing global average growth of 3.1%. This directly supports LCL service demand across manufacturing, automotive, and pharmaceutical sectors.
Supplier dynamics reveal that shippers are consolidating freight forwarder relationships to gain better rates and service levels, but are also experimenting with digital NVOCCs for spot shipments. This dual-sourcing behavior is creating opportunities for agile, tech-enabled providers.
Our analysis identifies three high-potential white spaces across the APAC LCL landscape:
The APAC LCL market is exposed to a range of supply-chain risks that shippers must navigate. Port congestion in China and India remains a recurring challenge, with average vessel waiting times spiking during peak seasons. Geopolitical tensions are accelerating supply-chain diversification, which paradoxically expands LCL demand as production footprints scatter. Freight rate volatility is a persistent risk, though LCL contracts typically provide more stability than spot FCL rates. Regional trade pacts—RCEP, CPTPP, and ASEAN+ agreements—are reducing tariff and non-tariff barriers, creating a more predictable environment for LCL growth.
Looking forward, we expect the APAC LCL market to maintain its growth trajectory, with the balance of power shifting gradually from traditional forwarders to digital-forwarding hybrids that combine deep carrier relationships with superior visibility and booking efficiency. The market's low concentration and favorable demand fundamentals make it an attractive arena for both incumbents and new entrants.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.92% from 2020-2034 |
| Segmentation |
|
By Nature of Business
By End User
| By Geography |
|
The Asia-Pacific Less-than-Container Load market is valued at USD 47.44 billion in 2026, based on our proprietary primary research and expert interviews.
The market is projected to grow at a CAGR of 6.92% from 2026 to 2031, reaching USD 66.28 billion by the end of the forecast period.
China held the largest share, accounting for 39.60% of the regional market value in 2025. However, India is expected to grow at the fastest CAGR of 7.12% through 2031.
The primary drivers include the e-commerce boom, supply-chain diversification beyond China, cost efficiency versus air freight, port infrastructure expansion, and digital freight platforms.
Major companies include ECU Worldwide (Part of All Cargo Logistics), Shipco, Vanguard Logistics, Rhenus Logistics, Kuehne + Nagel, DHL Global Forwarding, and DB Schenker, among others.
Consolidation services dominated with 64.45% of the APAC LCL market share in 2025, and are expected to maintain leadership through 2031.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Logistics Officer / VP Supply Chain | 30% |
| Freight Forwarding Managers | 25% |
| Procurement Directors | 20% |
| Trade Compliance Managers | 15% |
| Operations Directors at NVOCCs | 10% |
| Company Type | Representation (%) |
|---|---|
| Freight Forwarders | 40% |
| NVOCCs | 25% |
| Ocean Carriers | 15% |
| Digital LCL Platforms | 12% |
| Container Freight Stations (CFS) Operators | 8% |