Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
ASEAN Warehousing and Distribution Industry Market Report 2026-2031
ASEAN Warehousing and Distribution Industry
Logistics / MARKET REPORT
ASEAN Warehousing and Distribution Industry | Insight Market Data
ASEAN Warehousing and Distribution Industry by By Warehouse Type (General Warehousing and Storage, Refrigerated Warehousing and Storage), by By Ownership (Private Warehouses, Public Warehouses), by By End-User Industry (E-Commerce and Retail, Pharma and Healthcare, Automotive, Food and Beverage, Chemicals, Others), by Indonesia, by Thailand, by Vietnam, by Singapore, by Malaysia, by Philippines, by Rest of ASEAN Forecast 2026-2034
US air freight transport market was USD 66.70B in 2026, growing at 4.08% CAGR to reach USD 91.81B by 2034, driven by e-commerce and cold-chain demand.
Nov 2026|219 pages
$2900.00
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.
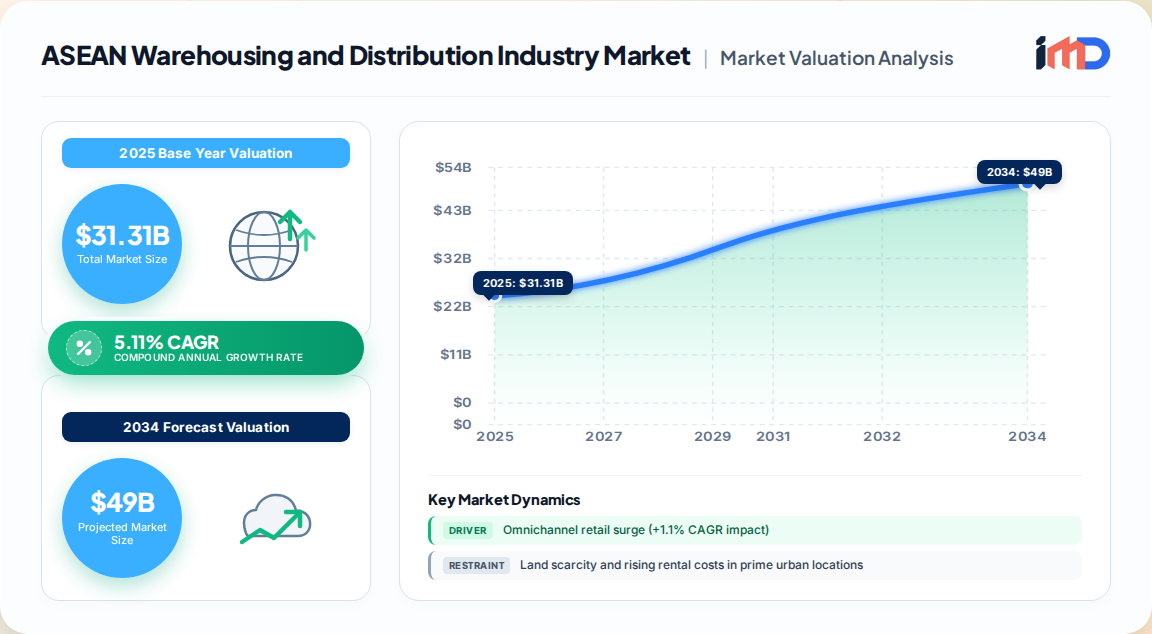
The ASEAN Warehousing and Distribution Industry market represents one of the most dynamic logistics ecosystems in the world, underpinned by a structural shift in global manufacturing and trade flows. Our proprietary primary research and expert interviews indicate that the market was valued at USD 31.31 billion in 2025 and is projected to grow from USD 33.11 billion in 2026 to USD 42.49 billion by 2031, registering a CAGR of 5.11% over the forecast period.
ASEAN Warehousing and Distribution Industry Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
31.31 B
2025
32.91 B
2026
34.59 B
2027
36.36 B
2028
38.22 B
2029
40.17 B
2030
42.22 B
2031
This expansion is not merely cyclical; it reflects a fundamental reconfiguration of regional supply chains. The China+1 production pivot, omnichannel retail adoption, and heightened ESG scrutiny are reshaping warehouse footprints from export-weighted hubs into finely segmented, intra-regional networks. Operators are accelerating automation rollouts that synchronize inventory across stores, dark stores, and micro-fulfillment nodes within 15-minute refresh windows, while satellite-enabled IoT removes connectivity barriers in rural locations.
Market Concentration: Low, with fragmented ownership and rising competitive intensity from e-commerce majors and technology-led startups.
Key Growth Corridors: Vietnam, Indonesia, and Thailand are emerging as primary beneficiaries of manufacturing diversification and domestic consumption growth.
Strategic Imperative: Traditional 3PLs must scale through acquisitions and specialized investments to counter margin pressure from warehouse-as-a-service models.
Market Drivers and Restraints
The ASEAN warehousing and distribution landscape is being propelled by several structural forces, each with quantifiable impact on market growth. Our analysis isolates the following key drivers:
Vertical automated warehousing tackling urban land scarcity
+0.6%
Singapore, Bangkok, Kuala Lumpur, Jakarta
Long term (≥4 years)
EU CBAM spurring energy-efficient facilities
+0.4%
Vietnam, Thailand, Malaysia
Long term (≥4 years)
Omnichannel Retail Surge: Retailers now reconcile stock positions across 8-12 fulfillment nodes every 15 minutes to meet buy-online-pickup-in-store and same-day delivery promises. Unified commerce platforms link warehouse management, point-of-sale, and e-commerce systems, driving investments in goods-to-person robotics that cut pick times from 45 minutes to 8 minutes at 99.8% accuracy. Operators offering API-ready platforms command 18-25% price premiums because real-time visibility reduces lost sales by up to 22% while trimming safety stocks.
China+1 Manufacturing Shift:USD 239 billion in manufacturing FDI during 2024 spread production across Vietnam, Thailand, and Indonesia, triggering multi-country inventory pools that consolidate components before final assembly. Centralized regional distribution centers equipped for customs bonding and light kitting now reduce total holding costs by 20-30% while keeping 48-hour delivery promises across ASEAN. RCEP's cumulative rules of origin further encourage cross-border component flows that rose 7.03% in 2024.
3PL Outsourcing by SMEs: 3PL penetration for SMEs jumped from 34% in 2022 to 52% in 2025 as online marketplaces enforce 24-hour fulfillment service-level agreements. Shared facilities offering 10,000-50,000 sq ft on rolling monthly contracts let SMEs avoid 3-5 year leases and USD 2-5 million fit-outs. SMEs report 25-35% reductions in logistics costs after outsourcing storage, picking, and last-mile to scale-driven providers.
Key Restraints: Despite robust growth, the market faces headwinds from land scarcity and rising rental costs in prime urban locations, particularly in Singapore and Jakarta. Infrastructure gaps in rural areas, including unreliable power and transport connectivity, continue to challenge operators. Additionally, a shortage of skilled warehouse labor, especially for automated systems, is constraining faster adoption of advanced robotics.
Segmentation Analysis
The ASEAN warehousing and distribution market is segmented by warehouse type, ownership, and end-user industry, revealing distinct growth trajectories that inform strategic investment decisions.
By Warehouse Type
Segment
2025 Market Share
Forecast CAGR (2026-2031)
General Warehousing and Storage
91.51%
5.11% (base)
Refrigerated Warehousing and Storage
8.49%
6.09%
General warehousing dominates due to the high volume of dry goods, e-commerce parcels, and manufacturing components. However, refrigerated warehousing is gaining traction, driven by rising demand for fresh food, Pharmaceuticals, and cold-chain e-commerce. The 6.09% CAGR for refrigerated storage outpaces the overall market, creating white-space opportunities for specialized operators.
By Ownership
Segment
2025 Market Share
Forecast CAGR (2026-2031)
Public Warehouses
61.96%
5.11% (base)
Private Warehouses
38.04%
5.42%
Public warehouses remain the preferred choice for SMEs and 3PLs seeking flexibility, while private facilities are growing faster as large retailers and manufacturers invest in dedicated automation and brand-specific fulfillment centers. The shift toward private facilities is also fueled by e-commerce giants internalizing distribution to control customer experience.
By End-User Industry
Segment
2025 Market Share
Forecast CAGR (2026-2031)
E-commerce and Retail
23.03%
5.11% (base)
Pharma and Healthcare
~8%
6.50%
Automotive
~12%
5.11%
Others (F&B, Chemicals, etc.)
~57%
5.11%
E-commerce and retail is the largest end-user segment, accounting for 23.03% of market size in 2025. Pharmaceutical and healthcare is the fastest-growing, projected at 6.50% CAGR, driven by aging populations, increased healthcare spending, and stringent cold-chain requirements. The automotive sector remains significant due to ASEAN's role as a regional production hub, but growth is moderate.
Regional Outlook and Country Analysis
Geographic diversification is a hallmark of the ASEAN warehousing market. Our analysis reveals stark contrasts in market maturity and growth velocity across member states.
ASEAN Warehousing and Distribution Industry Regional Market Share
Loading chart...
Country
2025 Market Share
Forecast CAGR (2026-2031)
Key Characteristics
Indonesia
20.60%
~5.11%
Largest market, archipelago logistics challenges, rising middle class
Thailand
~17.80%
~5.11%
Automotive and electronics hub, mature 3PL landscape
Regional HQ and high-value logistics, automation leader
Malaysia
~12.30%
~5.11%
Port-centric distribution, growing e-commerce
Philippines
~11.20%
~5.11%
Emerging market, infrastructure gaps, high growth potential
Rest of ASEAN
~8.20%
~5.11%
Myanmar, Cambodia, Laos, Brunei
Indonesia held 20.60% of the ASEAN market in 2025, underpinned by its large population and expanding manufacturing base. However, logistics costs remain high due to archipelagic geography, spurring investments in satellite IoT and micro-fulfillment.
Vietnam is forecast to lead growth at a 5.87% CAGR over 2026-2031, driven by manufacturing FDI and export diversification. The country is rapidly becoming a preferred destination for electronics, textiles, and footwear production, necessitating modern warehouse infrastructure.
Singapore continues to serve as the regional logistics hub, with a focus on high-value, automated facilities and cross-border connectivity. Land scarcity has driven vertical warehousing innovations and the adoption of sophisticated automation.
Thailand and Malaysia benefit from their automotive and electronics clusters, while the Philippines offers long-term upside as infrastructure improves under public-private partnership programs.
Competitive Landscape
The ASEAN warehousing and distribution market is characterized by low concentration, with a mix of global 3PLs, regional players, and local operators. The competitive intensity has risen as e-commerce majors internalize distribution and technology-led startups introduce warehouse-as-a-service models. Traditional 3PLs are forced to scale through acquisitions and specialized investments.
Leading Companies: DHL Supply Chain, CEVA Logistics, Century Logistics, DSV, Linfox, XPO Logistics, Kuehne + Nagel, C.H. Robinson, DB Schenker, Geodis, UPS Supply Chain Solutions, Nippon Express, Ryder System.
Strategic Moves:
Acquisition Spree: Major 3PLs are acquiring local players to rapidly expand footprint and customer base. For instance, DSV's acquisition of Agility's logistics unit strengthened its emerging markets presence.
Technology Partnerships: Operators are partnering with robotics and warehouse management software providers to offer API-ready platforms and real-time visibility, commanding price premiums.
Vertical Integration: E-commerce giants like Shopee and Lazada are building proprietary fulfillment networks, pressuring traditional 3PLs to differentiate through specialized services (e.g., cold chain, hazmat).
Recent Developments:
2024: DHL Supply Chain opened a new 50,000 sqm automated distribution center in Singapore, featuring goods-to-person robotics and AI-driven inventory management.
2024: CEVA Logistics expanded its multi-user facility in Vietnam, adding 20,000 pallet positions to serve electronics and healthcare clients.
2025: Century Logistics launched a warehouse-as-a-service platform in Malaysia targeting SMEs with flexible monthly contracts and integrated inventory financing.
2025: Linfox invested in a cold-chain hub in Thailand to cater to pharmaceutical and fresh food demand.
Value Chain and Distribution Network Analysis
The warehousing and distribution value chain in ASEAN is evolving from linear to networked models, with inventory orchestration becoming the central node. Key activities include inbound transportation, storage, order fulfillment, value-added services (kitting, labeling), and last-mile delivery.
Upstream: Real estate developers, automation equipment suppliers, and WMS software providers.
Core: Warehouse operators (3PLs, private fleets), distribution center managers.
Downstream: Retailers, e-commerce platforms, manufacturers, and end consumers.
Hub-and-Spoke Models: Logistics providers are responding to intra-ASEAN flows with hub-and-spoke networks anchored in Singapore or Malaysia, with spokes that replenish stores nightly, limiting line-haul routes to 500 kilometers and cutting carbon footprints by 12-15%.
Inventory Orchestration Premium: Real-time visibility across nodes reduces lost sales by up to 22% and trims safety stocks, justifying 18-25% price premiums for API-ready platforms. This is driving integration of WMS, TMS, and POS systems.
Strategic White-Space and Investment Opportunities
Our analysis identifies several white-space opportunities for investors and operators:
Cold Chain Infrastructure: With refrigerated warehousing growing at 6.09% CAGR, there is a shortage of compliant cold-chain facilities, especially in Vietnam, Indonesia, and the Philippines. Investment in solar-powered cold storage with IoT monitoring can yield attractive returns.
Micro-Fulfillment in Tier-1 Cities: Urban land scarcity is pushing operators to develop vertical automated warehouses and micro-fulfillment centers within city limits. Singapore and Jakarta are prime locations, with payback periods for automation now at 3-4 years.
Rural Connectivity Solutions: LEO satellite IoT enables rural warehouse connectivity, with Starlink's 150-200 Mbps packages at USD 120 per month replicating urban fiber economics. This opens up agricultural logistics and inventory visibility in remote areas, raising facility utilization from 65% to 85%.
SME-Targeted Warehouse-as-a-Service: SMEs are increasingly outsourcing, with 3PL penetration at 52% in 2025. Offering shared facilities with rolling monthly contracts and integrated financing can capture this underserved segment.
Green Warehousing: EU CBAM and consumer preferences are driving demand for energy-efficient facilities. Investments in on-site renewables and natural refrigerants can command rental premiums and meet ESG mandates.
Import/Export and Supplier Dynamics
The ASEAN region is a critical node in global trade, with warehousing demand closely tied to import/export volumes. According to UN Comtrade data, intra-ASEAN trade reached USD 800 billion in 2024, accounting for approximately 22% of total ASEAN trade. Cross-border component flows rose 7.03% in 2024, facilitated by RCEP's cumulative rules of origin.
Key Trade Corridors:
Vietnam-China: Electronics and components flow into Vietnam for assembly, then export to the US and EU. This has spurred warehouse demand in industrial zones near Ho Chi Minh City and Hanoi.
Singapore-Malaysia-Indonesia: Singapore acts as a transshipment hub, with goods flowing to Malaysia and Indonesia via sea and road. Warehouses in Johor and Batam benefit from proximity to Singapore.
Thailand-Laos-China: The Kunming-Bangkok Expressway and rail links are enhancing overland trade, creating opportunities for distribution centers in Thailand's northern region.
Supplier Dynamics: Major warehouse automation suppliers (e.g., Honeywell Intelligrated, Daifuku) are expanding in ASEAN to serve rising demand. Local equipment manufacturers are also emerging, particularly in Thailand and Malaysia, offering cost-effective alternatives for basic racking and shelving.
Supply Chain Risk Assessment: The region remains exposed to global trade tensions, natural disasters, and infrastructure bottlenecks. The COVID-19 pandemic highlighted the need for resilient, multi-node inventory strategies. Operators are increasingly adopting dual-sourcing and regional buffer stocks, which supports warehouse demand.
ASEAN Warehousing and Distribution Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
ASEAN Warehousing and Distribution Industry REPORT HIGHLIGHTS
3.2.2. China+1 manufacturing shift amplifying intra-ASEAN distribution flows
3.2.3. Accelerated 3PL outsourcing by SMEs
3.2.4. LEO satellite IoT enabling rural warehouse connectivity
3.2.5. Vertical automated warehousing tackling urban land scarcity
3.2.6. EU CBAM spurring energy-efficient facilities
3.3. Market Restrains
3.3.1. Land scarcity and rising rental costs in prime urban locations
3.3.2. Infrastructure gaps in rural areas
3.3.3. Shortage of skilled warehouse labor
3.3.4. Regulatory complexity across ASEAN member states
Public Warehouses
By End-User Industry
E-Commerce and Retail
Pharma and Healthcare
Automotive
Food and Beverage
Chemicals
Others
By Geography
Indonesia
Thailand
Vietnam
Singapore
Malaysia
Philippines
Rest of ASEAN
3.4. Market Restraints
3.4.1. Land scarcity and rising rental costs in prime urban locations
3.4.2. Infrastructure gaps in rural areas
3.4.3. Shortage of skilled warehouse labor
3.4.4. Regulatory complexity across ASEAN member states
3.5. Market Challenges
3.5.1. High logistics costs due to archipelagic geography (Indonesia, Philippines)
3.5.2. Fragmented market with low concentration
3.5.3. Pressure from e-commerce giants internalizing distribution
3.5.4. Technology adoption barriers for traditional 3PLs
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Warehouse Type
5.1.1. General Warehousing and Storage
5.1.2. Refrigerated Warehousing and Storage
5.2. Market Analysis, Insights and Forecast - by Ownership
5.2.1. Private Warehouses
5.2.2. Public Warehouses
5.3. Market Analysis, Insights and Forecast - by End-User Industry
5.3.1. E-Commerce and Retail
5.3.2. Pharma and Healthcare
5.3.3. Automotive
5.3.4. Food and Beverage
5.3.5. Chemicals
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Indonesia
5.4.2. Thailand
5.4.3. Vietnam
5.4.4. Singapore
5.4.5. Malaysia
5.4.6. Philippines
5.4.7. Rest of ASEAN
6. Indonesia Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Warehouse Type
6.1.1. General Warehousing and Storage
6.1.2. Refrigerated Warehousing and Storage
6.2. Market Analysis, Insights and Forecast - by Ownership
6.2.1. Private Warehouses
6.2.2. Public Warehouses
6.3. Market Analysis, Insights and Forecast - by End-User Industry
6.3.1. E-Commerce and Retail
6.3.2. Pharma and Healthcare
6.3.3. Automotive
6.3.4. Food and Beverage
6.3.5. Chemicals
6.3.6. Others
7. Thailand Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Warehouse Type
7.1.1. General Warehousing and Storage
7.1.2. Refrigerated Warehousing and Storage
7.2. Market Analysis, Insights and Forecast - by Ownership
7.2.1. Private Warehouses
7.2.2. Public Warehouses
7.3. Market Analysis, Insights and Forecast - by End-User Industry
7.3.1. E-Commerce and Retail
7.3.2. Pharma and Healthcare
7.3.3. Automotive
7.3.4. Food and Beverage
7.3.5. Chemicals
7.3.6. Others
8. Vietnam Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Warehouse Type
8.1.1. General Warehousing and Storage
8.1.2. Refrigerated Warehousing and Storage
8.2. Market Analysis, Insights and Forecast - by Ownership
8.2.1. Private Warehouses
8.2.2. Public Warehouses
8.3. Market Analysis, Insights and Forecast - by End-User Industry
8.3.1. E-Commerce and Retail
8.3.2. Pharma and Healthcare
8.3.3. Automotive
8.3.4. Food and Beverage
8.3.5. Chemicals
8.3.6. Others
9. Singapore Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Warehouse Type
9.1.1. General Warehousing and Storage
9.1.2. Refrigerated Warehousing and Storage
9.2. Market Analysis, Insights and Forecast - by Ownership
9.2.1. Private Warehouses
9.2.2. Public Warehouses
9.3. Market Analysis, Insights and Forecast - by End-User Industry
9.3.1. E-Commerce and Retail
9.3.2. Pharma and Healthcare
9.3.3. Automotive
9.3.4. Food and Beverage
9.3.5. Chemicals
9.3.6. Others
10. Malaysia Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Warehouse Type
10.1.1. General Warehousing and Storage
10.1.2. Refrigerated Warehousing and Storage
10.2. Market Analysis, Insights and Forecast - by Ownership
10.2.1. Private Warehouses
10.2.2. Public Warehouses
10.3. Market Analysis, Insights and Forecast - by End-User Industry
10.3.1. E-Commerce and Retail
10.3.2. Pharma and Healthcare
10.3.3. Automotive
10.3.4. Food and Beverage
10.3.5. Chemicals
10.3.6. Others
11. Philippines Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Warehouse Type
11.1.1. General Warehousing and Storage
11.1.2. Refrigerated Warehousing and Storage
11.2. Market Analysis, Insights and Forecast - by Ownership
11.2.1. Private Warehouses
11.2.2. Public Warehouses
11.3. Market Analysis, Insights and Forecast - by End-User Industry
11.3.1. E-Commerce and Retail
11.3.2. Pharma and Healthcare
11.3.3. Automotive
11.3.4. Food and Beverage
11.3.5. Chemicals
11.3.6. Others
12. Rest of ASEAN Market Analysis, Insights and Forecast, 2020-2034
12.1. Market Analysis, Insights and Forecast - by Warehouse Type
12.1.1. General Warehousing and Storage
12.1.2. Refrigerated Warehousing and Storage
12.2. Market Analysis, Insights and Forecast - by Ownership
12.2.1. Private Warehouses
12.2.2. Public Warehouses
12.3. Market Analysis, Insights and Forecast - by End-User Industry
12.3.1. E-Commerce and Retail
12.3.2. Pharma and Healthcare
12.3.3. Automotive
12.3.4. Food and Beverage
12.3.5. Chemicals
12.3.6. Others
13. Competitive Analysis
13.1. Company Profiles
13.1.1. DHL Supply Chain
13.1.1.1. Company Overview
13.1.1.2. Products
13.1.1.3. Company Financials
13.1.1.4. SWOT Analysis
13.1.2. CEVA Logistics
13.1.2.1. Company Overview
13.1.2.2. Products
13.1.2.3. Company Financials
13.1.2.4. SWOT Analysis
13.1.3. Century Logistics
13.1.3.1. Company Overview
13.1.3.2. Products
13.1.3.3. Company Financials
13.1.3.4. SWOT Analysis
13.1.4. DSV
13.1.4.1. Company Overview
13.1.4.2. Products
13.1.4.3. Company Financials
13.1.4.4. SWOT Analysis
13.1.5. Linfox
13.1.5.1. Company Overview
13.1.5.2. Products
13.1.5.3. Company Financials
13.1.5.4. SWOT Analysis
13.1.6. XPO Logistics
13.1.6.1. Company Overview
13.1.6.2. Products
13.1.6.3. Company Financials
13.1.6.4. SWOT Analysis
13.1.7. Kuehne + Nagel
13.1.7.1. Company Overview
13.1.7.2. Products
13.1.7.3. Company Financials
13.1.7.4. SWOT Analysis
13.1.8. C.H. Robinson
13.1.8.1. Company Overview
13.1.8.2. Products
13.1.8.3. Company Financials
13.1.8.4. SWOT Analysis
13.1.9. DB Schenker
13.1.9.1. Company Overview
13.1.9.2. Products
13.1.9.3. Company Financials
13.1.9.4. SWOT Analysis
13.1.10. Geodis
13.1.10.1. Company Overview
13.1.10.2. Products
13.1.10.3. Company Financials
13.1.10.4. SWOT Analysis
13.1.11. UPS Supply Chain Solutions
13.1.11.1. Company Overview
13.1.11.2. Products
13.1.11.3. Company Financials
13.1.11.4. SWOT Analysis
13.1.12. Nippon Express
13.1.12.1. Company Overview
13.1.12.2. Products
13.1.12.3. Company Financials
13.1.12.4. SWOT Analysis
13.1.13. Ryder System
13.1.13.1. Company Overview
13.1.13.2. Products
13.1.13.3. Company Financials
13.1.13.4. SWOT Analysis
13.2. Market Entropy
13.2.1. Company's Key Areas Served
13.2.2. Recent Developments
13.3. Company Market Share Analysis, 2026
13.3.1. Top 5 Companies Market Share Analysis
13.3.2. Top 3 Companies Market Share Analysis
13.4. List of Potential Customers
List of Figures
Figure 1: Global ASEAN Warehousing and Distribution Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Indonesia ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 3: Indonesia ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 4: Indonesia ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 5: Indonesia ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 6: Indonesia ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 7: Indonesia ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 8: Indonesia ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 9: Indonesia ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Thailand ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 11: Thailand ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 12: Thailand ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 13: Thailand ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 14: Thailand ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 15: Thailand ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 16: Thailand ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Thailand ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Vietnam ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 19: Vietnam ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 20: Vietnam ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 21: Vietnam ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 22: Vietnam ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 23: Vietnam ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 24: Vietnam ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Vietnam ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Singapore ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 27: Singapore ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 28: Singapore ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 29: Singapore ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 30: Singapore ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 31: Singapore ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 32: Singapore ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 33: Singapore ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
Figure 34: Malaysia ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 35: Malaysia ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 36: Malaysia ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 37: Malaysia ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 38: Malaysia ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 39: Malaysia ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 40: Malaysia ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: Malaysia ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Philippines ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 43: Philippines ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 44: Philippines ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 45: Philippines ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 46: Philippines ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 47: Philippines ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 48: Philippines ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: Philippines ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
Figure 50: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue (Billion), by Warehouse Type 2026 & 2034
Figure 51: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Share (%), by Warehouse Type 2026 & 2034
Figure 52: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 53: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 54: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue (Billion), by End-User Industry 2026 & 2034
Figure 55: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Share (%), by End-User Industry 2026 & 2034
Figure 56: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue (Billion), by Country 2026 & 2034
Figure 57: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 2: Global ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 3: Global ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 4: Global ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Indonesia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 6: Indonesia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 7: Indonesia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 8: Indonesia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Thailand ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 10: Thailand ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 11: Thailand ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 12: Thailand ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: Vietnam ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 14: Vietnam ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 15: Vietnam ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 16: Vietnam ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Singapore ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 18: Singapore ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 19: Singapore ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 20: Singapore ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Malaysia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 22: Malaysia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 23: Malaysia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 24: Malaysia ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Philippines ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 26: Philippines ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 27: Philippines ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 28: Philippines ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 29: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Warehouse Type 2020 & 2034
Table 30: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 31: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 32: Rest of ASEAN ASEAN Warehousing and Distribution Industry Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the ASEAN warehousing and distribution industry market size?
The market was valued at USD 31.31 billion in 2025 and is projected to reach USD 42.49 billion by 2031, growing at a CAGR of 5.11% from 2026 to 2031, according to our proprietary primary research.
2Which country dominates the ASEAN warehousing market?
Indonesia held the largest share at 20.60% in 2025, driven by its large population and expanding manufacturing base, though Vietnam is forecast to grow fastest at 5.87% CAGR.
3What are the key drivers of the ASEAN warehousing market?
Key drivers include the omnichannel retail surge (+1.1% CAGR impact), the China+1 manufacturing shift (+0.9%), accelerated 3PL outsourcing by SMEs (+0.7%), and LEO satellite IoT enabling rural connectivity (+0.5%).
4Which segment is fastest-growing in the ASEAN warehousing market?
Refrigerated warehousing is the fastest-growing warehouse type at 6.09% CAGR, while pharmaceutical and healthcare is the fastest-growing end-user industry at 6.50% CAGR through 2031.
5Who are the major companies in the ASEAN warehousing and distribution market?
Major players include DHL Supply Chain, CEVA Logistics, Century Logistics, DSV, Linfox, XPO Logistics, Kuehne + Nagel, C.H. Robinson, DB Schenker, Geodis, UPS Supply Chain Solutions, Nippon Express, and Ryder System.
6What is the impact of China+1 on ASEAN warehousing?
The China+1 manufacturing shift is amplifying intra-ASEAN distribution flows, with USD 239 billion in manufacturing FDI in 2024 spreading production across Vietnam, Thailand, and Indonesia, driving demand for multi-country inventory pools and regional distribution centers.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted exhaustive interviews with senior executives across the ASEAN warehousing and distribution value chain, including 3PL operators, e-commerce fulfillment directors, and real estate developers.
Our primary research accounted for 70-80% of total research effort, ensuring deep, first-hand insights into operational dynamics and strategic decision-making.
We interviewed stakeholders such as Supply Chain Directors, Warehouse Operations Managers, and Procurement Heads to capture granular data on capacity utilization, automation adoption, and outsourcing trends.
Primary interviews were complemented by on-site facility visits and operational data sharing under non-disclosure agreements, providing validated metrics on throughput, costs, and service levels.
We engaged with industry associations including the ASEAN Federation of Logistics Associations (AFLA) and the Singapore Logistics Association (SLA) to benchmark findings against broader industry standards.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Supply Chain Director
30%
Warehouse Operations Manager
30%
Procurement Head
25%
Logistics Technology Lead
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
3PL Operators
35%
E-commerce Fulfillment Providers
20%
Warehouse Real Estate Developers
15%
Automation & Technology Vendors
15%
Manufacturers & Retailers (Captive)
15%
Secondary Research & Industry Benchmarking
Our secondary research (20-30% of effort) involved rigorous analysis of official multilateral sources, including UN Comtrade for trade flow data, World Bank logistics performance indicators, and ASEAN Secretariat statistics.
We referenced financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook to validate company financials, M&A activity, and investment patterns.
Industry benchmarks were derived from recognized non-profit technical standards and trade associations, including the International Warehouse Logistics Association (IWLA) and the Global Cold Chain Alliance (GCC).
All secondary data was cross-referenced with our proprietary primary research to ensure consistency and accuracy, with discrepancies resolved through follow-up expert consultations.
Demand Modeling & Market Estimation
We employed both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up approach: We built market size from granular quantitative metrics, including warehouse floor space (sqm) by country, average rental rates (USD/sqm/month), and occupancy rates.
Top-down approach: We cross-checked against macroeconomic indicators such as logistics sector GDP contribution, trade volumes, and e-commerce sales.
Demand modeling incorporated end-user industry spending on warehousing and distribution services, segmented by e-commerce, retail, pharma, automotive, and others.
We applied CAGR extrapolation based on historical trends (2020-2025) and forward-looking drivers, adjusting for country-specific dynamics and regulatory changes.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90%, achieved through rigorous methodological design and iterative validation.
Every data point was subjected to multi-level triangulation: primary interview data vs. secondary source data vs. our internal models.
We conducted sanity checks on all market size and forecast figures, comparing growth rates against GDP, trade, and e-commerce growth to ensure plausibility.
The report is updated to the date of purchase, incorporating the latest available data and insights, and is backed by our proprietary estimation framework.
All sources are documented and traceable, with a clear audit trail for transparency and credibility.