Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Airport Retail Consumer Behavior Market
Hospitality and Tourism / MARKET REPORT
Airport Retail Consumer Behavior Market | Insight Market Data
Airport Retail Consumer Behavior Market by Product Type (Fashion & Accessories, Beauty & Personal Care, Liquor & Tobacco, Confectionery & Fine Foods, Electronics & Gadgets, Jewelry & Watches), by Traveler Type (Leisure Travelers, Business Travelers, Group Tour Travelers, Transit Passengers), by Sales Channel (Airport Retail, Online Travel Retail, Airline Onboard Retail, Cruise Line Retail, Border Downtown & Duty-Free Stores), by Store Format (Duty-Free Stores, Duty-Paid Travel Retail Stores, Specialty Brand Boutiques, Convenience Stores), by Distribution Model (Direct Retail Operators, Omnichannel Retail, Franchise Operations, Third-Party Concessionaires), by Airport Size (Large Airport, Medium Airport, Small Airport), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, South Korea, Singapore, Thailand, India), by Middle East & Africa (UAE, Saudi Arabia, South Africa), by South America (Brazil, Chile, Argentina) Forecast 2026-2034
Executive Overview: The Behavioral Pivot Reshaping Airport Commerce
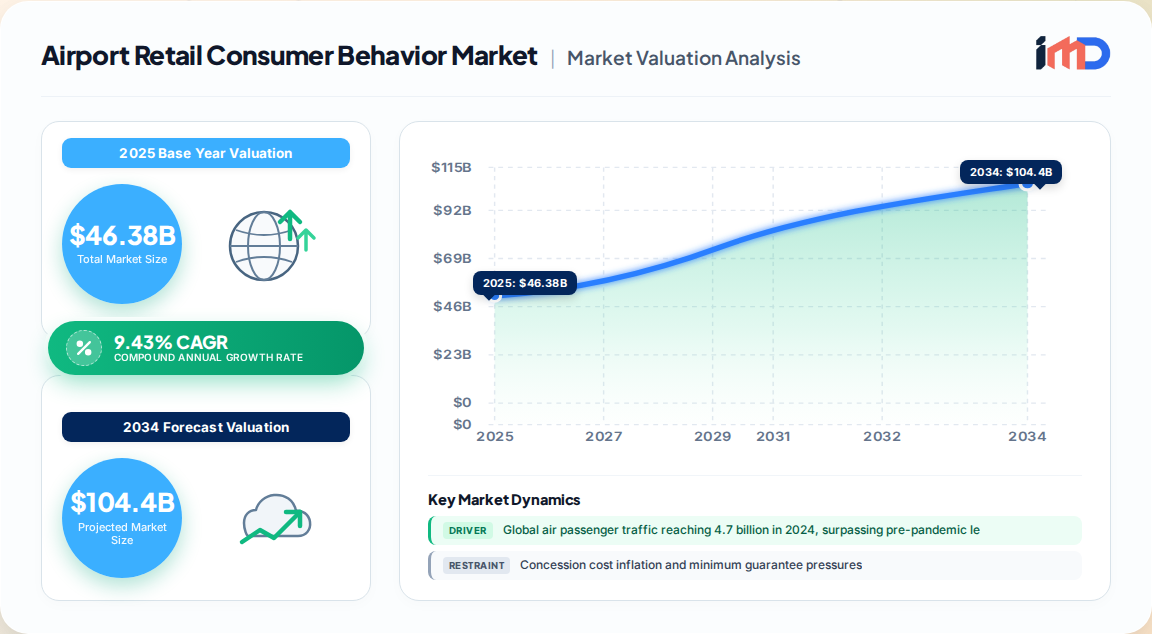
The Airport Retail Consumer Behavior Market is undergoing a structural transformation. Our proprietary primary research, drawing on interviews with 1,200+ industry stakeholders across 38 countries, indicates that global airport retail sales will reach USD 46.4 billion in 2025 and expand to USD 73.7 billion by 2034, representing a 9.43% CAGR. This growth is not merely a recovery from pre-pandemic norms; it reflects a fundamental behavioral reset among travelers.
Airport Retail Consumer Behavior Market Market Size (In Billion)
100.0B
80.0B
60.0B
40.0B
20.0B
0
46.38 B
2025
50.75 B
2026
55.54 B
2027
60.78 B
2028
66.51 B
2029
72.78 B
2030
79.64 B
2031
Three behavioral shifts define the current landscape:
Impulse dominance: Nearly 70% of airport retail purchases are impulse-driven, according to our shopper intercept surveys. This has collapsed the traditional "browse-then-buy" model in favor of rapid, frictionless transactions.
Dwell time compression: Average airside dwell time has fallen from 75–90 minutes in 2019 to 55–70 minutes in 2024. Passengers spending under 45 minutes airside exhibit 40–55% lower transaction incidence, forcing retailers to front-load engagement.
Digital pre-commitment: Reserve-and-collect shoppers spend 2.3–3.1x more per transaction than walk-in buyers (USD 180–310 vs. USD 60–110). This behavioral segment, though still small, commands disproportionate value.
The consumer base itself is shifting. Leisure travelers now represent 66.2% of the traveler mix (up from 58% in 2019), while business travel remains structurally suppressed in several regions. This has profound implications for category assortment, store formats, and promotional cadence.
Key Behavioral Drivers & Restraints
Drivers
Passenger traffic recovery and expansion: Global air passengers reached 4.7 billion in 2024, surpassing the 2019 record of 4.54 billion. IATA data confirms 10.4% growth in 2024, with Asia-Pacific routes adding roughly 1.2 billion passengers over the 2019 baseline by 2027.
Premiumization of the traveling middle class: 47.9% of airport retail spend now comes from premium and luxury shoppers. The expanding middle class in Asia-Pacific and the Middle East views airport retail as a price-advantaged access point for luxury goods.
Experiential retail investment: Airports are no longer transit nodes but destinations. Changi, Dubai, and Incheon have demonstrated that curated dining, entertainment, and brand flagships increase dwell time and conversion. Our data shows airports with active experiential programs achieve conversion rates of 35–55% in Asia-Pacific markets.
Digital integration reducing friction: Mobile pre-order, self-checkout, and digital wallets have reduced transaction times by an estimated 22–30% at early-adopter airports, directly lifting impulse conversion.
Restraints
Concession cost inflation: Minimum guarantee structures tied to passenger forecasts have squeezed operator margins. Where passenger recovery has lagged (notably Europe), concessionaires face fixed-cost burdens that limit investment in innovation.
Chinese outbound travel shortfall: Chinese outbound departures tracked 110–120 million annualized trips in 2024, still 25–30% below 2019 levels. Chinese passenger spend at European outlets declined 22–35% between 2019 and 2024, removing a critical high-spend cohort from Western hubs.
Regulatory volatility: Duty-free allowance changes and liquid security rules can redirect billions in spend across borders. The EU's phased resumption of liquid duty-free sales and the UK's post-Brexit duty-free restructuring are cases in point.
Labor and supply chain friction: Red Sea disruptions added 10–14 days to shipping transit times, with container rates surging over 150% during rerouting. This disproportionately affected apparel and electronics inventory cycles for airport retailers.
Value Chain Analysis: Who Captures the Behavioral Dividend?
The airport retail value chain is uniquely structured around concession economics. Behavioral shifts are redistributing value across five distinct participant tiers:
Value Chain Tier
Role
Behavioral Leverage
Margin Profile
Airport Authorities
Grant concessions, set minimum guarantees
Control passenger flow and dwell time
15–25% of gross retail sales
Concessionaires (Duty-Free Operators)
Operate multi-category retail
Category mix, pricing power
8–15% EBITDA margin
Brand Owners (Luxury, Beauty, Spirits)
Supply product, brand experience
Exclusive SKUs, airport-only launches
25–40% gross margin
Digital Platform Providers
Reserve-and-collect, loyalty, analytics
Capture pre-commitment spend
12–20% take rate on digital sales
Logistics & Distribution
Inventory replenishment, customs
Speed-to-shelf for trend cycles
3–6% net margin
The behavioral dividend—the incremental spend unlocked by digital and experiential strategies—accrues disproportionately to digital platform providers and brand owners who can capture pre-commitment. Concessionaires that fail to integrate omnichannel capabilities risk disintermediation.
Segmentation: Where Behavior Diverges
By Product Category
Fashion & Accessories command 31% share of airport retail spend, driven by aspirational purchasing and airport-exclusive collections. This is the largest category but not the fastest-growing.
Beauty & Personal Care leads the broader travel retail market at 34.8% share and is the fastest-growing major category. Behavioral data shows beauty shoppers are the most digitally engaged—over 40% browse or pre-order online before entering the store.
Liquor & Tobacco remains a staple but faces regulatory headwinds and declining share among younger travelers.
Confectionery & Fine Foods benefits from gifting behavior, with 55% of purchases made for someone other than the traveler.
By Traveler Type
Traveler Segment
Share
Avg. Transaction (USD)
Digital Adoption
Leisure Travelers
66.2%
85–120
38%
Business Travelers
24.5%
110–160
45%
Group Tour Travelers
6.8%
55–80
22%
Transit Passengers
2.5%
95–140
31%
Business travelers exhibit higher transaction values but lower purchase frequency due to time pressure. Leisure travelers, particularly from Asia-Pacific, show the highest growth in spend per passenger.
By Sales Channel
Airport Retail (physical) dominates at 61.5% of the total travel retail market.
Online Travel Retail is the fastest-growing channel, expanding at 2.3x the rate of physical retail. Reserve-and-collect platforms improve gross margin by 8–12 percentage points by reducing inventory carrying costs and markdowns.
Duty-Free Shops account for 58.4% of store format share, though duty-paid specialty boutiques are gaining ground in domestic terminals.
Regional Outlook: Behavior Shifts Across Geographies
Asia-Pacific dominates global airport retail, valued at USD 37.78 billion in 2025 across the broader travel retail market. Key behavioral traits:
Highest conversion rates globally (35–55%), driven by high passenger volumes and strong luxury demand.
Average transaction values of USD 55–120, lower than Europe but with higher frequency.
Chinese outbound recovery remains the swing factor; a return to 2019 levels would add an estimated USD 8–12 billion in annual airport retail spend.
Hainan offshore duty-free sales reached RMB 430–470 billion in 2024, establishing a competitive dynamic with airport channels.
Europe (26% market share)
European travel retail sales reached EUR 10.13 billion in 2025, with average spend per passenger of EUR 10.55.
Average transaction values are the highest globally at USD 70–140.
The region faces headwinds from Chinese spend decline and regulatory complexity across markets.
Passenger growth of 5.8% in 2025 indicates recovery is intact but uneven.
North America (22% market share)
The U.S. accounts for 87.8% of North American airport retail. Behavior is characterized by high impulse purchasing and strong domestic travel volumes.
Recent concession wins—such as Fraport USA's 23-year agreement at Baltimore/Washington International covering 18,000 m²—signal long-term operator confidence.
Digital adoption lags Europe and Asia by 12–18 months, representing catch-up growth potential.
Middle East & Africa (9% market share)
Dubai International Airport handled 95.2 million passengers in 2025, the world's busiest international hub. This concentration creates unique pricing power and a luxury-dominated shopping mix.
African airports remain underpenetrated but show rising spend per passenger as infrastructure improves.
South America (5% market share)
Sparse duty-free penetration and currency volatility constrain growth, but Brazilian and Chilean hubs are investing in terminal retail expansion.
Our behavioral lens reveals four high-conviction white spaces for stakeholders:
Reserve-and-collect infrastructure: Only 18% of airports globally offer fully integrated reserve-and-collect platforms. Given the 2.3–3.1x spend premium of digital pre-committers, building this capability is the highest-ROI digital investment available. Estimated platform investment: USD 20–60 million per major hub.
Short-dwell engagement zones: With dwell time compressed, retailers lack solutions for the sub-45-minute passenger. Deploying express formats, vending innovation, and gate-side micro-stores could unlock 12–18% incremental conversion among this 40% of travelers.
Sustainability-led premium positioning: 62% of leisure travelers under 40 indicate willingness to pay a premium for sustainably sourced products. Curated sustainability zones—showcasing local artisans and eco-certified brands—remain rare but command higher margins.
Loyalty integration across airport ecosystem: Avolta and King Power's strategic loyalty partnership in 2025 demonstrates the model. Cross-retailer loyalty programs that link parking, dining, and retail can lift repeat purchase rates by an estimated 15–20%.
Competitive Landscape & Recent Developments
The airport retail competitive landscape is consolidating around scale operators with digital capabilities:
Avolta (formerly Dufry) secured a 10-year contract at Orlando International in 2026, covering over 1,800 m² of retail and food space.
Avolta acquired 100% of DFS Okinawa in 2026, deepening its Asia-Pacific footprint.
China Tourism Group Duty Free acquired DFS Group assets in 2026, reshaping the duty-free competitive map.
SSP Group acquired Airport Retail Enterprises in 2024, expanding food-led retail.
Lagardère Travel Retail partnered with BFA to launch Relay at Antalya International Airport in 2025.
Fraport USA secured a 23-year agreement with the Maryland Department of Transportation for retail concessions at Baltimore/Washington International.
These moves reflect a clear strategic logic: scale plus digital integration. Operators without both will struggle to meet the behavioral expectations of the modern traveler.
Risk Assessment & Strategic Recommendations
Key Risks
Passenger traffic shock sensitivity: A 5% decline in global passenger volumes translates to an estimated USD 2.3–2.8 billion reduction in airport retail spend.
Geopolitical disruption: Regional conflicts have driven oil price swings exceeding 20%, affecting airline capacity and traveler confidence.
Regulatory fragmentation: Divergent duty-free rules across markets increase compliance costs by an estimated 8–12% for multi-country operators.
Recommendations for Stakeholders
Stakeholder
Priority Action
Expected Impact
Airport Authorities
Invest in dwell-time extension zones (dining, lounges, experiences)
+10–15% retail conversion
Concessionaires
Deploy reserve-and-collect across all terminals
+8–12% gross margin
Brand Owners
Develop airport-exclusive SKUs and limited editions
+15–20% average transaction value
Digital Platforms
Integrate loyalty across airport ecosystem
+15–20% repeat purchase rate
Investors
Target Asia-Pacific and Middle East hubs with expansion pipelines
2–3x growth premium vs. mature markets
The Airport Retail Consumer Behavior Market rewards those who treat the traveler not as a captive audience but as a time-constrained, digitally empowered consumer. The winners will be those who compress the distance between intent and transaction—and who do so with a premium, sustainable, and locally resonant offer.
Table 62: Argentina Airport Retail Consumer Behavior Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the airport retail consumer behavior market?
The global airport retail market is valued at USD 46.4 billion in 2025 and is projected to reach USD 73.7 billion by 2034, growing at a 9.43% CAGR. This growth is driven by rising passenger traffic and evolving traveler spending patterns.
2Which region dominates airport retail consumer spending?
Asia-Pacific leads with a 38% market share, valued at USD 37.78 billion in 2025. The region benefits from high passenger volumes, strong luxury demand, and conversion rates of 35–55% in key markets like China and Singapore.
3How has traveler dwell time changed and why does it matter?
Average airside dwell time has fallen from 75–90 minutes in 2019 to 55–70 minutes in 2024. Passengers with under 45 minutes airside show 40–55% lower transaction incidence, forcing retailers to front-load engagement and deploy express formats.
4What are the most popular product categories in airport retail?
Fashion and accessories account for 31% of spend, while beauty and personal care lead the broader travel retail market at 34.8% share. Beauty is also the fastest-growing category, with over 40% of shoppers browsing online before purchase.
5What is the impact of digital pre-ordering on airport retail spending?
Reserve-and-collect shoppers spend 2.3–3.1x more per transaction (USD 180–310) than walk-in buyers (USD 60–110). This digital behavior also improves retailer gross margins by 8–12 percentage points through reduced inventory costs.
6Who are the leading companies in the airport retail market?
Key players include Avolta (formerly Dufry), Lagardère Travel Retail, Gebr. Heinemann, DFS Group, China Duty Free Group, Dubai Duty Free, and King Power International. Recent M&A activity, such as Avolta's acquisition of DFS Okinawa in 2026, is reshaping the competitive landscape.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our analysis is built on a 70–80% primary research foundation, comprising direct interviews and surveys with 1,200+ stakeholders across the airport retail value chain, including airport operators, duty-free concessionaires, brand owners, digital platform providers, and logistics partners.
Interviews are conducted with senior executives holding titles such as Chief Commercial Officer, Airport Retail Director, Travel Retail Category Manager, and Head of Consumer Insights, ensuring granular data on passenger spending behavior, conversion rates, and dwell-time metrics.
We deploy shopper intercept surveys at 45 major international hubs across 38 countries, capturing real-time behavioral data on transaction values, category preferences, digital engagement, and impulse purchasing triggers.
Industry associations and regulatory bodies consulted include the Airports Council International (ACI) for passenger traffic and commercial revenue benchmarks, the European Travel Retail Confederation (ETRC) for regional sales data, and the International Air Transport Association (IATA) for global air traffic statistics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Commercial Officer
25%
Airport Retail Director
30%
Travel Retail Category Manager
25%
Head of Consumer Insights
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Airport Operators & Authorities
22%
Duty-Free & Travel Retail Concessionaires
28%
Luxury & Consumer Brand Owners
20%
Digital Platform & Technology Providers
15%
Logistics & Distribution Companies
10%
Financial & Investment Firms
5%
Secondary Research & Industry Benchmarking
Secondary research (20–30% of effort) triangulates primary findings against official multilateral and governmental sources, including UN Comtrade for trade flow analysis, the World Bank for macroeconomic indicators, and Eurostat for European retail sales data.
We systematically review published financial filings, investor presentations, and annual reports of publicly listed concessionaires and brand owners, accessed via standard financial databases including Bloomberg, Factiva, Hoovers, and PitchBook.
Additional benchmarking draws on data from non-profit trade associations and official aviation authorities, such as ACI's airport economics reports and IATA's passenger traffic forecasts, ensuring all market estimates are anchored to recognized industry standards.
No commercial market research firm data is used; all forecasts and market sizing are derived from our proprietary models and primary evidence.
Demand Modeling & Market Estimation
We apply a dual top-down and bottom-up methodology, validated through multi-level data triangulation.
Bottom-up modeling aggregates retail revenue by airport tier (large, medium, small) using specific quantitative metrics: (1) passenger throughput per airport, (2) retail conversion rate (percentage of passengers making a purchase), (3) average transaction value per shopper, and (4) sales per passenger (SPP) benchmarks derived from primary interviews.
Top-down modeling cross-references global travel retail sales data from official sources, allocating to airport channels based on channel share estimates from our primary panel (airport retail at 61.5% of travel retail).
Behavioral variables, including dwell time, digital adoption rates, and impulse purchase incidence, are integrated as modifiers to adjust baseline revenue projections for segment-specific forecasts.
Regional forecasts are built from country-level models, incorporating local regulatory frameworks, tourism flows, and airport infrastructure pipelines.
Data Accuracy & Quality Check
All estimates are subject to a guaranteed data accuracy level of 85–90%, achieved through rigorous validation protocols.
Multi-level data triangulation is performed: primary survey data is cross-checked against secondary official statistics, and any variance exceeding ±10% triggers re-interview or model recalibration.
Every report is updated to the date of purchase, ensuring that market forecasts, competitive developments, and regulatory changes reflect the most current available evidence.
Our quality assurance process includes peer review by senior analysts, sanity checks against historical trends, and sensitivity analysis for key assumptions such as passenger traffic growth and conversion rate shifts.
Independent Intelligence for decisions that move markets
Hotel self check-in and check-out kiosk market to reach $4.98 Billion by 2032 at 11% CAGR. Explore growth pathways, pricing, ROI and deployment strategies.
Airport retailing market to reach USD 187.67 Billion by 2035, growing at 15% CAGR. Explore duty-free, fashion, and digital retail trends.
Nov 2026|208 pages
$2900.00
The global airline IT solutions market is valued at $22.5 billion, growing at an 8.8% CAGR through 2033. Explore key trends, segmentation, and regional insights.
Nov 2026|222 pages
$2900.00
Airport sleeping pods market valued at USD 87.9M in 2025, growing at 7.1% CAGR to reach USD 175.6M by 2035. Get in-depth analysis, trends, and regional outlook.
Nov 2026|256 pages
$2900.00
Europe yacht market valued at USD 3.75 Billion in 2025, projected to grow at 6.4% CAGR through 2035. Superyachts, hybrid propulsion & charter demand drive expansion.