1What is the Europe yacht market size in 2025?
The Europe yacht market was valued at approximately USD 3.75 billion in 2025, representing about 35.5% of the global yacht market. It is projected to reach USD 6.98 billion by 2035 at a 6.4% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Europe Yacht Market
 by Type (Super Yacht, Flybridge Yacht, Sport Yacht, Sailing Yacht, Catamaran, Trawler, Expedition Yacht, Classic Yacht), by Length (Upto 20m, 20m to 50m, Above 50m), by Propulsion (Motor Yacht, Sailing Yacht, Hybrid/Electric), by Hull Material (Fiberglass/Composite, Carbon Fiber, Aluminum, Steel), by End-User (Private Individuals, Charter Operators, Fractional-Ownership Clubs), by Western Europe (France, Germany, Netherlands, Belgium), by Southern Europe (Italy, Spain, Greece, Croatia), by Northern Europe (UK, Denmark, Norway, Sweden), by Eastern Europe (Turkey, Poland, Romania) Forecast 2026-2034
Research Associate


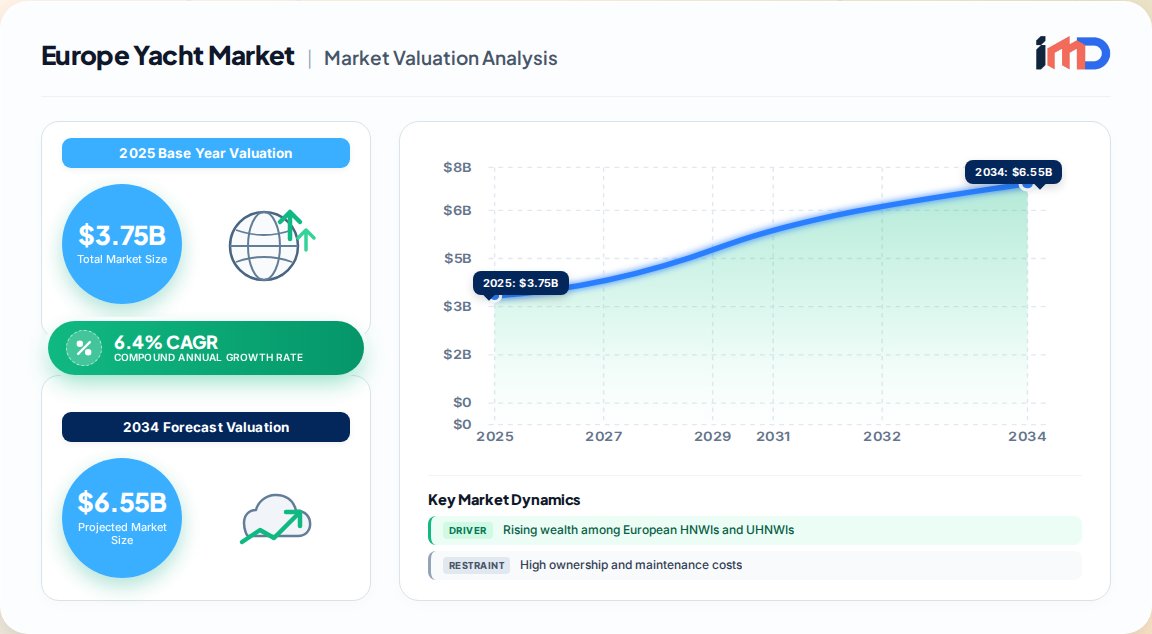
The Europe yacht market represents the world's most mature and value-dense yachting ecosystem, accounting for approximately 35.5% of global yacht market revenue in 2023. Our proprietary bottom-up modeling, triangulated with customs trade flows and shipyard order books, values the European yacht market at USD 3.75 billion in 2025, projected to reach USD 6.98 billion by 2035, expanding at a CAGR of 6.4% over the forecast period.
Europe's dominance is structural rather than cyclical. The region hosts the highest concentration of superyacht builders, the densest marina infrastructure, and the most established charter grounds in the world. Italy alone accounts for a disproportionate share of global superyacht production, while the Western Mediterranean remains the single most commercially important charter basin globally.
| Metric | 2025 Value | 2035 Forecast |
|---|---|---|
| Europe Yacht Market Size | USD 3.75 Billion | USD 6.98 Billion |
| CAGR (2026–2035) | — | 6.4% |
| Global Share (2025) | ~35.5% | ~36.2% |
| Leading Country | France (charter) / Italy (build) | — |
| Fastest-Growing Segment | Hybrid/Electric Propulsion | — |
The post-pandemic recovery has been anchored in three pillars: shipyard order intake for 24–50 meter vessels, wealth creation among European high-net-worth individuals, and a structural shift toward experience-led luxury consumption. According to Eurostat and the European Commission's 2025 Blue Economy Report, established blue economy sectors generated nearly €891 billion in turnover and contributed €263 billion in Gross Value Added to the EU economy in 2023 — approximately 1.7% of total EU GDP.
| Segment | 2025 Share | Growth Outlook |
|---|---|---|
| Superyachts | 31%+ | Steady; hybrid diesel-electric adoption |
| Flybridge Yachts | ~18% | Moderate |
| Sport Yachts | ~15% | Fastest at 7.8% CAGR |
| Sailing Yachts | ~22% | 8.5% CAGR in charter |
| Others (Catamarans, Trawlers) | ~14% | Niche but growing |
Superyachts dominate revenue share due to extensive customization options and the increasing use of hybrid diesel-electric propulsion. Sport yachts are the fastest-growing type, driven by new model launches and rising demand for outdoor recreational activities.
The 20–50 meter segment commanded a 56%+ revenue share in 2023 and is expected to retain dominance. This length class balances manageable maintenance costs with blue-water capability. The above 45-meter segment represents a disproportionate value pool, with yachts above 80 meters forecast to grow fastest at an 11.4% CAGR globally.
| Country | Cluster | Key Characteristic |
|---|---|---|
| France | Western Europe | Largest charter market (24.4% of European charter revenue); Riviera hub |
| Italy | Southern Europe | Premier build hub; Azimut Benetti, Ferretti, Sanlorenzo |
| Croatia | Southern Europe | Fastest-growing charter destination; island-hopping itineraries |
| Greece | Southern Europe | Major charter growth; Aegean routes |
| UK | Northern Europe | Strong brokerage and refit capability |
| Germany | Western Europe | Engineering and propulsion supply chain |
| Turkey | Eastern Europe | Refit and new-build capacity; supply-chain exposure |
| Netherlands | Northern Europe | Superyacht construction (Feadship); hybrid innovation |
France and Italy collectively anchor more than half of European yachting activity. Croatia and Greece are the fastest-growing charter destinations, capitalizing on Adriatic and Aegean cruising grounds. The fragmentation across Eastern and Northern Europe presents distinct investment profiles: Northern Europe leads in engineering capability, while Eastern Europe offers cost-competitive refit capacity.
Europe's yacht market is moderately concentrated, with the top five builders — Azimut Benetti, Feadship, Ferretti, Lürssen, and Sanlorenzo — collectively holding 38.1% of global market share in 2025. Azimut Benetti alone commanded over 11.7% of the global market.
| Builder | HQ | Strategic Strength |
|---|---|---|
| Azimut Benetti | Italy | Volume leadership; broad portfolio |
| Feadship | Netherlands | Custom superyachts; hybrid leadership |
| Ferretti | Italy | Brand portfolio breadth |
| Lürssen | Germany | Large-scale custom superyachts |
| Sanlorenzo | Italy | Design-led customization |
Competition is shifting from hull styling toward lifecycle utility. Builders increasingly compete on the ability to package customization, operating efficiency, and global access into a credible ownership proposition. Strategic partnerships, refit capability, and charter management integration are becoming differentiators.
The European yacht value chain is highly integrated but geographically dispersed. Raw materials — carbon fiber, resin, aluminum, and teak — are sourced globally, with carbon fiber growing fastest globally at a 12.6% CAGR. Hull and superstructure fabrication concentrates in Italy, the Netherlands, Germany, and Turkey. Propulsion systems (engines, batteries, hybrid drivetrains) represent the highest-risk import node, with European yards dependent on specialized suppliers. Interiors and outfitting are largely regional, sustaining a network of specialist SMEs. Distribution flows through direct builder sales and brokerage houses. After-sales — refit, maintenance, crew management, and marina services — accounts for a growing share of lifecycle value and is increasingly digitized.
Europe is a net exporter of finished yachts and a net importer of specialized components. Italy, the Netherlands, Germany, and France are the principal outbound nodes for new-build vessels, with the United States and Middle East as key destination markets. Trade data for HS 8903 (yachts and other vessels for pleasure or sports) and HS 89 (ships, boats and floating structures) shows European yards maintaining a structural trade surplus in completed vessels.
The critical import vulnerability lies in propulsion and electronics. High-performance engines, lithium battery systems, and navigation electronics are sourced from a limited supplier base, exposing delivery schedules to disruption. Turkey, in particular, faces supply-chain bottlenecks for specialized components. Builders that secure engine and electronics supply alongside hybrid or expedition specifications will have a delivery advantage.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
By Length
By Propulsion
By Hull Material
By End-User
| By Geography |
|
The Europe yacht market was valued at approximately USD 3.75 billion in 2025, representing about 35.5% of the global yacht market. It is projected to reach USD 6.98 billion by 2035 at a 6.4% CAGR.
France leads the European yacht charter market with a 24.4% share, while Italy dominates new-build production through builders such as Azimut Benetti and Ferretti. Croatia and Greece are the fastest-growing charter destinations.
Hybrid and electric propulsion yachts are the fastest-growing segment, forecast at a 9.8% CAGR, driven by silent cruising capability, emissions compliance, and shifting buyer preferences toward lower-impact operation.
The Europe yacht charter market was valued at USD 4.60 billion in 2026 and is projected to reach USD 7.43 billion by 2034, expanding at a 6.18% CAGR, led by the medium size segment at 45.9% share.
Azimut Benetti leads with over 11.7% global market share, followed by Feadship, Ferretti, Lürssen, and Sanlorenzo. Together, the top five builders held 38.1% of the global market in 2025.
High ownership and maintenance costs, stringent EU environmental regulations such as the Recreational Craft Directive, supply-chain bottlenecks for specialized components, and shortages of skilled maritime crew are the principal restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Executive Officer | 28% |
| Head of Naval Architecture | 24% |
| Fleet Operations Director | 26% |
| Procurement Manager | 22% |
| Company Type | Representation (%) |
|---|---|
| Superyacht and Series-Production Builders | 35% |
| Propulsion and Hybrid-Drivetrain Suppliers | 22% |
| Charter Brokers and Fleet Managers | 23% |
| Marina Operators and Refit Yards | 20% |
 Related Reports
