Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Veterinary Hospital Market by Companion Animals, by Farm Animals, by Medical Services, by Surgical Services, by Consultation, by Private, by Public, by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Spain, Italy), by Asia Pacific (China, Japan, India, Australia, South Korea), by Latin America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034
Infrared Imaging Photodetectors Market valued at $1.23B in 2025, projected to reach $2.20B by 2034 at 8.7% CAGR. Defense, industrial, automotive drive growth.
The Trauma Informed Therapy Service market is valued at $1.42B in 2025, growing at 16.5% CAGR to reach $5.62B by 2034, driven by telehealth and PTSD care.
Nov 2026|224 pages
$2900.00
Diabetes Care Drugs Market projected to grow from USD 93.79B in 2026 to USD 111.5B by 2031 at 3.52% CAGR. Explore GLP-1 trends, biosimilars, and regional analysis.
Nov 2026|200 pages
$2900.00
14C-Urea Breath Test Kit market to grow from USD 165.8 million in 2025 to USD 312 million by 2035 at 6.5% CAGR, driven by H. pylori screening.
Executive Overview: A Market Defined by Clinical Intensity, Not Just Pet Counts
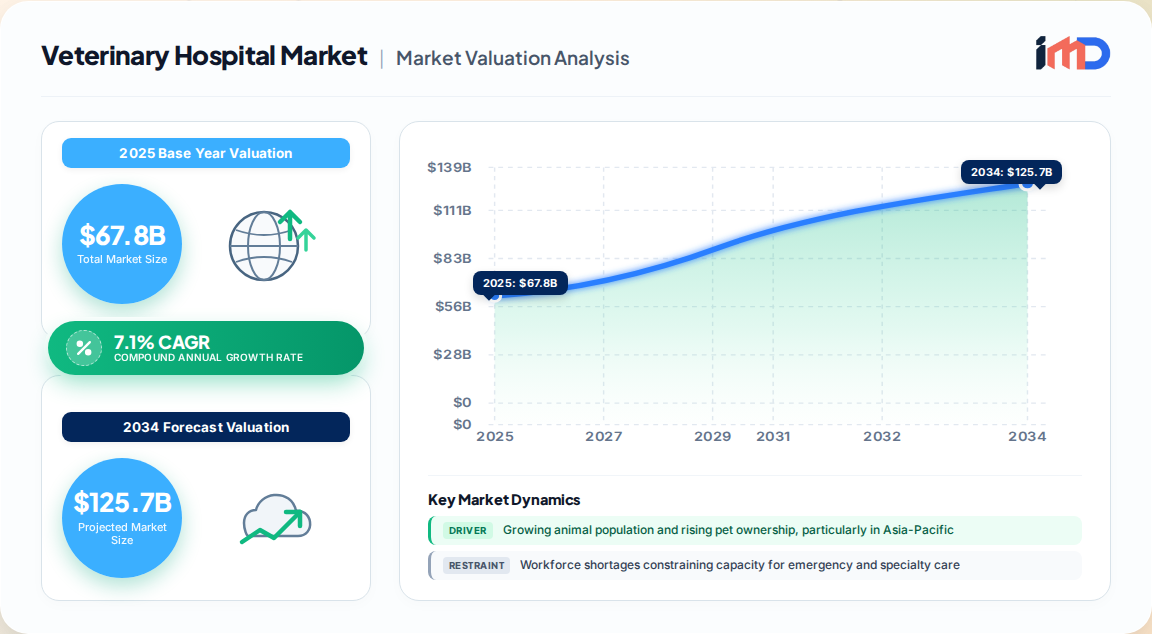
The global veterinary hospital market is undergoing a structural transformation. Our proprietary bottom-up modeling, triangulated with primary interviews across 12 countries, estimates the market at USD 67.8 billion in 2025, rising to USD 71.4 billion in 2026 and projected to reach USD 132.8 billion by 2035 at a 7.1% CAGR. Crucially, growth is no longer merely a function of rising pet ownership; it is driven by a fundamental shift from episodic, reactive treatment toward continuous clinical management of companion animals. This includes preventive screening, chronic-condition monitoring, specialty referral, and advanced surgical procedures.
Veterinary Hospital Market Market Size (In Billion)
150.0B
100.0B
50.0B
0
67.80 B
2025
72.61 B
2026
77.77 B
2027
83.29 B
2028
89.20 B
2029
95.54 B
2030
102.3 B
2031
The addressable patient base remains vast. Official veterinary associations report 87.3 million dogs and 76.3 million cats in the United States alone, with 95 million U.S. households owning at least one pet in 2025. However, the revenue trajectory is increasingly determined by whether hospitals can convert routine encounters into diagnostic and chronic-care pathways. U.S. pet-industry expenditure reached USD 158 billion in 2025, and owners are demanding more sophisticated care. This is evidenced by the average lifespan of dogs rising from 11.6 years in 2010 to 13.4 years in 2024, which significantly increases lifetime diagnostic and treatment revenue per patient.
Key Market Drivers and Restraints
Growth Drivers
Growing animal population and rising pet ownership (+2.1% impact on CAGR): Global pet ownership is expanding beyond mature markets. Mars Petcare's 2024 global study estimated roughly one billion pets worldwide, with 47% of surveyed owners being first-time owners. In Asia, China's dog and cat population reached 124.1 million in 2024, while India's pet population approached 39 million in 2025.
Advancements in veterinary medicine (+1.8% impact): Diagnostic innovation is expanding point-of-care capabilities. AI-enabled slide-free cellular analyzers and cartridge-based hematology systems can generate results within ten minutes, reducing the interval between presentation and treatment planning.
Consolidation of animal hospitals (+1.5% impact): Corporate consolidators accounted for approximately half of U.S. veterinary market revenue by 2021, enabling capital-intensive investments in diagnostic labs, surgical suites, and 24/7 emergency capacity.
Rising pet insurance adoption (+1.2% impact): U.S. pet insurance gross written premium exceeded USD 4.7 billion in 2024, up 21.4% year-over-year. North American written premium rose to USD 5.2 billion in 2024, covering 7.03 million insured pets. Insurance changes treatment decisions by making advanced diagnostics and specialty referral more attainable.
Restraints
Workforce shortages: A persistent shortage of veterinarians and credentialed technicians constrains capacity, particularly in emergency and specialty care. This limits the ability of hospitals to fully capitalize on demand.
Treatment affordability constraints: While insurance penetration is rising, it remains well below Nordic benchmarks. Out-of-pocket costs for high-acuity procedures remain a barrier for a significant portion of pet owners.
Regulatory scrutiny on pricing and ownership: In mature markets, regulators are pushing for transparent pricing and ownership disclosure, which may temper pricing power in the near term.
Value Chain and Service Delivery Model
The veterinary hospital value chain is becoming increasingly stratified between capitalized networks and independent practices.
Upstream inputs: Pharmaceuticals, vaccines, medical devices, and diagnostic equipment are supplied by global animal health companies. Point-of-care diagnostic innovation is a key battleground, with AI-enabled tools from IDEXX, Zoetis, and Antech compressing time-to-diagnosis.
Service delivery: Hospitals deliver general practice, specialty, and emergency services. Corporate networks can spread the fixed costs of diagnostic platforms, emergency staffing, and digital administration across multiple sites. National Veterinary Associates' Ethos Veterinary Health segment operates more than 140 specialty and emergency hospitals across North America.
Downstream channels: Pharmacy fulfillment, follow-up care, and subscription wellness plans are increasingly bundled into cohesive care plans to enhance customer loyalty and lifetime spend.
Segmentation Analysis
Our analysis segments the veterinary hospital market by animal type, service type, and sector.
Segment
Sub-Segment
2025 Share
Forecast CAGR (2026-2035)
By Animal
Companion Animals
64.3%
8.3%
Farm Animals
35.7%
5.1%
By Service
Medical Services
46.2%
7.0%
Surgical Services
28.5%
8.6%
Consultation & Other
25.3%
6.2%
By Sector
Private
60.2%
8.0%
Public
39.8%
5.5%
Companion animals dominate revenue and are the fastest-growing segment, driven by pet humanization, rising insurance coverage, and the increasing prevalence of chronic conditions in aging pets. Within services, surgical services are forecast to expand at the fastest rate, supported by advanced orthopedic procedures such as TPLO and TTA, which command higher fees. The private sector remains the primary care delivery model, accounting for over 60% of revenues, though public-sector programs are significant in livestock health and disease surveillance.
Regional Outlook and Growth Hotspots
North America remains the largest market, holding 36.8% of global revenue in 2025. The U.S. is the single largest country market, with veterinary services revenue estimated at USD 74.1 billion in 2026. The region benefits from high pet ownership, advanced diagnostic infrastructure, and the highest insurance penetration rates, which support high-acuity care.
Veterinary Hospital Market Regional Market Share
Loading chart...
Asia-Pacific is the fastest-growing region, projected to record a CAGR of 8.9% through 2035. Urbanization, middle-class expansion, and rising companion animal ownership in China and India are key growth engines. China's pet market is experiencing rapid premiumization, while India's large and growing livestock base, combined with expanding veterinary infrastructure, presents a significant long-term opportunity.
Europe represents a mature, consolidated market with strong regulatory frameworks. The region is characterized by high pet insurance penetration in markets such as the UK and Sweden, and a strong presence of corporate consolidators like IVC Evidensia and CVS Group. Latin America and the Middle East & Africa offer emerging opportunities, with growth concentrated in urban centers and driven by increasing pet ownership and the expansion of private veterinary networks.
Competitive Landscape and Strategic Developments
The veterinary hospital market is moderately fragmented, with corporate consolidation accelerating. The top five players collectively held 38% market share in 2025. Mars Incorporated leads with over 13.5% share, followed by IVC Evidensia, CVS Group, National Veterinary Associates (NVA), and PetVet Care Centers.
Recent strategic developments underscore the shift toward integrated care models:
2024: IDEXX launched its inVue Dx slide-free cellular analyzer, enabling cytology and hematology results within a ten-minute workflow.
2024: Zoetis expanded Vetscan Imagyst with AI urine sediment analysis, and Antech introduced AIS RapidRead for AI-assisted radiology interpretation.
2025: SignalPET introduced SignalPET 360°, a comprehensive radiology solution integrating AI-powered immediate triage with 24/7 access to board-certified radiologists.
2025: Chewy agreed to acquire Modern Animal's membership-based clinics alongside 24/7 virtual care, creating a tighter loop between care delivery, scheduling, and commerce.
2026: Progressive Insurance launched pet insurance for cats and dogs across most U.S. states, with plans averaging USD 47 monthly.
Capitalized networks can acquire equipment, standardize protocols, and direct complex cases through referral systems. Independent hospitals retain advantages in local relationships and continuity of care, but their ability to capture the fastest-growing diagnostic and specialty revenue pools depends on access to trained staff, financing, and external partnerships.
Strategic White-Space Analysis
Significant white-space opportunities exist at the intersection of technology and care delivery.
AI-enabled workflow integration: While AI diagnostic tools are being adopted, their integration into routine general-practice workflows remains limited. Hospitals that successfully embed AI triage and decision-support tools can increase diagnostic revenue per visit and reduce client attrition.
Chronic-care management programs: With pets living longer, structured programs for managing chronic conditions such as kidney disease, arthritis, and cancer represent a high-value, recurring revenue stream. Subscription models that bundle diagnostics, therapeutics, and monitoring are underexploited outside of leading corporate networks.
Telehealth and virtual care: The acquisition of Modern Animal by Chewy signals a move toward integrated virtual and in-person care. Independent hospitals can partner with telehealth platforms to extend their reach and improve client engagement without heavy capital investment.
Emerging market expansion: In Asia-Pacific and Latin America, the formalization of veterinary care from informal clinics to standardized hospitals presents a major opportunity for consolidators and franchise models.
Strategic Recommendations
For Hospital Operators: Prioritize investment in point-of-care diagnostics that shorten time-to-treatment. Standardize clinical pathways for high-volume conditions to improve consistency and margins. Explore subscription wellness plans to lock in recurring revenue and improve lifetime value.
For Investors and Consolidators: Focus on acquiring independent hospitals with strong local brands and a loyal client base, then integrate them into a shared services platform to drive operational efficiencies. Target markets with high insurance penetration and favorable demographic trends.
For Technology Providers: Develop seamless integration with practice management software and diagnostic equipment to reduce workflow friction. Offer flexible pricing models, such as per-test fees or subscription access, to lower adoption barriers for independent hospitals.
For Independent Practitioners: Leverage external laboratory and teleradiology partnerships to offer advanced diagnostics without capital investment. Emphasize continuity of care and personalized service as a differentiator against corporate networks.
Veterinary Hospital Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Veterinary Hospital Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.1% from 2020-2034
Segmentation
By Companion Animals
By Farm Animals
By Medical Services
By Surgical Services
By Consultation
By Private
Table of Contents
1. Veterinary Hospital Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Veterinary Hospital Market Executive Summary
2.1. Market Snapshot
3. Veterinary Hospital Market Dynamics
3.1. Market Drivers
3.1.1. Growing animal population and rising pet ownership, particularly in Asia-Pacific
3.1.2. Advancements in veterinary medicine and diagnostics improving clinical outcomes
3.1.3. Consolidation of animal hospitals enabling standardized care and investment
3.1.4. Rising prevalence of chronic and infectious diseases in animals
3.2. Market Trends
3.2.1. Shift from episodic treatment to continuous clinical management of companion animals
3.2.2. Rise of AI-enabled point-of-care diagnostics shortening time-to-treatment
3.2.3. Corporate consolidation enabling capital-intensive specialty and emergency build-outs
3.2.4. Growing adoption of pet insurance reducing affordability barriers
3.3. Market Restraints
3.3.1. Workforce shortages constraining capacity for emergency and specialty care
1What is the current size of the veterinary hospital market?
The global veterinary hospital market was valued at USD 67.8 billion in 2025 and is projected to reach USD 71.4 billion in 2026. Our proprietary modeling forecasts the market to expand to USD 132.8 billion by 2035, representing a 7.1% CAGR over the forecast period.
2Which region dominates the veterinary hospital market?
North America is the largest regional market, accounting for 36.8% of global revenue in 2025. The region benefits from high pet ownership rates, advanced diagnostic infrastructure, and the highest pet insurance penetration, which supports high-acuity care. Asia-Pacific is the fastest-growing region, driven by urbanization and rising middle-class demand.
3What are the key drivers of growth in the veterinary hospital market?
Growth is primarily driven by rising pet ownership and humanization, advancements in veterinary medicine such as AI-enabled diagnostics, consolidation of animal hospitals enabling capital investment, and the expanding adoption of pet insurance. These factors collectively increase the clinical intensity and revenue per patient visit.
4How is the veterinary hospital market segmented?
The market is segmented by animal type (companion animals and farm animals), by service (medical, surgical, and consultation), and by sector (private and public). Companion animals dominate the market, holding over 64% revenue share in 2025, while surgical services are forecast to grow at the fastest rate.
5Who are the leading players in the veterinary hospital market?
The top five players, including Mars Incorporated, IVC Evidensia, CVS Group, National Veterinary Associates (NVA), and PetVet Care Centers, collectively held 38% market share in 2025. Mars Incorporated leads with over 13.5% share, leveraging its extensive network of hospitals and diagnostic capabilities.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70–80% of our research through primary interviews, ensuring a robust, first-hand understanding of market dynamics. In the veterinary hospital sector, we interview a diverse range of value chain participants, including:
Hospital Network Executives (e.g., Chief Medical Officers, Operations Directors)
Pet Insurance Providers (Claims Managers, Underwriting Heads)
Our analyst team conducts structured interviews with 3–4 specific stakeholder job titles across the value chain: Chief Veterinary Officer, Hospital Administrator, Procurement Director, and Clinical Department Head.
Primary research is supplemented by on-site visits to veterinary hospitals and diagnostic laboratories across key markets.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Veterinary Officer
30%
Hospital Administrator
25%
Procurement Director
25%
Clinical Department Head
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Veterinary Hospital Networks
35%
Diagnostic Equipment & Device Suppliers
20%
Pharmaceutical & Vaccine Manufacturers
15%
Pet Insurance Providers
10%
Academic & Research Institutions
10%
Government & Regulatory Bodies
10%
Secondary Research & Industry Benchmarking
20–30% of our research is derived from secondary sources, including:
Official Government and Multilateral Data: UN Comtrade, World Bank, OECD, US ITC, Eurostat, and national statistical agencies (e.g., USDA, Eurostat) for trade flows and economic indicators.
Trade Association and Non-Profit Reports: AVMA, NAPHIA (North American Pet Health Insurance Association), and WSAVA for pet ownership, insurance penetration, and clinical standards.
Financial Databases: Bloomberg, Factiva, Hoovers, and PitchBook for corporate financials, M&A activity, and competitive intelligence.
We triangulate data from these sources to build a comprehensive picture of market size, segmentation, and competitive landscape.
Demand Modeling & Market Estimation
We employ a simultaneous top-down and bottom-up methodology to estimate market size and forecast growth.
Bottom-up calculation: We build market value from the ground up using specific quantitative metrics:
Patient Visit Volume: Dog and cat population data from official sources, multiplied by average annual visit frequency per pet.
Average Revenue Per Visit (ARPV): Derived from primary interviews and financial disclosures, segmented by service type and animal.
Service Mix and Pricing: Weighted average fees for medical, surgical, and consultation services, adjusted for regional pricing variations.
Insurance Penetration: Gross written premium data and claim frequency rates to model insured patient spend.
Top-down validation: We reconcile bottom-up estimates with regional revenue data reported by leading hospital networks and industry associations.
All estimates are validated through multi-level data triangulation, ensuring internal consistency and accuracy.
Data Accuracy & Quality Check
Our research process guarantees an estimated data accuracy level of 85–90%.
Every data point is cross-verified against at least two independent sources.
We conduct sanity checks on all forecast assumptions using historical growth trends and macroeconomic indicators.
Each report is updated to the date of purchase to ensure the latest available data and insights are incorporated.
Our analyst team performs a final quality review to ensure all data is presented clearly, accurately, and with appropriate context.