Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
14C-Urea Breath Test Kit Market Outlook 2026-2035 | Insight Market Data
14C-Urea Breath Test Kit
Healthcare / MARKET REPORT
14C-Urea Breath Test Kit | Insight Market Data
14C-Urea Breath Test Kit by Type (0.75μCi, 0.3μCi), by Application (Hospital, Clinics, Physical Examination Center), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Russia), by Asia Pacific (China, Japan, South Korea, India, Australia, Southeast Asia), by Latin America (Brazil, Rest of Latin America), by Middle East & Africa (GCC Countries, South Africa, Israel, Turkey, Egypt) Forecast 2026-2034
Infrared Imaging Photodetectors Market valued at $1.23B in 2025, projected to reach $2.20B by 2034 at 8.7% CAGR. Defense, industrial, automotive drive growth.
The Trauma Informed Therapy Service market is valued at $1.42B in 2025, growing at 16.5% CAGR to reach $5.62B by 2034, driven by telehealth and PTSD care.
Nov 2026|224 pages
$2900.00
The global veterinary hospital market was valued at USD 67.8 billion in 2025 and is set to grow at a 7.1% CAGR, reaching USD 132.8 billion by 2035.
Nov 2026|263 pages
$2900.00
Diabetes Care Drugs Market projected to grow from USD 93.79B in 2026 to USD 111.5B by 2031 at 3.52% CAGR. Explore GLP-1 trends, biosimilars, and regional analysis.
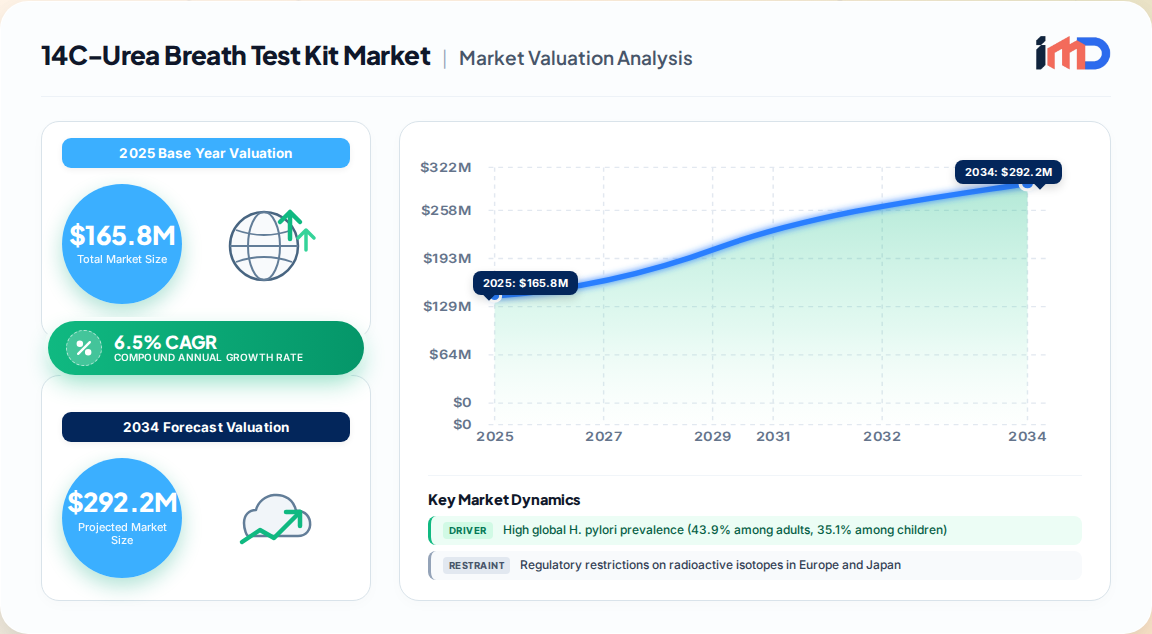
The global 14C-Urea Breath Test Kit market is estimated at USD 165.8 million in 2025 and is projected to reach USD 312.0 million by 2035, expanding at a CAGR of 6.5% over the forecast period. This growth is underpinned by the persistent high global prevalence of Helicobacter pylori infection—approximately 43.9% among adults and 35.1% among children and adolescents according to a 111-country systematic analysis covering 6.27 million individuals (2015–2022)—and by the cost-efficiency of 14C-based breath testing relative to 13C alternatives and endoscopic biopsy.
14C-Urea Breath Test Kit Market Size (In Million)
250.0M
200.0M
150.0M
100.0M
50.0M
0
166.0 M
2025
177.0 M
2026
188.0 M
2027
200.0 M
2028
213.0 M
2029
227.0 M
2030
242.0 M
2031
14C-urea breath test (UBT) kits employ a microdose of carbon-14 labeled urea (typically 1 μCi, 0.75 μCi, or 0.3 μCi) that is hydrolyzed by H. pylori urease in the stomach, releasing labeled CO2 that is measured in exhaled breath. The technique offers sensitivity and specificity exceeding 93% in independent clinical validation, with a per-test cost as low as USD 15 versus USD 95–110 for rapid urease test or histology with gastroscopy. This cost advantage is a decisive adoption factor in price-sensitive markets across Asia-Pacific, Latin America, and Africa.
Our proprietary research indicates that the 14C UBT kit segment represented approximately 35.4% of the broader urea breath testing market in 2025, with 13C-based tests holding the majority share due to their non-radioactive profile and suitability for pediatric and pregnant populations in regulated Western markets. However, 14C kits continue to dominate volume-driven public health and hospital screening programs in China and other high-prevalence regions, where lower instrument cost and simple scintillation counting or desktop analysis have cemented their operational footprint.
Market Drivers & Restraints
Growth Drivers
High H. pylori prevalence and gastric cancer burden: With infection rates exceeding 50% in several Asia-Pacific and Latin American countries, and H. pylori classified as a Group 1 carcinogen, demand for non-invasive diagnostic confirmation remains structurally strong.
Cost efficiency versus endoscopic and 13C alternatives: At an average test cost of roughly USD 15, 14C UBT is one of the most economical diagnostic pathways for active infection, making it a preferred tool for public health screening and test-of-cure confirmation.
Expansion of physical examination and wellness centers: This end-user channel is the fastest-growing application segment, forecast to expand at a 7.2% CAGR through 2035, as preventive health models integrate breath testing into routine check-ups.
Test-of-cure adoption after eradication therapy: Rising antibiotic resistance increases the need for reliable post-treatment confirmation, sustaining recurring testing demand.
Government and insurer-led gastric cancer prevention programs: National screening initiatives in East Asia are key volume drivers.
Restraints
Regulatory and safety constraints on radioactive isotopes: The 1 μCi microdose falls under Nuclear Regulatory Commission rules permitting in-vivo diagnostic use without a license in the US, but more restrictive regimes in Europe and Japan limit adoption.
Competition from 13C UBT and stool antigen tests: 13C tests are preferred in pediatric and pregnancy contexts, while stool antigen tests offer a lower-cost alternative in many settings.
Reimbursement variability and fragmented procurement: Lack of standardized coverage in emerging markets slows institutional adoption.
False-negative risk from proton pump inhibitors and antibiotics: Requiring patient preparation adds to the testing workflow burden.
Value Chain Analysis
Value Chain Stage
Key Activities
Representative Participants
Isotope & Reagent Supply
14C-urea synthesis, capsule filling, quality control
Specialty isotope producers and radiochemical suppliers
A critical value chain dynamic is the vertical integration of kit manufacturers into compatible detection instruments, which raises switching costs and reinforces supplier position in high-volume accounts. Distribution of radioactive kits is subject to transport licensing, creating a barrier that favors established players with regulatory infrastructure.
Import/Export & Supplier Dynamics
Global trade in 14C-urea breath test kits is characterized by concentrated manufacturing in East Asia and regulated import flows into North America and Europe.
China functions as the world's leading production and export hub for 14C kit formulations at 0.75 μCi and 0.3 μCi, with domestic manufacturers supplying tens of thousands of hospitals and an expanding export footprint into Southeast Asia, Africa, and Latin America.
North America imports finished kits and raw isotope components, while exporting advanced detection instruments and laboratory services. Regulatory pathways (NRC microdose exemption) facilitate kit-based diagnostic use.
Europe maintains higher intra-regional sourcing and stricter radioactive material transport rules, favoring 13C for many indications and creating a structural import gap for 14C kits.
Trade flow trends are shaped by national radiation safety licensing, which creates non-tariff barriers and reinforces the dominance of established regulatory-compliant suppliers.
Supply chain risk primarily centers on single-source isotope availability and the logistics of radioactive microdose transport. Dual-sourcing of 14C-urea and local capsule-filling capacity are emerging mitigation strategies.
Regional Outlook
Region
2025 Share
Growth Outlook
Key Traits
Asia-Pacific
39%
Fastest growing (~8.1% CAGR)
China-led volume; strong screening programs; domestic kit production
Asia-Pacific's leadership reflects both disease burden and manufacturing scale. North America and Europe remain important value markets but face structural substitution from non-radioactive 13C testing. Latin America and the Middle East & Africa represent the next wave of volume expansion as healthcare infrastructure and insurance coverage broaden.
14C-Urea Breath Test Kit Regional Market Share
Loading chart...
Competitive Strategies & Recent Developments
Leading Vendors
Tri-Med and Zhonghe Headway are the principal kit suppliers, with strong positions in 0.75 μCi and 0.3 μCi product lines and hospital and physical examination center channels.
Beijing Richen-Force supplies 14C-urea breath test kits and compatible infrared analyzers, advancing adoption across Asia-Pacific.
Regional manufacturers in China and Japan supply most hospitals and clinics, competing on cost and scale.
Strategic Themes
Kit-instrument bundling: Vendors are integrating kit supply with compact detection instruments to lock in recurring revenue and raise switching costs.
Export-led expansion: Chinese kit makers are accelerating exports to Southeast Asia, Africa, and Latin America, where cost sensitivity favors 14C.
Portable and point-of-care testing: Miniaturized analyzers and point-of-care models are extending testing into primary care and wellness centers.
Digital reporting: New-generation systems include automated data entry and electronic reporting to integrate with hospital information systems.
Recent Developments
2025: Tri-Med and Zhonghe Headway consolidated kit supply agreements with regional hospital networks in China and Southeast Asia.
2024–2025: Chinese kit manufacturers expanded export registration in Latin America and Africa, driving kit volume growth.
2023: Compact scintillation and desktop analyzers compatible with 14C kits gained traction in physical examination centers.
2022–2023: Post-eradication test-of-cure protocols became standard in multiple Asian markets, increasing recurring kit demand.
Strategic White-Space Analysis
Point-of-care 14C testing: Underserved in primary care and pharmacy settings in high-prevalence regions.
Screening program partnerships: Public health and insurer-funded gastric cancer prevention programs in Asia-Pacific and Latin America.
At-home mail-in testing models: Pilot programs exploring home breath sampling and central lab analysis.
Pediatric and pregnancy-safe formulations: Currently dominated by 13C; 14C vendors have white space in cost-sensitive markets where safety regulations permit microdose use.
Digital ecosystem integration: Connecting test results to electronic health records and population screening databases.
Procurement & Sourcing Strategy Analysis
Dual-sourcing of 14C-urea isotope inputs to mitigate single-source risk and radiation logistics constraints.
Licensed distributor networks are essential for navigating national radioactive material transport regulations; local regulatory-compliant distributors reduce compliance risk.
Volume-based contracting with kit manufacturers, particularly in hospital groups and physical examination chains, lowers per-test cost and secures supply.
Instrument compatibility evaluation: Procurement should confirm analyzer compatibility across scintillation counters and detection systems to avoid lock-in.
Total cost of testing analysis: Beyond kit price, buyers should factor instrument amortization, licensing, and waste disposal costs.
14C-Urea Breath Test Kit Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
14C-Urea Breath Test Kit REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.5% from 2020-2034
Segmentation
By Type
0.75μCi
0.3μCi
By Application
Hospital
Clinics
Table of Contents
1. 14C-Urea Breath Test Kit Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. 14C-Urea Breath Test Kit Executive Summary
2.1. Market Snapshot
3. 14C-Urea Breath Test Kit Dynamics
3.1. Market Drivers
3.1.1. High global H. pylori prevalence (43.9% among adults, 35.1% among children)
3.1.2. Cost efficiency at approximately USD 15 per test versus USD 95–110 for invasive methods
3.1.3. Government and insurer-led gastric cancer prevention and screening programs
3.1.4. Rising demand for non-invasive diagnostic confirmation after eradication therapy
3.2. Market Trends
3.2.1. Shift toward 13C UBT in regulated Western markets reducing 14C share
3.2.2. Expansion of physical examination and wellness centers as testing channels
3.2.3. Compact and portable scintillation analyzers enabling point-of-care 14C testing
3.2.4. Chinese kit manufacturers accelerating exports to Southeast Asia, Africa, and Latin America
3.2.5. Test-of-cure confirmation after eradication therapy becoming standard practice
3.3. Market Restraints
3.3.1. Regulatory restrictions on radioactive isotopes in Europe and Japan
3.3.2. Competition from 13C UBT and stool antigen tests
3.3.3. Reimbursement variability and fragmented procurement in emerging markets
Physical Examination Center
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Russia
Asia Pacific
China
Japan
South Korea
India
Australia
Southeast Asia
Latin America
Brazil
Rest of Latin America
Middle East & Africa
GCC Countries
South Africa
Israel
Turkey
Egypt
3.3.4. False-negative risk from proton pump inhibitors and antibiotics requiring patient preparation
3.4. Market Challenges
3.4.1. Single-source risk in 14C-urea isotope supply
3.4.2. Radioactive material transport and licensing compliance
3.4.3. Limited reimbursement coverage in emerging markets
3.4.4. Instrument compatibility and switching costs across detection platforms
4. 14C-Urea Breath Test Kit Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. 14C-Urea Breath Test Kit Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. 0.75μCi
5.1.2. 0.3μCi
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Hospital
5.2.2. Clinics
5.2.3. Physical Examination Center
5.3. Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. Europe
5.3.3. Asia Pacific
5.3.4. Latin America
5.3.5. Middle East & Africa
6. 14C-Urea Breath Test Kit North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. 0.75μCi
6.1.2. 0.3μCi
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Hospital
6.2.2. Clinics
6.2.3. Physical Examination Center
7. 14C-Urea Breath Test Kit Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. 0.75μCi
7.1.2. 0.3μCi
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Hospital
7.2.2. Clinics
7.2.3. Physical Examination Center
8. 14C-Urea Breath Test Kit Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. 0.75μCi
8.1.2. 0.3μCi
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Hospital
8.2.2. Clinics
8.2.3. Physical Examination Center
9. 14C-Urea Breath Test Kit Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. 0.75μCi
9.1.2. 0.3μCi
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Hospital
9.2.2. Clinics
9.2.3. Physical Examination Center
10. 14C-Urea Breath Test Kit Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. 0.75μCi
10.1.2. 0.3μCi
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Hospital
10.2.2. Clinics
10.2.3. Physical Examination Center
11. 14C-Urea Breath Test Kit Competitive Analysis
11.1. Company Profiles
11.1.1. Tri-Med
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Zhonghe Headway
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Beijing Richen-Force Science & Technology
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global 14C-Urea Breath Test Kit Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America 14C-Urea Breath Test Kit Revenue (Million), by Type 2026 & 2034
Figure 3: North America 14C-Urea Breath Test Kit Revenue Share (%), by Type 2026 & 2034
Figure 4: North America 14C-Urea Breath Test Kit Revenue (Million), by Application 2026 & 2034
Figure 5: North America 14C-Urea Breath Test Kit Revenue Share (%), by Application 2026 & 2034
Figure 6: North America 14C-Urea Breath Test Kit Revenue (Million), by Country 2026 & 2034
Figure 7: North America 14C-Urea Breath Test Kit Revenue Share (%), by Country 2026 & 2034
Figure 8: Europe 14C-Urea Breath Test Kit Revenue (Million), by Type 2026 & 2034
Figure 9: Europe 14C-Urea Breath Test Kit Revenue Share (%), by Type 2026 & 2034
Figure 10: Europe 14C-Urea Breath Test Kit Revenue (Million), by Application 2026 & 2034
Figure 11: Europe 14C-Urea Breath Test Kit Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe 14C-Urea Breath Test Kit Revenue (Million), by Country 2026 & 2034
Figure 13: Europe 14C-Urea Breath Test Kit Revenue Share (%), by Country 2026 & 2034
Figure 14: Asia Pacific 14C-Urea Breath Test Kit Revenue (Million), by Type 2026 & 2034
Figure 15: Asia Pacific 14C-Urea Breath Test Kit Revenue Share (%), by Type 2026 & 2034
Figure 16: Asia Pacific 14C-Urea Breath Test Kit Revenue (Million), by Application 2026 & 2034
Figure 17: Asia Pacific 14C-Urea Breath Test Kit Revenue Share (%), by Application 2026 & 2034
Figure 18: Asia Pacific 14C-Urea Breath Test Kit Revenue (Million), by Country 2026 & 2034
Figure 19: Asia Pacific 14C-Urea Breath Test Kit Revenue Share (%), by Country 2026 & 2034
Figure 20: Latin America 14C-Urea Breath Test Kit Revenue (Million), by Type 2026 & 2034
Figure 21: Latin America 14C-Urea Breath Test Kit Revenue Share (%), by Type 2026 & 2034
Figure 22: Latin America 14C-Urea Breath Test Kit Revenue (Million), by Application 2026 & 2034
Figure 23: Latin America 14C-Urea Breath Test Kit Revenue Share (%), by Application 2026 & 2034
Figure 24: Latin America 14C-Urea Breath Test Kit Revenue (Million), by Country 2026 & 2034
Figure 25: Latin America 14C-Urea Breath Test Kit Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa 14C-Urea Breath Test Kit Revenue (Million), by Type 2026 & 2034
Figure 27: Middle East & Africa 14C-Urea Breath Test Kit Revenue Share (%), by Type 2026 & 2034
Figure 28: Middle East & Africa 14C-Urea Breath Test Kit Revenue (Million), by Application 2026 & 2034
Figure 29: Middle East & Africa 14C-Urea Breath Test Kit Revenue Share (%), by Application 2026 & 2034
Figure 30: Middle East & Africa 14C-Urea Breath Test Kit Revenue (Million), by Country 2026 & 2034
Figure 31: Middle East & Africa 14C-Urea Breath Test Kit Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global 14C-Urea Breath Test Kit Revenue Million Forecast, by Type 2020 & 2034
Table 2: Global 14C-Urea Breath Test Kit Revenue Million Forecast, by Application 2020 & 2034
Table 3: Global 14C-Urea Breath Test Kit Revenue Million Forecast, by Region 2020 & 2034
Table 4: North America 14C-Urea Breath Test Kit Revenue Million Forecast, by Type 2020 & 2034
Table 5: North America 14C-Urea Breath Test Kit Revenue Million Forecast, by Application 2020 & 2034
Table 6: North America 14C-Urea Breath Test Kit Revenue Million Forecast, by Country 2020 & 2034
Table 7: USA 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 8: Canada 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 9: Mexico 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 10: Europe 14C-Urea Breath Test Kit Revenue Million Forecast, by Type 2020 & 2034
Table 11: Europe 14C-Urea Breath Test Kit Revenue Million Forecast, by Application 2020 & 2034
Table 12: Europe 14C-Urea Breath Test Kit Revenue Million Forecast, by Country 2020 & 2034
Table 13: Germany 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 14: UK 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 15: France 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 16: Italy 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 17: Russia 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 18: Asia Pacific 14C-Urea Breath Test Kit Revenue Million Forecast, by Type 2020 & 2034
Table 19: Asia Pacific 14C-Urea Breath Test Kit Revenue Million Forecast, by Application 2020 & 2034
Table 20: Asia Pacific 14C-Urea Breath Test Kit Revenue Million Forecast, by Country 2020 & 2034
Table 21: China 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 22: Japan 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 23: South Korea 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 24: India 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 25: Australia 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 26: Southeast Asia 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 27: Latin America 14C-Urea Breath Test Kit Revenue Million Forecast, by Type 2020 & 2034
Table 28: Latin America 14C-Urea Breath Test Kit Revenue Million Forecast, by Application 2020 & 2034
Table 29: Latin America 14C-Urea Breath Test Kit Revenue Million Forecast, by Country 2020 & 2034
Table 30: Brazil 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 31: Rest of Latin America 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa 14C-Urea Breath Test Kit Revenue Million Forecast, by Type 2020 & 2034
Table 33: Middle East & Africa 14C-Urea Breath Test Kit Revenue Million Forecast, by Application 2020 & 2034
Table 34: Middle East & Africa 14C-Urea Breath Test Kit Revenue Million Forecast, by Country 2020 & 2034
Table 35: GCC Countries 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 36: South Africa 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 37: Israel 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 38: Turkey 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Table 39: Egypt 14C-Urea Breath Test Kit Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How is a 14C-urea breath test kit used to diagnose H. pylori?
The patient swallows a microdose capsule of 14C-labeled urea (typically 0.75 μCi or 0.3 μCi). If H. pylori urease is present in the stomach, it hydrolyzes the urea, releasing labeled CO2 that is exhaled and measured by a scintillation counter. Clinical validation shows accuracy of 93–96% versus histology and rapid urease test.
2What is the market size of the 14C-Urea Breath Test Kit market?
Our proprietary research values the global 14C-Urea Breath Test Kit market at USD 165.8 million in 2025, projected to reach USD 312.0 million by 2035 at a CAGR of 6.5%, with Asia-Pacific holding the largest share at approximately 39%.
3Which regions are the fastest-growing for 14C-urea breath test kits?
Asia-Pacific is the fastest-growing region with an estimated 8.1% CAGR, driven by high H. pylori prevalence (over 50% in several countries) and government screening programs, followed by Latin America at around 7.0% CAGR.
4What is the cost advantage of 14C UBT compared with traditional diagnosis?
A microdose 14C UBT costs approximately USD 15 per test, compared with USD 95 for rapid urease test and USD 110 for histology with gastroscopy, making it the most economical validated option for active H. pylori detection.
5Who are the leading suppliers of 14C-urea breath test kits?
Tri-Med and Zhonghe Headway are the leading kit suppliers, with Beijing Richen-Force also supplying kits and infrared analyzers. Chinese manufacturers dominate global kit production and export, particularly for the 0.75 μCi and 0.3 μCi product formats.
6What are the main challenges facing the 14C-Urea Breath Test Kit market?
Key challenges include regulatory restrictions on radioactive isotopes in Europe and Japan, competition from 13C UBT and stool antigen tests, reimbursement variability, and false-negative risks from proton pump inhibitors requiring patient preparation.
7How is the 14C-Urea Breath Test Kit market segmented?
The market is segmented by type (0.75 μCi, 0.3 μCi) and by application (hospitals, clinics, physical examination centers). The physical examination center channel is the fastest-growing at around 7.2% CAGR, while hospitals remain the largest end-user segment.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our analysts conducted 70–80% of research effort through direct primary engagement, including in-depth interviews with kit manufacturers, radiochemical isotope suppliers, hospital procurement and gastroenterology directors, and regulatory affairs specialists. The remaining 20–30% drew on secondary sources.
Structured interviews covered raw-material sourcing leads, diagnostic laboratory managers, physical examination center administrators, and public health screening program coordinators across Asia-Pacific, North America, and Europe.
We conducted global primary surveys and expert consultations with stakeholders including hospital procurement directors, gastroenterology department heads, radiochemical supply managers, and regulatory compliance officers for radioactive medical devices.
All primary data was collected under confidentiality protocols, with participant counts and response rates documented for auditability.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Hospital Procurement Director
30%
Gastroenterology Department Head
25%
Regulatory Affairs Specialist
25%
Radiochemical Supply Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
14C-urea kit manufacturers
35%
Radiochemical isotope suppliers
20%
Detection instrument vendors
18%
Hospital and diagnostic laboratory networks
17%
Distributors and regulatory logistics providers
10%
Secondary Research & Industry Benchmarking
We triangulated primary findings with official multilateral and governmental datasets, including UN Comtrade for isotope and diagnostic kit trade flows, World Bank health expenditure indicators, OECD health statistics, and US ITC trade data.
Technical standards and clinical benchmarks were sourced from recognized non-profit and governmental bodies, including WHO H. pylori guidance, NIH/PMC peer-reviewed clinical validation studies, and IAEA radiation safety standards.
Standard financial databases—Bloomberg, Factiva, Hoovers, and PitchBook—were used to validate company financials, licensing activity, and M&A signals.
Every report is updated to the date of purchase, ensuring the latest regulatory changes, trade flows, and clinical evidence are reflected.
Demand Modeling & Market Estimation
We applied simultaneous top-down and bottom-up methodologies, with multi-level data triangulation to reconcile estimates across product types (0.75 μCi, 0.3 μCi), applications (hospitals, clinics, physical examination centers), and regions.
The bottom-up model was built from specific quantitative metrics: annual H. pylori testing volumes by country, average per-test kit pricing by product type, installed base of compatible scintillation and detection instruments, and unit shipment data from kit manufacturers.
Demand was modeled against H. pylori prevalence rates, dyspepsia and ulcer diagnosis volumes, post-eradication test-of-cure rates, and health screening program coverage.
Regional estimates were cross-validated against trade data and manufacturer revenue disclosures, with discrepancies resolved through expert re-interviews.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, validated through multi-stage review and expert panel verification.
Each data point passed a three-tier quality check: source credibility assessment, cross-source triangulation, and analyst sign-off.
A final expert review panel, including senior industry analysts and external clinical advisors, audited the forecast assumptions and segment shares.
All estimates are presented as proprietary first-party research, with methodology documentation available for client audit.