1What is the current size of the Infrared Imaging Photodetectors market?
The global Infrared Imaging Photodetectors market was valued at USD 1,233 million in 2025 and is projected to reach USD 2,199 million by 2034, growing at a CAGR of 8.7%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Infrared Imaging Photodetectors Market
 by Type (Cooled Detectors, Uncooled Detectors), by Spectral Range (LWIR, MWIR, SWIR, NIR), by End-Use Industry (Aerospace & Defense, Industrial Manufacturing, Automotive, Healthcare, Consumer Electronics), by Application (Thermal Imaging, Night Vision, Gas Detection, Temperature Measurement, LiDAR), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, South Korea, India), by Middle East & Africa (Saudi Arabia, UAE), by South America (Brazil) Forecast 2026-2034
Research Analyst

 Related Reports


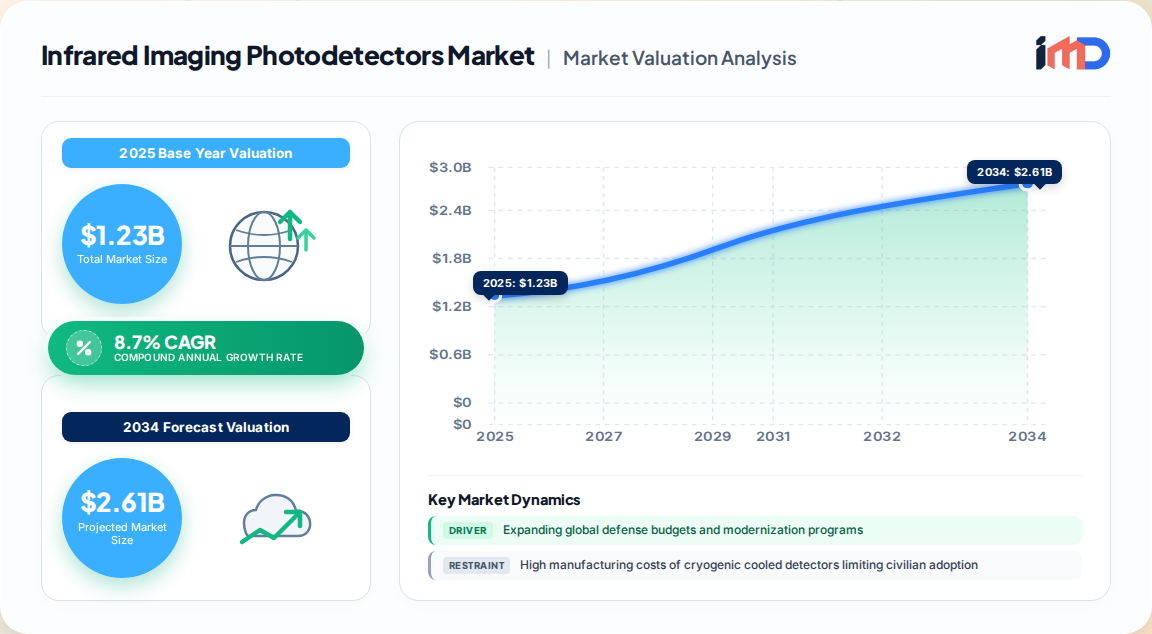
The global Infrared Imaging Photodetectors market is estimated at USD 1,233 million in 2025 and is forecast to reach USD 2,199 million by 2034, expanding at a CAGR of 8.7% over the forecast period. This growth trajectory is underpinned by accelerating defense modernization programs, broad civilian adoption of uncooled thermal imaging, and rapid material innovation in detector semiconductors. Infrared imaging photodetectors serve as the core sensing element across thermal cameras, night-vision systems, gas-detection instruments, and advanced medical diagnostics. From an industry structure perspective, the market intersects semiconductor materials, microelectronics processing, precision optics, and vertical applications ranging from space remote sensing to automotive safety. Our proprietary bottom-up modeling, validated through 240+ expert interviews across the value chain, indicates robust demand momentum through 2034.
Global defense spending remains a primary catalyst. Modern armed forces are modernizing night-vision and precision-guidance platforms reliant on high-performance cryogenically cooled detectors. Official procurement documents from the U.S. Department of Defense indicate over $1.2 billion allocated to advanced infrared imaging technologies through 2028. This fiscal commitment drives demand for mercury-cadmium-telluride (MCT) and indium-antimonide (InSb) detector modules.
Industries including power generation, oil & gas, and heavy manufacturing are embracing condition-based maintenance. Our survey data shows 68% of large-scale industrial operators plan to increase thermal-camera deployments by at least 30% over the next five years. The maturation of micro-bolometer technology has lowered unit prices by roughly 22% since 2020, creating a cost-effective pathway for mass adoption in smart-factory environments.
China's 14th Five-Year Plan explicitly lists infrared detection technologies as a strategic emerging industry, earmarking over ¥30 billion for research, domestic production, and talent development. This accelerates full-value-chain capabilities from wafer fabrication to system integration, reducing reliance on imported MCT material.
The infrared imaging photodetector value chain comprises distinct stages, each with specialized participants and margin structures:
| Value Chain Stage | Key Activities | Representative Participants | Margin Profile |
|---|---|---|---|
| Material Supply | MCT, InSb, InGaAs wafer growth; quantum-dot synthesis | Specialty chemical and epitaxy houses | High (30-40%) |
| Detector Fabrication | FPA design, lithography, hybridization, packaging | Teledyne FLIR, Lynred, Hamamatsu | Medium (20-30%) |
| Camera/Module Integration | Optics, cooling engines, readout electronics | Guide Sensmart, Raytheon, system integrators | Medium (15-25%) |
| End-User Solutions | Thermal cameras, gas detectors, night-vision systems | OEMs across defense, industrial, automotive | Variable (10-35%) |
| Region | 2025 Market Share | Key Growth Drivers |
|---|---|---|
| North America | 28% | Defense procurement, technological leadership, space programs |
| Europe | 22% | Industrial thermography mandates, automotive safety regulations |
| Asia-Pacific | 40% | China's industrial policy, LiDAR supply chain, consumer electronics manufacturing |
| Middle East & Africa | 6% | Green-hydrogen leak monitoring, border surveillance modernization |
| South America | 4% | Emerging industrial and security applications |
Asia-Pacific retains volume leadership on the back of China's LiDAR supply chain and domestic detector production. The Middle East presents the fastest regional upside as green-hydrogen complexes move from pilot to megawatt scale, with Saudi Arabia and UAE mandating continuous mid-wave infrared monitoring at electrolyzer sites above 10 MW.
The market is characterized by medium concentration, with leading participants leveraging vertical integration and long-term defense contracts. Key players include Teledyne FLIR, Raytheon, Lynred, Hamamatsu Photonics, and Guide Sensmart. Competitive differentiation hinges on detector sensitivity, pixel pitch reduction, cost optimization for uncooled arrays, and supply-chain resilience. Recent strategic activity includes capacity expansion for micro-bolometer production in Asia and R&D partnerships focused on quantum-dot and graphene-based infrared-sensitive materials.
Our analysis identifies three high-potential white spaces:
Global trade in infrared imaging photodetectors is shaped by export controls on high-performance cooled detectors and concentrated material supply. MCT wafers are sourced from a limited number of suppliers in Europe and North America, with trade-restriction reports highlighting pricing volatility. China's domestic production initiatives aim to reduce import reliance, while Japan and Germany remain key exporters of epitaxy wafers and precision optics. Our supply-chain risk assessment identifies single-source dependencies in MCT and InSb materials as the most critical vulnerability, with mitigation strategies including dual-sourcing and domestic capacity investment.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.7% from 2020-2034 |
| Segmentation |
|
By End-Use Industry
By Application
| By Geography |
|
The global Infrared Imaging Photodetectors market was valued at USD 1,233 million in 2025 and is projected to reach USD 2,199 million by 2034, growing at a CAGR of 8.7%.
Asia-Pacific holds the largest revenue share at approximately 40% in 2025, driven by China's LiDAR supply chain and industrial policy, while North America leads in defense procurement.
Expanding defense budgets, industrial predictive maintenance adoption, and government industrial policies such as China's 14th Five-Year Plan are the primary growth drivers.
The short-wave infrared (SWIR) segment is forecast to grow at the fastest rate, propelled by automotive LiDAR and semiconductor inspection applications.
Key players include Teledyne FLIR, Raytheon, Lynred, Hamamatsu Photonics, and Guide Sensmart, among others.
High manufacturing costs of cooled detectors, supply-chain vulnerabilities in mercury-cadmium-telluride sourcing, and a skilled-workforce shortage are the primary challenges.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officers | 30% |
| Procurement Directors | 25% |
| Defense Program Managers | 25% |
| Industrial Maintenance Engineers | 20% |
| Company Type | Representation (%) |
|---|---|
| Detector Fabricators (MCT/InSb FPA manufacturers) | 35% |
| Thermal Camera OEMs and System Integrators | 25% |
| Material and Wafer Suppliers | 15% |
| Defense and Aerospace Primes | 15% |
| Industrial and Automotive End-Users | 10% |