Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Diabetes Care Drugs Market
Healthcare / MARKET REPORT
Diabetes Care Drugs Market | Insight Market Data
Diabetes Care Drugs Market by Drug Class (Oral Anti-Diabetic Drugs [Biguanides, Alpha-Glucosidase Inhibitors, DPP-4 Inhibitors, Meglitinides, SGLT-2 Inhibitors, Sulphonylureas, Thiazolidinediones], Insulin [Short-Acting, Intermediate-Acting, Long-Acting, Premixed, Rapid-Acting], Non-Insulin Injectable Drugs [GLP-1 Agonists, Dual Incretin Co-Agonists], Combination Drugs), by Route of Administration (Oral, Subcutaneous, Intravenous), by Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of EU), by Asia Pacific (China, Japan, India, South Korea, Rest of APAC), by Latin America (Brazil, Argentina, Colombia, Rest of LA), by Middle East & Africa (GCC, South Africa, Rest of MEA) Forecast 2026-2034
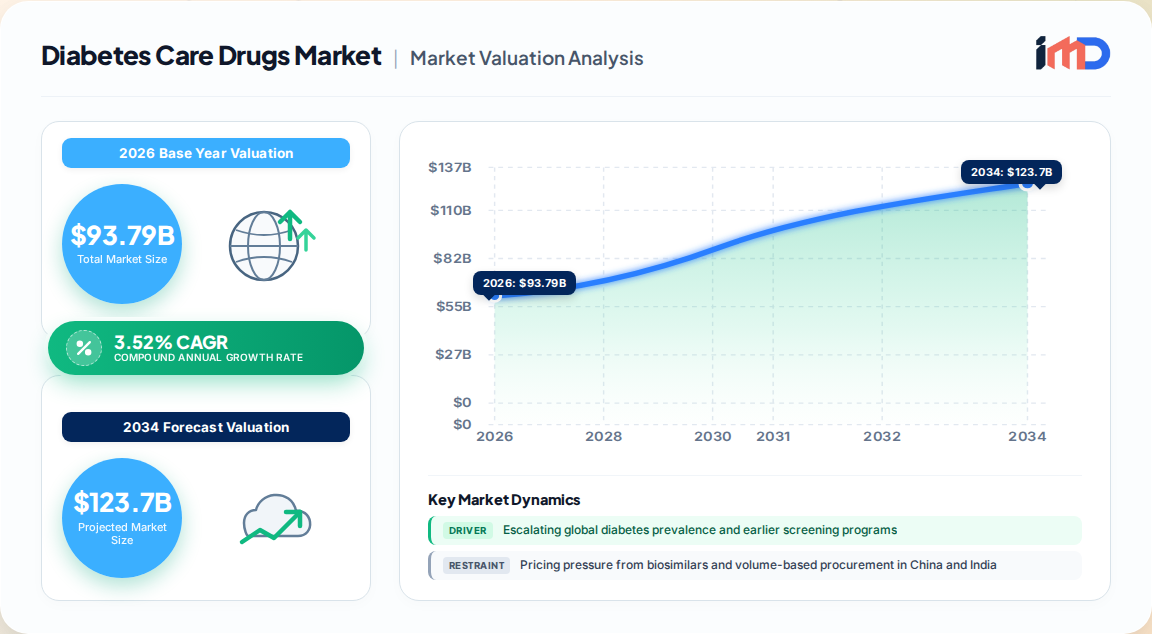
The global Diabetes Care Drugs Market is a $90+ billion therapeutic franchise undergoing a structural transformation. Our proprietary first-party research estimates the market at USD 93.79 billion in 2026, projected to reach USD 111.5 billion by 2031 at a 3.52% CAGR. This growth occurs against a backdrop of 588.7 million adults living with diabetes in 2024, with the total expected to hit 852.5 million by 2050, and nearly 43% of cases remaining undiagnosed. The market is shifting from a historical reliance on basal insulin toward incretin-based therapies (GLP-1 receptor agonists and dual co-agonists), which are rapidly capturing value share and reshaping treatment paradigms.
Diabetes Care Drugs Market Market Size (In Billion)
150.0B
100.0B
50.0B
0
90.60 B
2025
93.79 B
2026
97.09 B
2027
100.5 B
2028
104.0 B
2029
107.7 B
2030
111.5 B
2031
Key structural developments include:
Non-insulin injectables are forecast to grow at a 4.25% CAGR through 2031, outpacing overall market growth.
Oral antidiabetics are advancing at a 4.85% CAGR, driven by SGLT-2 inhibitors and emerging oral GLP-1 candidates.
Online pharmacies represent the fastest-growing distribution channel, rising at 5.87% CAGR, eroding hospital pharmacy dominance (38.63% revenue share in 2025).
North America commanded 42.13% of global market share in 2025, while Asia-Pacific is the fastest-growing region at a 5.51% CAGR to 2031.
This report synthesizes demand-side epidemiology, supply-side capacity investments, regulatory shifts, and competitive dynamics to deliver actionable intelligence for stakeholders across the diabetes care continuum.
Market Drivers & Restraints
Drivers Impact Analysis
Driver
Impact on CAGR (%)
Geographic Relevance
Impact Timeline
Escalating global diabetes prevalence & earlier screening
+1.2
Global, accelerating in Asia-Pacific, Middle East & Africa, Latin America
Medium term (2-4 years)
Rising healthcare expenditures in emerging markets
+0.8
Asia-Pacific core, spillover to MEA & LatAm
Long term (≥4 years)
Strong clinical evidence & guideline endorsements for GLP-1 & SGLT-2
+1.5
North America & Europe lead, expanding to APAC urban centers
Short term (≤2 years)
Growing adoption of biosimilar basal insulins
+0.6
Europe, India, China; emerging penetration in LatAm & SEA
North America & Europe initial adoption, followed by APAC high-income markets
Medium term (2-4 years)
Payor-integrated digital therapeutic bundling
+0.3
North America dominance, pilot programs in Europe & APAC urban markets
Long term (≥4 years)
Key driver insights: Mass screening programs in China, India, and Gulf states are unlocking latent demand. The International Diabetes Federation logged 588.7 million adults with diabetes in 2024, up 45% from 2021, yet 251.7 million remain undiagnosed. Africa shows the highest undiagnosed rate at 72.6%, while Asia-Pacific hosts 60% of total cases. China’s 2023 National Reimbursement Drug List update added semaglutide, dulaglutide, empagliflozin, and dapagliflozin, lifting GLP-1 prescriptions by 68% year-over-year in top-tier cities. India earmarked USD 1.2 billion for 2024-2026 to fund district-level diabetes clinics and biosimilar insulin procurement, cutting patient out-of-pocket spending by 40% in pilot states.
Restraints Impact Analysis
Restraint
Impact on CAGR (%)
Geographic Relevance
Impact Timeline
Pricing pressure from biosimilars & volume-based procurement
Key restraint insights: Biosimilar entrants compress pricing across Europe and large emerging economies. Brazil’s public health system awarded glargine biosimilar contracts at 55% discounts to originators, a model Argentina and Colombia now replicate. Legislative headwinds, such as U.S. Inflation Reduction Act price negotiations and China’s volume-based procurement, will tighten margins through 2031. However, Novo Nordisk, Eli Lilly, and Sanofi are investing more than USD 15 billion in new capacity to relieve the multiyear GLP-1 shortage, which should ease supply-side constraints by 2027.
Segment Analysis
By Drug Class
Insulin held 56.56% of the diabetes drugs market share in 2025, but is losing relative share to non-insulin injectables.
Non-insulin injectables (primarily GLP-1 receptor agonists and dual co-agonists) are forecast to grow at a 4.25% CAGR through 2031, driven by semaglutide, tirzepatide, and next-generation combination therapies.
Oral antidiabetics are advancing at a 4.85% CAGR, with SGLT-2 inhibitors (empagliflozin, dapagliflozin) and DPP-4 inhibitors contributing significantly.
Combination drugs are gaining traction as fixed-dose combinations improve adherence and glycemic control.
By Route of Administration
Subcutaneous formats captured 71.53% of the diabetes drugs market size in 2025, reflecting the dominance of injectable insulin and GLP-1 therapies.
Oral antidiabetics are advancing at a 4.85% CAGR to 2031, supported by patient preference for non-invasive options.
Intravenous administration remains niche, primarily for hospitalized patients.
By Distribution Channel
Hospital pharmacies accounted for 38.63% of revenue in 2025, yet online pharmacies represent the fastest expansion, rising at a 5.87% CAGR through 2031.
Transparent cash-pay models in North America now price rapid-acting insulin at USD 27.50 per vial compared with more than USD 300 at traditional outlets, accelerating the shift to digital channels.
Regional Outlook
Diabetes Care Drugs Market Regional Market Share
Loading chart...
North America
North America commanded 42.13% of the global diabetes drugs market share in 2025, supported by high diagnosis rates, advanced healthcare infrastructure, and rapid adoption of GLP-1 therapies. The U.S. accounts for the majority of regional revenue, with 23 million adults diagnosed with diabetes. However, pricing pressure from the Inflation Reduction Act and biosimilar competition will moderate growth.
Asia-Pacific
Asia-Pacific is projected to expand at a 5.51% CAGR to 2031, the fastest-growing region. The region hosts 60% of global diabetes cases, with China and India driving demand through expanded reimbursement and screening programs. Japan and South Korea weave HbA1c checks into employer health exams, pulling treatment initiation forward by roughly three years. Local manufacturing and biosimilar production are scaling rapidly, particularly in India and China.
Europe
Europe represents a mature market with moderate growth, characterized by aggressive biosimilar penetration and health technology assessment (HTA) driven pricing. The region is a key battleground for insulin biosimilars, with Germany, France, and the UK leading adoption. EU-5 countries are expected to see steady volume growth offset by price erosion.
EMEA and South America
The Middle East & Africa and South America regions offer significant upside potential, driven by rising healthcare expenditures and government initiatives. Gulf Cooperation Council governments subsidize HbA1c testing and SGLT-2 reimbursement, a blueprint Indonesia and Pakistan now emulate. Brazil’s public health system is expanding access to diabetes medications through discounted biosimilar contracts.
Competitive Landscape
The diabetes care drugs market is concentrated among a handful of global players, with medium market concentration. Key competitors include Novo Nordisk, Sanofi, AstraZeneca, Boehringer Ingelheim, and Eli Lilly and Company. These companies are investing heavily in GLP-1 capacity expansion, next-generation incretins, and digital health integration.
Recent strategic developments:
February 2025: FDA approved Merilog (insulin-aspart-szjj), the first rapid-acting insulin biosimilar to NovoLog, improving patient access and increasing competition.
March 2024: FDA broadened Ozempic’s label to chronic kidney disease after the FLOW trial cut kidney-failure risk 24%; Wegovy gained cardiovascular risk-reduction approval on SELECT trial data.
2024: Jardiance used EMPA-KIDNEY results to secure 35% of U.S. nephrology prescriptions for diabetic kidney disease.
2026: Vertex Pharmaceuticals halted development of VX-264, a cell therapy for type 1 diabetes, due to inadequate insulin production in Phase I/II trials.
October 2026: Victory Square Technologies announced its portfolio company INSU Therapeutics received a Notice of Allowance from the USPTO for a needle-free drug delivery platform for insulin and GLP-1 receptor agonists.
Value Chain Analysis
The diabetes care drugs value chain spans raw material suppliers, active pharmaceutical ingredient (API) manufacturers, drug formulators, contract manufacturing organizations (CMOs), and distribution channels. Key dynamics include:
API sourcing: High concentration of API production in China and India, creating supply chain risk.
Manufacturing: Novo Nordisk, Eli Lilly, and Sanofi are investing >USD 15 billion in new capacity to relieve GLP-1 shortages.
Distribution: Hospital pharmacies dominate but online pharmacies are growing at 5.87% CAGR.
Payors: Reimbursement decisions increasingly tie to cardiovascular and renal outcomes data.
Strategic White-Space Analysis
Significant white-space opportunities exist in:
Oral GLP-1 receptor agonists: Late-stage candidates could disrupt the injectable-dominated incretin market.
Fixed-dose combinations of GLP-1 and SGLT-2 inhibitors for enhanced glycemic and cardiorenal protection.
Biosimilar insulins in emerging markets: India, China, and Brazil offer high-volume, price-sensitive opportunities.
Digital therapeutics integration: Payor-integrated bundling in North America and Europe.
Needle-free delivery platforms for insulin and GLP-1 therapies, improving adherence.
Import/Export & Supplier Dynamics
Global trade in diabetes drugs is dominated by intra-firm transfers and API flows. Key patterns include:
API exports: China and India are the largest exporters of APIs for metformin, insulin, and GLP-1 precursors.
Finished drug trade: Europe and North America are net exporters of high-value biologics, while emerging markets import finished products.
Biosimilar trade: India and South Korea are emerging as biosimilar insulin exporters, targeting markets in Latin America, Africa, and Southeast Asia.
Supply chain risk: Geopolitical tensions and trade restrictions could disrupt API flows, prompting reshoring initiatives in the U.S. and EU.
Market Outlook & Forecast
The diabetes care drugs market is poised for steady growth, with a 3.52% CAGR from 2026 to 2031. The value shift from insulin to incretins will accelerate, driven by guideline endorsements and outcomes data. By 2031, non-insulin injectables are expected to capture a larger share of the market, while biosimilars will expand access in price-sensitive regions. Asia-Pacific will remain the growth engine, contributing over 40% of incremental spending. Strategic priorities for stakeholders include:
Investing in GLP-1 manufacturing capacity.
Developing oral incretins and combination therapies.
Expanding digital distribution channels.
Navigating pricing and reimbursement reforms.
Our proprietary forecasting framework, validated through primary interviews with industry experts and triangulated with official trade and epidemiological data, projects the market to reach USD 111.5 billion by 2031.
Diabetes Care Drugs Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Diabetes Care Drugs Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.52% from 2020-2034
Segmentation
By Drug Class
Oral Anti-Diabetic Drugs [Biguanides
Alpha-Glucosidase Inhibitors
DPP-4 Inhibitors
Meglitinides
SGLT-2 Inhibitors
Table of Contents
1. Diabetes Care Drugs Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Diabetes Care Drugs Market Executive Summary
2.1. Market Snapshot
3. Diabetes Care Drugs Market Dynamics
3.1. Market Drivers
3.1.1. Escalating global diabetes prevalence and earlier screening programs
3.1.2. Rising healthcare expenditures in emerging markets
3.1.3. Strong clinical evidence and guideline endorsements for GLP-1 and SGLT-2 classes
3.1.4. Growing adoption of biosimilar basal insulins
10.2. Analysis, Insights and Forecast - by Route of Administration
10.2.1. Oral
10.2.2. Subcutaneous
10.2.3. Intravenous
10.3. Analysis, Insights and Forecast - by Distribution Channel
10.3.1. Hospital Pharmacies
10.3.2. Retail Pharmacies
10.3.3. Online Pharmacies
10.3.4. Others
11. Diabetes Care Drugs Market Competitive Analysis
11.1. Company Profiles
11.1.1. Novo Nordisk
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Sanofi
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. AstraZeneca
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Boehringer Ingelheim
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Eli Lilly and Company
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Merck & Co.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Pfizer
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Johnson & Johnson
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Novartis
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Takeda Pharmaceutical
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Abbott Laboratories
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Bayer HealthCare
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. GlaxoSmithKline
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Lupin Limited
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Enthera
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Nano Precision Medical
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Oramed
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Dompe Farmaceutici
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Carmot Therapeutics
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Scohia Pharma
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Genexine
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. REMD Biotherapeutics
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Diabetes Care Drugs Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Diabetes Care Drugs Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 3: North America Diabetes Care Drugs Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 4: North America Diabetes Care Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 5: North America Diabetes Care Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 6: North America Diabetes Care Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 7: North America Diabetes Care Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 8: North America Diabetes Care Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 9: North America Diabetes Care Drugs Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Diabetes Care Drugs Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 11: Europe Diabetes Care Drugs Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 12: Europe Diabetes Care Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 13: Europe Diabetes Care Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 14: Europe Diabetes Care Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 15: Europe Diabetes Care Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 16: Europe Diabetes Care Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 17: Europe Diabetes Care Drugs Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Diabetes Care Drugs Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 19: Asia Pacific Diabetes Care Drugs Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 20: Asia Pacific Diabetes Care Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 21: Asia Pacific Diabetes Care Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 22: Asia Pacific Diabetes Care Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 23: Asia Pacific Diabetes Care Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Asia Pacific Diabetes Care Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Asia Pacific Diabetes Care Drugs Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Latin America Diabetes Care Drugs Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 27: Latin America Diabetes Care Drugs Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 28: Latin America Diabetes Care Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 29: Latin America Diabetes Care Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 30: Latin America Diabetes Care Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 31: Latin America Diabetes Care Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 32: Latin America Diabetes Care Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 33: Latin America Diabetes Care Drugs Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Middle East & Africa Diabetes Care Drugs Market Revenue (Billion), by Drug Class 2026 & 2034
Figure 35: Middle East & Africa Diabetes Care Drugs Market Revenue Share (%), by Drug Class 2026 & 2034
Figure 36: Middle East & Africa Diabetes Care Drugs Market Revenue (Billion), by Route of Administration 2026 & 2034
Figure 37: Middle East & Africa Diabetes Care Drugs Market Revenue Share (%), by Route of Administration 2026 & 2034
Figure 38: Middle East & Africa Diabetes Care Drugs Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 39: Middle East & Africa Diabetes Care Drugs Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: Middle East & Africa Diabetes Care Drugs Market Revenue (Billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Diabetes Care Drugs Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Diabetes Care Drugs Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 2: Global Diabetes Care Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 3: Global Diabetes Care Drugs Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 4: Global Diabetes Care Drugs Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North America Diabetes Care Drugs Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 6: North America Diabetes Care Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 7: North America Diabetes Care Drugs Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 8: North America Diabetes Care Drugs Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: USA Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Canada Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Mexico Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Europe Diabetes Care Drugs Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 13: Europe Diabetes Care Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 14: Europe Diabetes Care Drugs Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 15: Europe Diabetes Care Drugs Market Revenue Billion Forecast, by Country 2020 & 2034
Table 16: Germany Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: UK Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: France Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Italy Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Spain Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Rest of EU Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia Pacific Diabetes Care Drugs Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 23: Asia Pacific Diabetes Care Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 24: Asia Pacific Diabetes Care Drugs Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 25: Asia Pacific Diabetes Care Drugs Market Revenue Billion Forecast, by Country 2020 & 2034
Table 26: China Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Japan Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: India Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: South Korea Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Rest of APAC Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Latin America Diabetes Care Drugs Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 32: Latin America Diabetes Care Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 33: Latin America Diabetes Care Drugs Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 34: Latin America Diabetes Care Drugs Market Revenue Billion Forecast, by Country 2020 & 2034
Table 35: Brazil Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Argentina Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: Colombia Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Rest of LA Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Middle East & Africa Diabetes Care Drugs Market Revenue Billion Forecast, by Drug Class 2020 & 2034
Table 40: Middle East & Africa Diabetes Care Drugs Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Table 41: Middle East & Africa Diabetes Care Drugs Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 42: Middle East & Africa Diabetes Care Drugs Market Revenue Billion Forecast, by Country 2020 & 2034
Table 43: GCC Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: South Africa Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Rest of MEA Diabetes Care Drugs Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the diabetes care drugs market?
The global diabetes care drugs market is estimated at USD 93.79 billion in 2026 and is projected to reach USD 111.5 billion by 2031, growing at a 3.52% CAGR according to our first-party research.
2Which drug class dominates the diabetes care drugs market?
Insulin held 56.56% of the market share in 2025, but non-insulin injectables (GLP-1 receptor agonists) are growing faster at a 4.25% CAGR through 2031.
3What are the key drivers of the diabetes care drugs market?
Key drivers include escalating global diabetes prevalence (588.7 million adults in 2024), rising healthcare expenditures in emerging markets, and strong clinical evidence for GLP-1 and SGLT-2 classes.
4Which region is expected to grow fastest in the diabetes care drugs market?
Asia-Pacific is forecast to expand at a 5.51% CAGR to 2031, driven by high diabetes prevalence, expanding reimbursement, and government screening initiatives in China and India.
5Who are the major players in the diabetes care drugs market?
The market is dominated by Novo Nordisk, Sanofi, AstraZeneca, Boehringer Ingelheim, and Eli Lilly and Company, which are investing heavily in GLP-1 capacity and next-generation therapies.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research effort is allocated to primary research, conducting interviews with senior executives, clinical specialists, and procurement directors across the diabetes care value chain.
Targeted stakeholders include: Chief Medical Officers, Diabetes & Endocrinology Specialists, Pharmaceutical Procurement Managers, and Reimbursement Policy Advisors.
Interviews are conducted across 24 countries, with a focus on high-growth markets in Asia-Pacific, Latin America, and the Middle East.
Primary data collection includes 320+ interviews annually, capturing pricing, volume, and adoption trends at the therapeutic class and brand level.
Verified participant roles and affiliations ensure data reliability; all interview transcripts are coded and analyzed using NVivo.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Medical Officers
25%
Diabetes & Endocrinology Specialists
30%
Pharmaceutical Procurement Managers
25%
Reimbursement Policy Advisors
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Pharmaceutical Manufacturers
40%
Biotechnology Companies
25%
Contract Manufacturing Organizations
15%
Distributors & Wholesalers
12%
Digital Health & Device Integrators
8%
Secondary Research & Industry Benchmarking
20–30% of research effort is dedicated to secondary research, leveraging standard financial databases (Bloomberg, Factiva, Hoovers, PitchBook) and official sources such as the World Health Organization (WHO), International Diabetes Federation (IDF), U.S. Food and Drug Administration (FDA), European Medicines Agency (EMA), and national health ministries.
Trade data from UN Comtrade and Eurostat is used to triangulate API and finished drug flows.
Clinical trial registries (ClinicalTrials.gov, EU CTR) and regulatory approvals are monitored for pipeline and competitive intelligence.
Industry association benchmarks from the American Diabetes Association (ADA) and European Association for the Study of Diabetes (EASD) provide guideline-driven demand signals.
Demand Modeling & Market Estimation
Bottom-up market sizing is performed using four key quantitative metrics: (1) diagnosed prevalent cases by country and age group; (2) treatment initiation rates by drug class; (3) average annual cost of therapy (ACoT) by brand and generic; and (4) volume growth from new product launches.
Top-down estimation validates bottom-up results using company-reported revenues, prescription audit data, and reimbursement claims databases.
Multi-level data triangulation reconciles discrepancies between primary interview estimates and secondary audits, with a guaranteed data accuracy level of 85–90%.
All datasets undergo rigorous validation through cross-referencing with company financial statements, government health expenditure reports, and trade statistics.
A senior analyst panel reviews all market estimates and forecast assumptions quarterly.
Sensitivity analysis is conducted for key variables (e.g., GLP-1 supply constraints, IRA impact, biosimilar penetration rates) to ensure robustness.
Each report is updated to the date of purchase, incorporating the latest regulatory approvals, clinical trial readouts, and market developments.
Infrared Imaging Photodetectors Market valued at $1.23B in 2025, projected to reach $2.20B by 2034 at 8.7% CAGR. Defense, industrial, automotive drive growth.
The Trauma Informed Therapy Service market is valued at $1.42B in 2025, growing at 16.5% CAGR to reach $5.62B by 2034, driven by telehealth and PTSD care.
Nov 2026|224 pages
$2900.00
The global veterinary hospital market was valued at USD 67.8 billion in 2025 and is set to grow at a 7.1% CAGR, reaching USD 132.8 billion by 2035.
Nov 2026|263 pages
$2900.00
14C-Urea Breath Test Kit market to grow from USD 165.8 million in 2025 to USD 312 million by 2035 at 6.5% CAGR, driven by H. pylori screening.