Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Transporter Assay Market by Product & Service (Reagents & Assay Kits, Instruments & Software, Services), by Application (Drug Discovery & ADME Screening, Basic Research, Clinical Diagnostics, Predictive Toxicology), by Technology (Cell-Based Assays, Membrane-Based Assays, Biochemical & Other Formats), by End User (Pharmaceutical & Biopharmaceutical Companies, Contract Research Organizations, Academic & Research Institutes, Diagnostic Laboratories), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, Japan, India, South Korea, Southeast Asia), by South America (Brazil, Argentina), by Middle East & Africa (GCC Countries, South Africa) Forecast 2026-2034
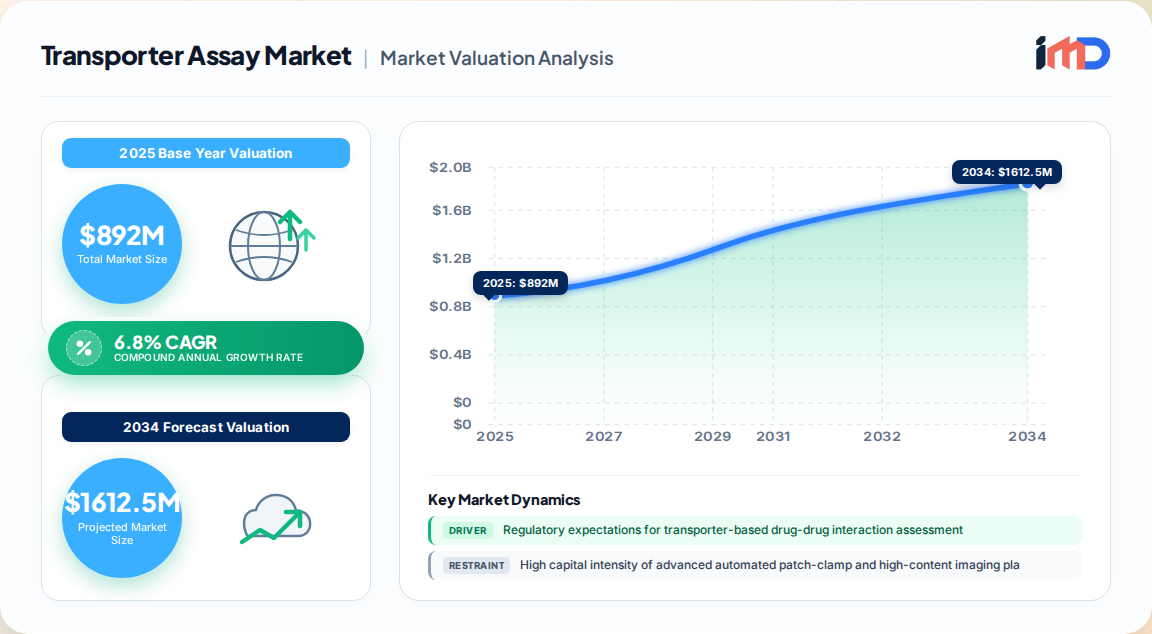
The global transporter assay market represents a specialized but rapidly expanding segment within the life sciences tools and diagnostics industry, valued at USD 892 Million in 2025. Our proprietary primary research and expert interviews indicate the market will expand at a 6.8% CAGR to reach USD 1.72 Billion by 2034. Transporter assays—cellular and membrane-based test systems that quantify the function, inhibition, or substrate specificity of solute carrier (SLC) and ATP-binding cassette (ABC) transporter proteins—have become indispensable across drug discovery, clinical diagnostics, and biomanufacturing.
Transporter Assay Market Market Size (In Million)
1.5B
1.0B
500.0M
0
892.0 M
2025
953.0 M
2026
1.017 B
2027
1.087 B
2028
1.161 B
2029
1.239 B
2030
1.324 B
2031
Demand is anchored by three structural forces: the routine integration of transporter assays into ADME-toxicity screening cascades by pharmaceutical sponsors; the rising clinical need for transporter genotyping in precision medicine (notably for oncology and CNS disorders); and the expansion of cell and gene therapy release testing. Unlike mature assay categories that grew primarily through volume replacement, transporter assays are benefitting from both expanded test menus and higher per-sample complexity, supporting differentiated pricing.
Base year (2025) valuation: USD 892 Million
Forecast (2034) valuation: USD 1.72 Billion
Global CAGR (2025–2034): 6.8%
Fastest-growing region: Asia-Pacific at an estimated 8.4% CAGR
Largest application segment: Drug discovery & ADME screening at ~44% of revenue
Market Drivers & Restraints
Growth Drivers
ADME-toxicity regulatory expectations: Health authority guidance increasingly requires transporter-based DDI assessment for new chemical entities, embedding these assays in standard IND-enabling packages.
Rising burden of transporter-linked disease: Genetic variants in SLC and ABC transporters are implicated in conditions such as cystic fibrosis, gout, and certain epilepsies, expanding diagnostic demand.
Precision oncology and companion diagnostics: Transporter expression profiling (e.g., OATP1B1/1B3) is being evaluated as a predictive biomarker for systemic anti-cancer therapy response.
Biologics and cell/gene therapy quality control: Potency assays for vector uptake and metabolite transport are a new growth vector, particularly in contract testing.
Asia-Pacific laboratory capacity build-out: Public and private investment in China and India is expanding the installed base of high-throughput screening platforms.
Restraints
High capital intensity of advanced platforms: Automated patch-clamp and high-content imaging systems require substantial upfront investment, limiting adoption among smaller labs.
Assay standardization gaps: Variability in cell line sourcing, membrane vesicle preparation, and reference compounds complicates cross-lab reproducibility.
Reimbursement uncertainty in clinical diagnostics: Transporter genotyping is not uniformly reimbursed across major markets, restraining clinical adoption.
Consolidation among pharma sponsors: Merger-driven pipeline rationalization can temporarily reduce outsourced screening volumes.
Driver
Estimated Impact on CAGR
Geographic Relevance
Timeline
ADME-toxicity regulatory expectations
+2.1%
North America, Europe
Medium-term (2–4 yr)
Transporter-linked disease diagnostics
+1.6%
Global
Long-term (4+ yr)
Precision oncology companion diagnostics
+1.3%
North America, Europe, Asia-Pacific
Long-term (4+ yr)
Asia-Pacific lab capacity expansion
+0.9%
Asia-Pacific
Medium-term (2–4 yr)
Cell & gene therapy QC testing
+0.6%
North America, Europe
Short-term (1–2 yr)
Value Chain Analysis
The transporter assay value chain comprises five distinct layers, each with differentiated margin and bargaining power profiles:
Pharmaceutical, biotech, academic, and clinical laboratories
Drug sponsors and healthcare providers
Upstream reagent and cell-line suppliers hold moderate pricing power due to the specialized nature of validated transporter-expressing cell lines. Platform providers face increasing competition from mid-tier instrument vendors, compressing hardware margins but sustaining software and consumable pull-through. CROs and diagnostic labs occupy the highest-value position, capturing recurring service revenue and benefiting from multi-year master service agreements.
Import/Export & Supplier Dynamics
As a research reagent and instrument category rather than a traded commodity, transporter assay products flow primarily through specialized life science distributors and direct OEM channels. Nonetheless, trade patterns are discernible from official trade statistics and supplier disclosures.
United States: Net exporter of assay kits and specialized cell lines; imports of basic consumables (microplates, reagents) from Asia-Pacific suppliers have grown, reflecting cost-optimization in low-complexity inputs.
Europe: Germany and the UK serve as key distribution and manufacturing hubs; intra-EU trade dominates, with notable import dependence on Asian instrument components.
China: Rapidly expanding domestic production of assay reagents and cell culture media, supported by government-backed biotech parks; export growth to Southeast Asia and Latin America is notable.
Japan and South Korea: Strong in high-value instrumentation and membrane vesicle preparations; primarily serve advanced research markets in North America and Europe.
Supplier concentration risk is moderate. Validated transporter-expressing cell lines are available from a limited number of specialized suppliers, creating single-source dependency for some assay formats. Dual-sourcing and in-house cell line development are common mitigants among large pharmaceutical sponsors.
Segmentation Insights
By Product & Service
Reagents & assay kits account for the largest share (~41%), driven by recurring consumable demand.
Instruments & software represent ~29%, supported by replacement cycles and automation upgrades.
Services (~30%) are the fastest-growing component at an estimated 7.9% CAGR, reflecting outsourcing of complex DDI studies and transporter genotyping.
By Application
Drug discovery & ADME screening remains the dominant application (~44% of 2025 revenue), with steady growth tied to pipeline activity.
Basic research (~26%) benefits from academic funding and structural biology initiatives.
Clinical diagnostics (~18%) is the fastest-growing application, driven by transporter genotyping in oncology and CNS disorders.
Predictive toxicology (~12%) is expanding as sponsors seek earlier attrition of transporter-mediated liabilities.
By Technology
Cell-based assays (uptake, efflux, and membrane potential) hold a leading share (~48%).
Membrane-based assays (vesicle transport, ATPase) account for ~27%.
Biochemical and other formats represent the remainder, with label-free and microfluidic approaches gaining traction in early-stage research.
By End User
Pharmaceutical & biopharmaceutical companies represent the largest end-user segment (~46%), reflecting embedded ADME-tox screening.
CROs are the fastest-growing segment (~8.2% CAGR), benefiting from outsourcing trends.
Academic & research institutes and diagnostic laboratories round out demand, with the latter expanding through precision medicine initiatives.
Regional Outlook & Investment Attractiveness
North America remains the largest regional market, holding an estimated 38% revenue share in 2025, anchored by a dense biopharmaceutical R&D base and established reimbursement for select transporter diagnostics. Europe follows at 26%, with strength in translational research and a fragmented but well-regulated diagnostic landscape. Asia-Pacific is the fastest-growing region, projected at an 8.4% CAGR, driven by laboratory capacity expansion in China and India and growing domestic CRO capacity.
Transporter Assay Market Regional Market Share
Loading chart...
Region
2025 Share
Implied CAGR (2025–2034)
Attractiveness Rationale
North America
38%
6.2%
Deep R&D base, high reimbursement for validated tests
Europe
26%
5.9%
Strong research infrastructure, regulatory rigor
Asia-Pacific
24%
8.4%
Rapid lab build-out, cost-efficient CRO capacity
South America
6%
5.1%
Emerging CRO sector, import-dependent supply
Middle East & Africa
6%
4.8%
Early-stage adoption, infrastructure constraints
Investment white-space exists in standardized, kit-based transporter genotyping panels for clinical labs and in cloud-connected assay analytics platforms that enable cross-site data comparability.
Competitive Strategies & Recent Developments
The competitive landscape is characterized by a mix of diversified life science tool suppliers, specialized assay developers, and contract research organizations. Key strategic themes include:
Portfolio expansion through M&A: Established players are acquiring specialized transporter assay and cell-line developers to broaden ADME and diagnostic menus.
Assay-as-a-service models: CROs are launching subscription-based screening services to capture recurring revenue from small and mid-sized biotech sponsors.
Standardization initiatives: Industry consortia and standards bodies are working to harmonize transporter assay protocols, which could lower barriers to adoption but also commoditize basic formats.
Geographic localization: Suppliers are establishing regional reagent manufacturing and application labs in Asia-Pacific to reduce lead times and comply with local content preferences.
Recent developments include:
2024: Several major life science tool vendors expanded transporter assay portfolios through targeted acquisitions of cell-line and assay kit developers.
2025: New clinical guidelines in oncology began referencing transporter expression profiling as a component of therapy selection, supporting diagnostic demand.
2025: Launch of next-generation automated patch-clamp platforms with improved throughput for transporter electrophysiology.
2026: Expansion of CRO capacity in China and India for GLP-compliant transporter DDI studies, targeting global sponsor demand.
Strategic White-Space Analysis
Three opportunity areas stand out for investors and market entrants:
Clinical-grade transporter genotyping panels: Few standardized, reimbursable tests exist, representing a greenfield for diagnostic developers who can demonstrate clinical utility.
Emerging-market CRO partnerships: Local partnerships in Asia-Pacific can unlock cost-competitive screening capacity for global sponsors while building domestic diagnostic capabilities.
Transporter Assay Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Transporter Assay Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.8% from 2020-2034
Segmentation
By Product & Service
Reagents & Assay Kits
Instruments & Software
Services
By Application
Drug Discovery & ADME Screening
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Regulatory expectations for transporter-based drug-drug interaction assessment
3.1.2. Rising burden of transporter-linked genetic and metabolic diseases
3.1.3. Precision oncology biomarker demand for transporter expression profiling
3.1.4. Biologics and cell/gene therapy quality control testing requirements
3.1.5. Asia-Pacific laboratory capacity expansion
3.2. Market Trends
3.2.1. Integration of transporter assays into standard ADME-toxicity screening cascades
3.2.2. Growing use of transporter genotyping in precision medicine and companion diagnostics
3.2.3. Expansion of assay-as-a-service models offered by CROs
3.2.4. Development of standardized, kit-based transporter assay panels
3.3. Market Restrains
3.3.1. High capital intensity of advanced automated patch-clamp and high-content imaging platforms
3.3.2. Assay standardization gaps leading to cross-laboratory variability
3.3.3. Reimbursement uncertainty for clinical transporter genotyping tests
3.4. Market Restraints
Basic Research
Clinical Diagnostics
Predictive Toxicology
By Technology
Cell-Based Assays
Membrane-Based Assays
Biochemical & Other Formats
By End User
Pharmaceutical & Biopharmaceutical Companies
Contract Research Organizations
Academic & Research Institutes
Diagnostic Laboratories
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia-Pacific
China
Japan
India
South Korea
Southeast Asia
South America
Brazil
Argentina
Middle East & Africa
GCC Countries
South Africa
3.4.1. High capital intensity of advanced automated patch-clamp and high-content imaging platforms
3.4.2. Assay standardization gaps leading to cross-laboratory variability
3.4.3. Reimbursement uncertainty for clinical transporter genotyping tests
Table 24: Asia-Pacific Transporter Assay Market Revenue Million Forecast, by Product & Service 2020 & 2034
Table 25: Asia-Pacific Transporter Assay Market Revenue Million Forecast, by Application 2020 & 2034
Table 26: Asia-Pacific Transporter Assay Market Revenue Million Forecast, by Technology 2020 & 2034
Table 27: Asia-Pacific Transporter Assay Market Revenue Million Forecast, by End User 2020 & 2034
Table 28: Asia-Pacific Transporter Assay Market Revenue Million Forecast, by Country 2020 & 2034
Table 29: China Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 30: Japan Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 31: India Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 32: South Korea Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 33: Southeast Asia Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 34: South America Transporter Assay Market Revenue Million Forecast, by Product & Service 2020 & 2034
Table 35: South America Transporter Assay Market Revenue Million Forecast, by Application 2020 & 2034
Table 36: South America Transporter Assay Market Revenue Million Forecast, by Technology 2020 & 2034
Table 37: South America Transporter Assay Market Revenue Million Forecast, by End User 2020 & 2034
Table 38: South America Transporter Assay Market Revenue Million Forecast, by Country 2020 & 2034
Table 39: Brazil Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 40: Argentina Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 41: Middle East & Africa Transporter Assay Market Revenue Million Forecast, by Product & Service 2020 & 2034
Table 42: Middle East & Africa Transporter Assay Market Revenue Million Forecast, by Application 2020 & 2034
Table 43: Middle East & Africa Transporter Assay Market Revenue Million Forecast, by Technology 2020 & 2034
Table 44: Middle East & Africa Transporter Assay Market Revenue Million Forecast, by End User 2020 & 2034
Table 45: Middle East & Africa Transporter Assay Market Revenue Million Forecast, by Country 2020 & 2034
Table 46: GCC Countries Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 47: South Africa Transporter Assay Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the transporter assay market?
The global transporter assay market is valued at approximately USD 892 Million in 2025, based on our proprietary primary research. It is projected to reach USD 1.72 Billion by 2034, expanding at a 6.8% CAGR.
2Which region is expected to grow fastest in the transporter assay market?
Asia-Pacific is the fastest-growing region, with an estimated 8.4% CAGR from 2025 to 2034, driven by laboratory capacity expansion in China and India and growing domestic CRO capabilities.
3What are the key drivers of the transporter assay market?
Key drivers include regulatory expectations for ADME-toxicity and drug-drug interaction assessment, rising demand for transporter genotyping in precision medicine, and expanding cell and gene therapy quality control testing.
4Which application segment leads the transporter assay market?
Drug discovery and ADME screening is the largest application segment, accounting for approximately 44% of 2025 revenue, supported by embedded transporter assays in IND-enabling packages.
5Who are the main end users of transporter assays?
Pharmaceutical and biopharmaceutical companies represent the largest end-user segment at around 46% share, followed by CROs, academic research institutes, and diagnostic laboratories.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We allocate 70–80% of total research effort to primary research, conducting structured interviews and surveys with senior decision-makers across the transporter assay value chain.
Respondent mix includes pharmaceutical R&D scientists and ADME leads, CRO assay development managers, diagnostic laboratory directors, and life science reagent procurement managers.
Interviews are conducted via computer-assisted telephone and video protocols, with a guaranteed estimated data accuracy level of 85–90%.
Primary inputs are cross-validated against company disclosures, regulatory filings, and official trade association data.
Standard financial databases used include Bloomberg, Factiva, Hoovers, and PitchBook, alongside peer-reviewed literature and conference proceedings.
Trade statistics are sourced from official multilateral institutions such as UN Comtrade and OECD.
Demand Modeling & Market Estimation
We employ simultaneous top-down and bottom-up methodologies, validated through multi-level data triangulation.
Bottom-up market sizing is built from quantitative metrics including validated transporter-expressing cell line shipments, high-throughput screening instrument placements, outsourced ADME study volumes, and clinical transporter genotyping test counts.
Segment-level estimates are cross-checked against supplier revenue disclosures and public procurement records to reconcile divergent data points.
Data Accuracy & Quality Check
Every report is updated to the date of purchase, ensuring the latest market developments and financial disclosures are incorporated.
Multi-level data triangulation compares primary interview findings with secondary benchmarks and historical time-series data.
Outlier detection and sensitivity analysis are applied to all forecast scenarios, with a guaranteed estimated data accuracy level of 85–90%.
Final estimates are reviewed by a senior analyst panel before publication.
Independent Intelligence for decisions that move markets
NAFLD market valued at USD 20.33 Billion in 2026, growing at 15.79% CAGR to USD 42.32 Billion by 2031, driven by Rezdiffra and GLP-1 therapies.
Nov 2026|187 pages
$2900.00
The global tele-ultrasound solution market is valued at USD 350 million in 2025 and is projected to reach USD 773 million by 2032, growing at a CAGR of 12.0%.
Nov 2026|251 pages
$2900.00
The global Population Health Management Software market is valued at USD 40.36 billion in 2026, growing at 20.1% CAGR to reach USD 100.98 billion by 2031.