1What is the current size of the Medical Examination Service market?
The global market was valued at USD 4.2 billion in 2025 and is projected to reach USD 8.5 billion by 2034, growing at an 8.5% CAGR according to our proprietary research.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Medical Examination Service
 by Service Type (Physical Examination, Review-Based Independent Medical Services, Functional / Work-Capacity Assessment, Claims-Support / Cost-Containment, Workflow / Network Administration), by Delivery Mode (In-Person Examination, Telehealth / Virtual, Hybrid (Exam + File Review), Records-Only Review), by End-User (Insurance Companies, Government Agencies, Employers, Legal Entities, Healthcare Providers), by Case Type (Workers' Compensation, Disability Claims, Auto and Personal Injury, Liability and Litigation, Group Health and Medical Necessity Reviews, Occupational Health / Fitness for Duty), by Specialty (Orthopedic and Musculoskeletal, Neurology, Psychiatry and Psychology, Occupational and Physical Medicine, Internal Medicine, Other Specialties), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia-Pacific (China, Japan, India, South Korea, Australia, Rest of APAC), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034


Research Analyst
 Related Reports

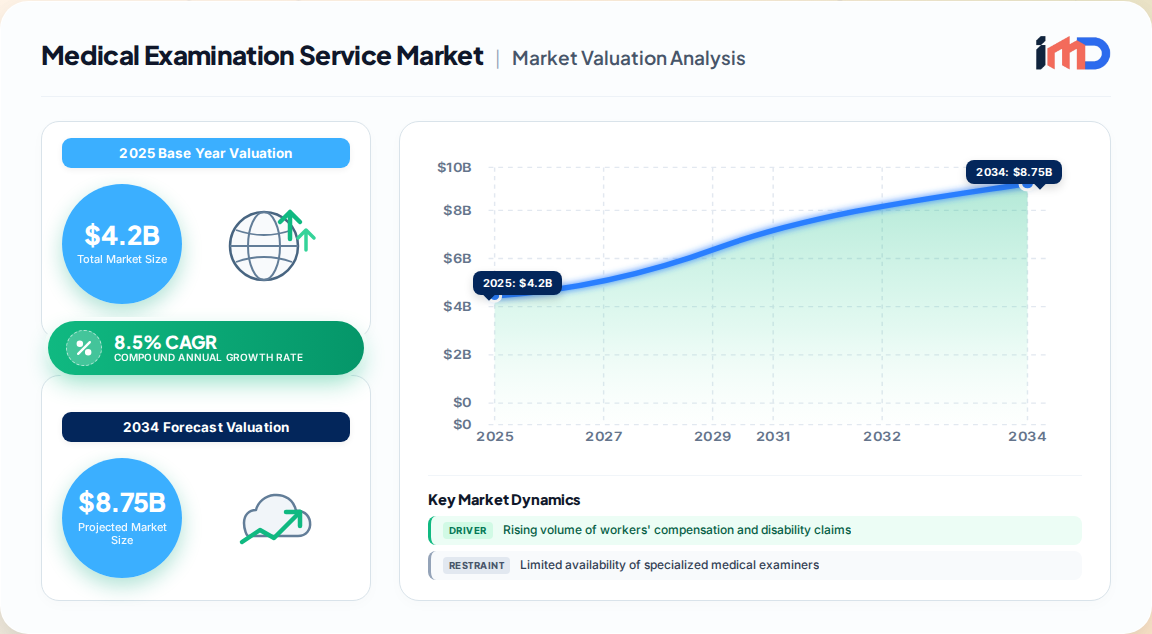
The global Medical Examination Service market is undergoing a profound structural transformation. No longer merely an administrative adjunct to insurance claims, these services now form the evidentiary backbone of risk adjudication, regulatory compliance, and medico-legal dispute resolution across public and private payers. Our proprietary primary research and expert interviews indicate that the market is on a strong growth trajectory, with demand fundamentals underpinning sustained double-digit expansion in high-acuity segments.
Key market metrics (2025 base year):
The expansion of the Medical Examination Service market is propelled by a confluence of regulatory, demographic, and technological forces. Our analysis isolates the following key dynamics:
The Medical Examination Service market is best understood through a multi-dimensional segmentation lens. Our analysis identifies the following dominant segments and their shares:
| Service Type | Market Share (2025) | Key Characteristics |
|---|---|---|
| Physical Examination | Largest | Delivers firsthand clinical evidence; essential for musculoskeletal, orthopedic, and chronic pain cases. |
| Review-Based Independent Medical Services | Significant | Records-only review; cost-effective for clear-cut cases and initial triage. |
| Functional / Work-Capacity Assessment | Growing | Evaluates ability to perform job functions; critical for return-to-work decisions. |
| Claims-Support / Cost-Containment Services | Niche | Focuses on billing reviews, utilization management, and fraud detection. |
| Workflow / Network Administration Services | Emerging | Provides end-to-end management of IME networks and scheduling. |
Physical examination dominates due to its irreplaceable role in providing objective, tangible findings that withstand scrutiny from insurers, legal entities, and government bodies. The segment is reinforced by innovations in standardized functional testing and the growing emphasis on patient-centered care.
| Case Type | Share (2025) | Growth Outlook |
|---|---|---|
| Workers' Compensation | Dominant | Steady, supported by state-mandated independent evaluations (e.g., QME in California, Designated Doctor in Texas). |
| Disability Claims | High | Strong, driven by aging workforce and federal benefit programs. |
| Auto and Personal Injury | Moderate | Growing with litigation trends and no-fault insurance reforms. |
| Liability and Litigation | Niche | Specialized, high-value engagements for expert witness testimony. |
| Group Health and Medical Necessity Reviews | Emerging | Expanding with utilization management and value-based care. |
North America remains the epicenter of the Medical Examination Service market, accounting for 41.2% of global revenue in 2023. This leadership is underpinned by a mature healthcare infrastructure, a highly developed legal and insurance ecosystem, and stringent regulatory frameworks governing workers' compensation and disability claims. The presence of well-established providers with extensive examiner networks creates a competitive but consolidated landscape.
Europe follows as the second-largest market, with growth driven by regulatory harmonization and cross-border claims management. The region's emphasis on standardized medical evaluations and social security systems provides a stable demand base, though market fragmentation and language diversity pose operational challenges.
Asia-Pacific is poised to register the highest CAGR during the forecast period, albeit from a smaller base. Rapid industrialization, growing insurance penetration, and increasing awareness of independent medical assessments in markets such as China, Japan, and India are key growth catalysts. However, regulatory variability and limited examiner supply remain constraints.
South America and the Middle East & Africa represent emerging frontiers, with growth potential tied to insurance market liberalization, infrastructure development, and the adoption of digital delivery models.
The Medical Examination Service market is characterized by a mix of large, diversified service providers and specialized regional players. Our competitive intelligence reveals a landscape where scale, technology integration, and regulatory compliance are critical success factors.
Leading providers are pursuing strategies to expand their examiner networks, invest in digital platforms, and integrate AI-driven analytics for faster report generation and quality assurance. Key developments observed include:
Our analysis identifies several high-potential white spaces for stakeholders:
The Medical Examination Service market is fundamentally a service-based sector, and its "trade" dynamics differ from goods markets. Cross-border supply (Mode 1) is increasingly relevant through telehealth and remote review services, allowing providers in one country to serve clients in another. However, regulatory and licensing requirements often restrict the practice of medicine across borders, limiting direct export potential for core examination services.
Supply-side dynamics are driven by the availability of qualified medical examiners, access to comprehensive medical records, and the technological infrastructure for secure data exchange. The market's supply chain is essentially a network of independent contractors (physicians, specialists) coordinated by administrative entities. Key supplier risks include examiner attrition, specialty shortages, and cybersecurity vulnerabilities in handling protected health information.
The Medical Examination Service market is poised for robust growth, with a projected CAGR of 8.5% from 2026 to 2034. The convergence of regulatory mandates, technological innovation, and evolving payer needs will reshape service delivery. We anticipate that by 2030, telehealth-enabled and AI-assisted evaluations will represent a substantial share of total service volume, particularly for routine assessments, while complex cases will continue to require in-person examination.
Stakeholders should prioritize investments in digital infrastructure, examiner network expansion, and quality assurance to capitalize on growth opportunities. The market's resilience during economic downturns—underpinned by non-discretionary nature of claims adjudication—further enhances its attractiveness for investors and service providers alike.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.5% from 2020-2034 |
| Segmentation |
|
By Delivery Mode
By End-User
By Case Type
By Specialty
| By Geography |
|
The global market was valued at USD 4.2 billion in 2025 and is projected to reach USD 8.5 billion by 2034, growing at an 8.5% CAGR according to our proprietary research.
North America holds the largest share, accounting for 41.2% of global revenue in 2023, driven by a mature insurance ecosystem and stringent regulatory requirements for independent medical evaluations.
Major drivers include the rising volume of workers' compensation and disability claims, stringent regulatory mandates for independent medical evidence, and the growing adoption of telehealth and hybrid evaluation models.
Physical examination is the leading service type, as it provides firsthand clinical evidence essential for accurate diagnosis and credible assessments in workers' compensation, disability, and personal injury cases.
Insurance companies are the dominant end-users, utilizing these services for risk management and fraud mitigation. Government agencies and employers also represent significant demand, particularly for federal disability and workers' compensation programs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Medical Officer / Medical Director | 30% |
| Claims Director / VP of Claims | 25% |
| Independent Medical Examiner (Physician) | 20% |
| Workers' Compensation Program Manager | 15% |
| Regulatory Compliance Officer | 10% |
| Company Type | Representation (%) |
|---|---|
| Independent Medical Examination Providers | 35% |
| Insurance Carriers and Third-Party Administrators | 25% |
| Government Agencies and Disability Programs | 20% |
| Telehealth and Technology Platform Vendors | 12% |
| Legal and Claims Management Firms | 8% |