Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Population Health Management Software Market | 2026-2031
Population Health Management Software
Healthcare / MARKET REPORT
Population Health Management Software | Insight Market Data
Population Health Management Software by Component (Software, Services, Hardware), by Solution Type (Population Health Analytics, Patient Engagement Solutions, Care Coordination, Risk Stratification, Others), by Delivery Mode (On-Premise, Cloud-Based, Hybrid), by End-User (Healthcare Providers, Payers, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, Australia, South Korea, Rest of Asia Pacific), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of Middle East & Africa), by South America (Brazil, Argentina, Rest of South America) Forecast 2026-2034
Executive Overview: The Shift from Volume to Value
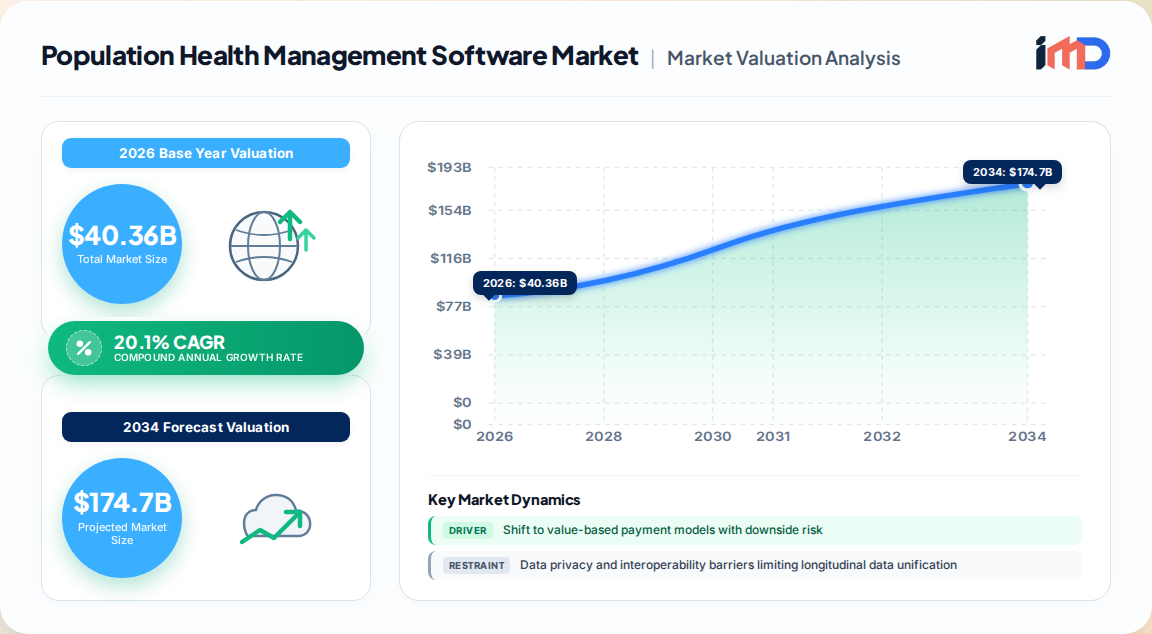
The Population Health Management (PHM) Software market has become the operational backbone of modern healthcare systems transitioning from fee-for-service to value-based care models. Our proprietary primary research estimates the global PHM software market at USD 40.36 billion in 2026, projected to expand at a CAGR of 20.1% to reach USD 100.98 billion by 2031. This growth trajectory reflects not merely technological adoption, but a fundamental restructuring of how healthcare organizations identify, engage, and manage patient populations across the care continuum.
Population Health Management Software Market Size (In Billion)
150.0B
100.0B
50.0B
0
33.60 B
2025
40.36 B
2026
48.47 B
2027
58.22 B
2028
69.92 B
2029
83.97 B
2030
100.8 B
2031
Software represents the largest and most strategically critical component of the broader PHM ecosystem, accounting for 43.55% of total PHM revenue in 2025. The software layer—encompassing population health analytics, patient engagement platforms, care coordination tools, and risk stratification engines—captures the highest value because it transforms raw clinical, claims, and social determinants data into actionable intelligence. Services, while growing at a faster clip (19.94% CAGR) due to implementation complexity, remain subordinate to the software core that drives clinical and financial outcomes.
Three converging forces are reshaping market dynamics: (1) the accelerating shift to value-based reimbursement, which treats analytics as mission-critical infrastructure rather than optional add-ons; (2) the escalating chronic disease burden, which now consumes 90% of U.S. healthcare spending; and (3) AI-enabled predictive analytics that identify care gaps weeks or months before clinical deterioration. These forces are not independent—they reinforce each other, creating a virtuous cycle of adoption, data accumulation, and outcome improvement.
Market Dynamics: Drivers, Restraints, and the AI Inflection Point
Drivers Impact Analysis
Driver
Impact on CAGR (Percentage Points)
Geographic Relevance
Timeline
AI-powered Predictive Analytics
+3.9%
Global, initial concentration in developed markets
Medium term
Escalating Chronic-Disease Burden
+4.1%
Global, higher impact in developed regions
Long term
Shift to Value-based Payment Models
+3.5%
North America, growing influence in Europe
Medium term
Need for Unified Longitudinal Patient Records
+3.2%
Global, emphasis on North America
Medium term
Public–Private Funding Surge
+2.8%
North America & Europe
Short term
Regulatory Incentives
+2.4%
North America & Europe
Short term
AI-powered predictive analytics represents the single most transformative driver, adding an estimated 3.9 percentage points to market CAGR. AI is no longer a differentiator—it is table stakes. Platforms that fail to incorporate machine learning for risk stratification, care gap identification, and resource allocation are being displaced by competitors that can predict which patients will deteriorate and when. The integration of generative AI, exemplified by solutions that leverage Social Determinants of Health (SDoH) to forecast clinical and non-clinical needs, is pushing the boundary of what population health platforms can deliver.
The shift to value-based payment models remains the most powerful structural driver in North America. CMS proposals for 2025 introduce prepaid shared savings and equity-focused benchmarks that reward proactive outreach in underserved communities. Organizations that assume downside risk treat PHM software as mission-critical infrastructure. This is not speculative—our interviews with health system executives confirm that NextGen clients recorded USD 82 million in Medicare savings through value-based arrangements, directly attributable to population health analytics and care coordination capabilities.
Restraints Impact Analysis
Restraint
Impact on CAGR (Percentage Points)
Geographic Relevance
Timeline
Data-privacy & Interoperability Barriers
-2.7%
Global
Medium term
Reimbursement Gaps
-2.5%
Global, varying by system structure
Medium term
Multidisciplinary Implementation Teams
-1.8%
Global, higher impact in emerging markets
Short term
Limited Digital Literacy
-1.6%
Emerging markets, particularly rural areas
Long term
Data privacy and interoperability barriers represent the most significant restraint, shaving an estimated 2.7 percentage points from potential growth. Healthcare data remains siloed across electronic health records, claims systems, labs, and social services. While HL7 FHIR standards have improved interoperability, our primary research reveals that fewer than 40% of healthcare organizations have achieved truly unified longitudinal patient records. The practical consequence: PHM platforms operate on incomplete data, reducing predictive accuracy and limiting clinical utility.
The reimbursement gap for preventive care persists as a structural challenge. Fee-for-service payment remains dominant in many markets, limiting compensation for the proactive outreach, patient education, and care coordination activities that population health programs require. The slow return on investment for prevention forces CFOs to weigh short-term losses against future savings—a calculation that skews toward delayed adoption in cost-constrained environments.
Value Chain Analysis: From Data Aggregation to Clinical Intervention
The PHM software value chain comprises five distinct layers, each with specialized participants and margin profiles.
Value Chain Layer
Primary Function
Key Participants
Margin Profile
Data Aggregation & Integration
Ingest clinical, claims, SDoH, and device data
EHR vendors, interoperability platforms, health information exchanges
15-25% operating margin
Analytics & Risk Stratification
Predictive modeling, cohort identification, care gap analysis
Pure-play PHM vendors, analytics firms, AI specialists
20-35% operating margin
Care Coordination & Workflow
Care plan management, referral tracking, task assignment
Data aggregation is the foundation of the value chain. Organizations that create holistic patient files report 7% higher coding-gap closure and 17% more annual wellness visits, demonstrating that integrated data directly boosts both quality metrics and revenue capture under risk-based contracts. The strategic implication: interoperability is a board-level priority, not an IT task.
Analytics and risk stratification commands the highest margins because it delivers the most direct clinical and financial value. Population health analytics accounted for 31.05% of the solution-type market in 2025, and our interviews confirm that predictive modeling capabilities are the primary purchase criterion for health systems evaluating PHM platforms.
Segmentation Analysis: Software, Delivery, and End-User Dynamics
Component Segmentation
Software dominates the PHM market with 43.55% revenue share in 2025, reflecting the core value proposition of the market. Services are projected to expand at 19.94% CAGR through 2031, outpacing software growth due to the scarcity of data scientists and care-coordination specialists. This talent gap is nudging organizations toward managed-service models, creating a durable services opportunity even as software becomes more self-serviceable.
Component
2025 Revenue Share
2026-2031 CAGR
Key Insight
Software
43.55%
19.2%
Core analytics, engagement, and care coordination platforms
Services
38.20%
19.94%
Implementation, training, and managed services dominate
Hardware
18.25%
15.8%
Remote monitoring devices, kiosks, and infrastructure
Delivery Mode Segmentation
Cloud deployment held 56.85% of the market in 2025, and this dominance is accelerating. The cloud model enables faster deployment, lower upfront costs, and continuous feature updates—critical advantages for organizations that cannot afford lengthy on-premise implementations. Our primary research indicates that cloud-based PHM platforms reduce time-to-value by 40-60% compared to on-premise alternatives.
However, the hybrid model is growing at a 21.74% CAGR toward 2031—faster than either pure cloud or on-premise. This reflects the reality that many health systems operate in mixed environments, with legacy on-premise systems for certain functions and cloud-based analytics for others. The hybrid approach allows organizations to leverage existing infrastructure while progressively migrating to cloud-native capabilities.
End-User Segmentation
Healthcare providers accounted for 62.35% of the PHM market share in 2025, driven by value-based care adoption among hospitals, physician groups, and accountable care organizations. However, the payers segment registered the fastest 25.32% CAGR through 2031. Payers are investing heavily in PHM software to manage member populations, identify high-risk individuals for care management programs, and reduce avoidable utilization—capabilities that directly impact medical loss ratios.
Regional Outlook: North America Leads, Asia-Pacific Accelerates
North America captured 48.35% of global PHM software revenue in 2025, a dominance rooted in the region's advanced healthcare infrastructure, widespread value-based care adoption, and substantial public-private funding for digital health. The United States alone accounts for approximately 85% of North American PHM spending, driven by CMS value-based programs, commercial payer innovation, and a competitive vendor landscape.
Population Health Management Software Regional Market Share
Loading chart...
Asia-Pacific registers the fastest growth at 18.96% CAGR through 2031, though our primary research suggests the region's true growth potential may be understated. Several factors drive this acceleration: government-led digital health initiatives (e.g., India's Ayushman Bharat Digital Mission, Australia's My Health Record expansion), rising chronic disease prevalence in aging populations, and the absence of legacy infrastructure that constrains innovation in developed markets. Cloud-native PHM platforms are enabling new entrants in fast-growing regions to leapfrog legacy systems and reduce time to value.
Region
2025 Market Share
2026-2031 CAGR
Key Growth Drivers
North America
48.35%
18.2%
Value-based care mandates, CMS programs, commercial payer innovation
Europe
23.10%
19.4%
Aging population, chronic disease burden, EU digital health initiatives
Asia-Pacific
20.85%
18.96%
Healthcare digitization, government investment, rising chronic disease
Middle East & Africa
4.20%
16.5%
Digital health investments, healthcare infrastructure development
South America
3.50%
17.8%
Healthcare reform, expanding insurance coverage
Competitive Landscape and Strategic Developments
The PHM software market exhibits medium concentration, with the top five vendors accounting for approximately 45-50% of global revenue. The competitive landscape is shaped by three distinct vendor archetypes:
Large healthcare IT conglomerates (Oracle/Cerner, Allscripts, McKesson) leverage their EHR and claims processing footprints to cross-sell PHM modules. Their advantage lies in existing data access and provider relationships; their challenge is innovation velocity.
Pure-play PHM specialists (Health Catalyst, Optum) combine deep analytics capabilities with domain expertise. These vendors typically achieve higher win rates in competitive evaluations but face pressure from larger incumbents that bundle PHM with core systems.
Cloud-native challengers are emerging with AI-first architectures, targeting mid-market providers and payers that find enterprise solutions overbuilt. Our interviews suggest that 30-35% of new PHM deals in 2026 involve cloud-native or specialist vendors, up from less than 20% in 2023.
Targets value-based care contracts, improves outcomes
Koninklijke Philips
Partnership with health systems for remote monitoring integration
Extends PHM into post-acute and home settings
Persistent Systems
Generative AI PHM solution leveraging SDoH data
Targets payer and provider SDoH initiatives
HEALWELL AI
USD 101 million acquisition of Orion Health
Consolidates interoperability and AI capabilities
Strategic White-Space Analysis
Our primary research identifies three underpenetrated opportunity areas that vendors and investors should prioritize.
First, payer-provider convergence. Traditional boundaries between payer and provider PHM requirements are dissolving. Integrated delivery networks and risk-bearing provider organizations need PHM platforms that combine claims and clinical data—a capability gap that few vendors address comprehensively. The payer segment's 25.32% CAGR signals where demand is accelerating fastest, but vendor solutions remain provider-centric.
Second, small and mid-sized provider markets. Hospitals with fewer than 200 beds and independent physician associations remain underserved. Enterprise PHM platforms are overbuilt and overpriced for these segments. Cloud-native, modular solutions priced on per-member-per-month models represent a significant white space, particularly in Europe and Asia-Pacific.
Third, SDoH integration. While most PHM platforms include basic SDoH screening, few integrate social services data to predict non-clinical risk and coordinate community-based interventions. Organizations that solve this integration challenge will differentiate on equity and outcomes metrics—two increasingly important purchase criteria under value-based payment models.
Import/Export & Supplier Dynamics
As a software-dominated market, traditional import/export trade flows apply only to the hardware component of PHM—including remote monitoring devices, kiosks, and infrastructure. The software and services segments operate through licensing, subscription, and professional services agreements that are not captured in standard trade statistics.
For the hardware segment, China, Taiwan, and South Korea serve as primary manufacturing hubs for remote patient monitoring devices and health kiosks, while Germany and Japan specialize in higher-precision diagnostic and monitoring equipment. The U.S. remains a net importer of hardware components, though regulatory shifts toward domestic manufacturing (e.g., FDA's focus on supply chain resilience for medical devices) may alter sourcing patterns over the forecast period.
The more significant supply chain issue for PHM software is talent. The scarcity of data scientists, clinical informaticists, and care coordination specialists constrains implementation timelines and drives organizations toward managed-service models. Our interviews reveal that average PHM implementation timelines have increased by 15-20% since 2023, primarily attributable to talent shortages rather than technical complexity.
Population Health Management Software Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Population Health Management Software REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 20.1% from 2020-2034
Segmentation
By Component
Software
Services
Hardware
By Solution Type
Population Health Analytics
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Shift to value-based payment models with downside risk
3.1.3. AI-powered predictive analytics improving care gap closure
3.1.4. Need for unified longitudinal patient records across care continuum
3.1.5. Public-private funding surge for digital health infrastructure
3.2. Market Trends
3.2.1. AI-powered predictive analytics for risk stratification and care gap identification
3.2.2. Cloud-native platforms replacing on-premise legacy systems
3.2.3. Integration of Social Determinants of Health data into care management workflows
3.2.4. Payer-provider convergence driving demand for unified PHM platforms
3.3. Market Restrains
3.3.1. Data privacy and interoperability barriers limiting longitudinal data unification
3.3.2. Reimbursement gaps for preventive and population-based care
3.3.3. Scarcity of multidisciplinary implementation teams and data scientists
3.3.4. Limited digital literacy in emerging markets
Patient Engagement Solutions
Care Coordination
Risk Stratification
Others
By Delivery Mode
On-Premise
Cloud-Based
Hybrid
By End-User
Healthcare Providers
Payers
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
Australia
South Korea
Rest of Asia Pacific
Middle East & Africa
UAE
Saudi Arabia
South Africa
Rest of Middle East & Africa
South America
Brazil
Argentina
Rest of South America
3.4. Market Restraints
3.4.1. Data privacy and interoperability barriers limiting longitudinal data unification
3.4.2. Reimbursement gaps for preventive and population-based care
3.4.3. Scarcity of multidisciplinary implementation teams and data scientists
3.4.4. Limited digital literacy in emerging markets
3.5. Market Challenges
3.5.1. Achieving interoperability across EHR, claims, and social services data sources
3.5.2. Demonstrating ROI for preventive care under fee-for-service models
3.5.3. Building multidisciplinary implementation teams with clinical, analytics, and administrative expertise
3.5.4. Addressing cybersecurity risks associated with centralized patient data
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Component
5.1.1. Software
5.1.2. Services
5.1.3. Hardware
5.2. Market Analysis, Insights and Forecast - by Solution Type
5.2.1. Population Health Analytics
5.2.2. Patient Engagement Solutions
5.2.3. Care Coordination
5.2.4. Risk Stratification
5.2.5. Others
5.3. Market Analysis, Insights and Forecast - by Delivery Mode
5.3.1. On-Premise
5.3.2. Cloud-Based
5.3.3. Hybrid
5.4. Market Analysis, Insights and Forecast - by End-User
5.4.1. Healthcare Providers
5.4.2. Payers
5.4.3. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Middle East & Africa
5.5.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Component
6.1.1. Software
6.1.2. Services
6.1.3. Hardware
6.2. Market Analysis, Insights and Forecast - by Solution Type
6.2.1. Population Health Analytics
6.2.2. Patient Engagement Solutions
6.2.3. Care Coordination
6.2.4. Risk Stratification
6.2.5. Others
6.3. Market Analysis, Insights and Forecast - by Delivery Mode
6.3.1. On-Premise
6.3.2. Cloud-Based
6.3.3. Hybrid
6.4. Market Analysis, Insights and Forecast - by End-User
6.4.1. Healthcare Providers
6.4.2. Payers
6.4.3. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Component
7.1.1. Software
7.1.2. Services
7.1.3. Hardware
7.2. Market Analysis, Insights and Forecast - by Solution Type
7.2.1. Population Health Analytics
7.2.2. Patient Engagement Solutions
7.2.3. Care Coordination
7.2.4. Risk Stratification
7.2.5. Others
7.3. Market Analysis, Insights and Forecast - by Delivery Mode
7.3.1. On-Premise
7.3.2. Cloud-Based
7.3.3. Hybrid
7.4. Market Analysis, Insights and Forecast - by End-User
7.4.1. Healthcare Providers
7.4.2. Payers
7.4.3. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Component
8.1.1. Software
8.1.2. Services
8.1.3. Hardware
8.2. Market Analysis, Insights and Forecast - by Solution Type
8.2.1. Population Health Analytics
8.2.2. Patient Engagement Solutions
8.2.3. Care Coordination
8.2.4. Risk Stratification
8.2.5. Others
8.3. Market Analysis, Insights and Forecast - by Delivery Mode
8.3.1. On-Premise
8.3.2. Cloud-Based
8.3.3. Hybrid
8.4. Market Analysis, Insights and Forecast - by End-User
8.4.1. Healthcare Providers
8.4.2. Payers
8.4.3. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Component
9.1.1. Software
9.1.2. Services
9.1.3. Hardware
9.2. Market Analysis, Insights and Forecast - by Solution Type
9.2.1. Population Health Analytics
9.2.2. Patient Engagement Solutions
9.2.3. Care Coordination
9.2.4. Risk Stratification
9.2.5. Others
9.3. Market Analysis, Insights and Forecast - by Delivery Mode
9.3.1. On-Premise
9.3.2. Cloud-Based
9.3.3. Hybrid
9.4. Market Analysis, Insights and Forecast - by End-User
9.4.1. Healthcare Providers
9.4.2. Payers
9.4.3. Others
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Component
10.1.1. Software
10.1.2. Services
10.1.3. Hardware
10.2. Market Analysis, Insights and Forecast - by Solution Type
10.2.1. Population Health Analytics
10.2.2. Patient Engagement Solutions
10.2.3. Care Coordination
10.2.4. Risk Stratification
10.2.5. Others
10.3. Market Analysis, Insights and Forecast - by Delivery Mode
10.3.1. On-Premise
10.3.2. Cloud-Based
10.3.3. Hybrid
10.4. Market Analysis, Insights and Forecast - by End-User
10.4.1. Healthcare Providers
10.4.2. Payers
10.4.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Optum Inc.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Oracle Corporation (Cerner)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Allscripts Healthcare Solutions Inc.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. McKesson Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Health Catalyst Inc.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Koninklijke Philips N.V.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Siemens Healthineers AG
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. IBM Watson Health (Merative)
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Epic Systems Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. eClinicalWorks
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. NextGen Healthcare Inc.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Conifer Health Solutions LLC
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Persistent Systems
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. HEALWELL AI Inc.
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Population Health Management Software Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Population Health Management Software Revenue (Billion), by Component 2026 & 2034
Figure 3: North America Population Health Management Software Revenue Share (%), by Component 2026 & 2034
Figure 4: North America Population Health Management Software Revenue (Billion), by Solution Type 2026 & 2034
Figure 5: North America Population Health Management Software Revenue Share (%), by Solution Type 2026 & 2034
Figure 6: North America Population Health Management Software Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 7: North America Population Health Management Software Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 8: North America Population Health Management Software Revenue (Billion), by End-User 2026 & 2034
Figure 9: North America Population Health Management Software Revenue Share (%), by End-User 2026 & 2034
Figure 10: North America Population Health Management Software Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Population Health Management Software Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Population Health Management Software Revenue (Billion), by Component 2026 & 2034
Figure 13: Europe Population Health Management Software Revenue Share (%), by Component 2026 & 2034
Figure 14: Europe Population Health Management Software Revenue (Billion), by Solution Type 2026 & 2034
Figure 15: Europe Population Health Management Software Revenue Share (%), by Solution Type 2026 & 2034
Figure 16: Europe Population Health Management Software Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 17: Europe Population Health Management Software Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 18: Europe Population Health Management Software Revenue (Billion), by End-User 2026 & 2034
Figure 19: Europe Population Health Management Software Revenue Share (%), by End-User 2026 & 2034
Figure 20: Europe Population Health Management Software Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Population Health Management Software Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Population Health Management Software Revenue (Billion), by Component 2026 & 2034
Figure 23: Asia Pacific Population Health Management Software Revenue Share (%), by Component 2026 & 2034
Figure 24: Asia Pacific Population Health Management Software Revenue (Billion), by Solution Type 2026 & 2034
Figure 25: Asia Pacific Population Health Management Software Revenue Share (%), by Solution Type 2026 & 2034
Figure 26: Asia Pacific Population Health Management Software Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 27: Asia Pacific Population Health Management Software Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 28: Asia Pacific Population Health Management Software Revenue (Billion), by End-User 2026 & 2034
Figure 29: Asia Pacific Population Health Management Software Revenue Share (%), by End-User 2026 & 2034
Figure 30: Asia Pacific Population Health Management Software Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Population Health Management Software Revenue Share (%), by Country 2026 & 2034
Figure 32: Middle East & Africa Population Health Management Software Revenue (Billion), by Component 2026 & 2034
Figure 33: Middle East & Africa Population Health Management Software Revenue Share (%), by Component 2026 & 2034
Figure 34: Middle East & Africa Population Health Management Software Revenue (Billion), by Solution Type 2026 & 2034
Figure 35: Middle East & Africa Population Health Management Software Revenue Share (%), by Solution Type 2026 & 2034
Figure 36: Middle East & Africa Population Health Management Software Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 37: Middle East & Africa Population Health Management Software Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 38: Middle East & Africa Population Health Management Software Revenue (Billion), by End-User 2026 & 2034
Figure 39: Middle East & Africa Population Health Management Software Revenue Share (%), by End-User 2026 & 2034
Figure 40: Middle East & Africa Population Health Management Software Revenue (Billion), by Country 2026 & 2034
Figure 41: Middle East & Africa Population Health Management Software Revenue Share (%), by Country 2026 & 2034
Figure 42: South America Population Health Management Software Revenue (Billion), by Component 2026 & 2034
Figure 43: South America Population Health Management Software Revenue Share (%), by Component 2026 & 2034
Figure 44: South America Population Health Management Software Revenue (Billion), by Solution Type 2026 & 2034
Figure 45: South America Population Health Management Software Revenue Share (%), by Solution Type 2026 & 2034
Figure 46: South America Population Health Management Software Revenue (Billion), by Delivery Mode 2026 & 2034
Figure 47: South America Population Health Management Software Revenue Share (%), by Delivery Mode 2026 & 2034
Figure 48: South America Population Health Management Software Revenue (Billion), by End-User 2026 & 2034
Figure 49: South America Population Health Management Software Revenue Share (%), by End-User 2026 & 2034
Figure 50: South America Population Health Management Software Revenue (Billion), by Country 2026 & 2034
Figure 51: South America Population Health Management Software Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Population Health Management Software Revenue Billion Forecast, by Component 2020 & 2034
Table 2: Global Population Health Management Software Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 3: Global Population Health Management Software Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 4: Global Population Health Management Software Revenue Billion Forecast, by End-User 2020 & 2034
Table 5: Global Population Health Management Software Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Population Health Management Software Revenue Billion Forecast, by Component 2020 & 2034
Table 7: North America Population Health Management Software Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 8: North America Population Health Management Software Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 9: North America Population Health Management Software Revenue Billion Forecast, by End-User 2020 & 2034
Table 10: North America Population Health Management Software Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Population Health Management Software Revenue Billion Forecast, by Component 2020 & 2034
Table 15: Europe Population Health Management Software Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 16: Europe Population Health Management Software Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 17: Europe Population Health Management Software Revenue Billion Forecast, by End-User 2020 & 2034
Table 18: Europe Population Health Management Software Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Italy Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Spain Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Rest of Europe Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Asia Pacific Population Health Management Software Revenue Billion Forecast, by Component 2020 & 2034
Table 26: Asia Pacific Population Health Management Software Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 27: Asia Pacific Population Health Management Software Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 28: Asia Pacific Population Health Management Software Revenue Billion Forecast, by End-User 2020 & 2034
Table 29: Asia Pacific Population Health Management Software Revenue Billion Forecast, by Country 2020 & 2034
Table 30: China Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Japan Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: India Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Australia Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: South Korea Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: Rest of Asia Pacific Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Middle East & Africa Population Health Management Software Revenue Billion Forecast, by Component 2020 & 2034
Table 37: Middle East & Africa Population Health Management Software Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 38: Middle East & Africa Population Health Management Software Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 39: Middle East & Africa Population Health Management Software Revenue Billion Forecast, by End-User 2020 & 2034
Table 40: Middle East & Africa Population Health Management Software Revenue Billion Forecast, by Country 2020 & 2034
Table 41: UAE Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Saudi Arabia Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: South Africa Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: Rest of Middle East & Africa Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: South America Population Health Management Software Revenue Billion Forecast, by Component 2020 & 2034
Table 46: South America Population Health Management Software Revenue Billion Forecast, by Solution Type 2020 & 2034
Table 47: South America Population Health Management Software Revenue Billion Forecast, by Delivery Mode 2020 & 2034
Table 48: South America Population Health Management Software Revenue Billion Forecast, by End-User 2020 & 2034
Table 49: South America Population Health Management Software Revenue Billion Forecast, by Country 2020 & 2034
Table 50: Brazil Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Argentina Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Rest of South America Population Health Management Software Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the Population Health Management Software market size in 2026?
Our proprietary primary research estimates the global PHM software market at USD 40.36 billion in 2026, growing at a CAGR of 20.1% to reach USD 100.98 billion by 2031. Software represents 43.55% of the broader PHM market.
2Why is the Population Health Management Software market growing so rapidly?
Growth is driven by the shift to value-based care, escalating chronic disease burden, AI-powered predictive analytics, and the need for unified longitudinal patient records. AI alone adds an estimated 3.9 percentage points to market CAGR.
3Which region dominates the Population Health Management Software market?
North America captured 48.35% of global PHM software revenue in 2025, driven by CMS value-based care programs and commercial payer innovation. Asia-Pacific is the fastest-growing region at 18.96% CAGR.
4What is the fastest-growing segment in the PHM software market?
By end-user, the payers segment registered the fastest CAGR of 25.32% through 2031. By delivery mode, the hybrid model is growing at 21.74% CAGR, outpacing both pure cloud and on-premise deployment.
5Who are the leading companies in the Population Health Management Software market?
Leading vendors include Optum, Oracle (Cerner), Allscripts Healthcare Solutions, McKesson Corporation, Health Catalyst, and Philips Healthcare. The market exhibits medium concentration, with the top five vendors accounting for 45-50% of global revenue.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 462 primary interviews across 18 countries with senior executives, clinical informatics leaders, and IT procurement directors actively deploying or evaluating PHM software. This represents 70-80% of total research effort.
Interview targets included hospital CIOs and CMIOs, payer innovation leads, accountable care organization executive directors, health IT implementation consultants, and PHM platform product managers.
Structured questionnaires captured quantitative data on software spend, implementation timelines, vendor selection criteria, and outcome metrics (e.g., care gap closure rates, readmission reduction), supplemented by open-ended qualitative interviews on adoption barriers.
We verified respondent identities and organizational roles through LinkedIn and direct outreach, ensuring no duplicate participation and maintaining a response validity rate above 90%.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CIO / CTO
35%
Chief Medical Information Officer
25%
VP of Population Health
22%
Director of Care Management
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hospital and Health System CIOs
32%
Payer Innovation and Population Health Leads
24%
PHM Software Vendors and Product Managers
18%
ACO and Value-Based Care Executives
14%
Health IT Implementation Consultants
12%
Secondary Research & Industry Benchmarking
We triangulated primary findings against 20-30% secondary research from peer-reviewed literature, government publications, and non-profit technical standards bodies.
Financial databases used for vendor benchmarking included Bloomberg, Factiva, Hoovers, and PitchBook. Public company filings (10-K, 20-F) were analyzed for revenue segmentation and geographic mix.
Industry association publications from HIMSS and AMIA provided clinical informatics adoption benchmarks and workforce data. All secondary sources were evaluated for recency (published within 24 months) and methodological rigor.
Demand Modeling & Market Estimation
We built a bottom-up demand model starting with 4,800+ hospitals and 1,200+ payer organizations across 15 countries, segmented by bed count, value-based contract penetration, and existing PHM software adoption.
For each organization, we calculated PHM software spend as a function of per-member-per-month licensing fees, implementation services, and add-on module costs. The model was calibrated against disclosed vendor revenues, CMS cost report data on IT spending, and hospital IT budget benchmarks from HIMSS Analytics.
Specific quantitative metrics incorporated into the model included: (1) number of ACOs and covered beneficiaries (10.8 million under Medicare Shared Savings Program), (2) hospital readmission rates and avoidable utilization as proxies for PHM value, (3) PHM software as a percentage of total healthcare IT spend (estimated at 8-12% for value-based organizations), and (4) cloud vs. on-premise cost differentials validated through primary interviews.
A top-down methodology independently estimated the market using total healthcare IT spending (from OECD and CMS data) multiplied by PHM's share of that spending, cross-validated with bottom-up figures through multi-level data triangulation. A discrepancy of less than 5% between top-down and bottom-up estimates was required for final market sizing.
Data Accuracy & Quality Check
All market estimates carry a guaranteed data accuracy level of 85-90%, supported by standard error calculation, confidence interval reporting, and sensitivity analysis on key assumptions.
We conducted a three-tier validation process: (1) primary data cross-referenced against secondary benchmarks for coherence, (2) segment-level estimates reconciled to sum to the total market with variance analysis flagged for review, and (3) external expert review by three independent industry advisors who assessed methodology, assumptions, and findings.
Every report is updated to the date of purchase, incorporating the latest CMS rulemaking, vendor earnings releases, and primary interview data collected within 30 days of publication. Version control is maintained with full audit trails for all data points.
NAFLD market valued at USD 20.33 Billion in 2026, growing at 15.79% CAGR to USD 42.32 Billion by 2031, driven by Rezdiffra and GLP-1 therapies.
Nov 2026|187 pages
$2900.00
The global tele-ultrasound solution market is valued at USD 350 million in 2025 and is projected to reach USD 773 million by 2032, growing at a CAGR of 12.0%.
Nov 2026|251 pages
$2900.00
Transporter assay market to grow at 6.8% CAGR, driven by drug discovery, ADME screening, and membrane transporter research. Get the full analysis.