Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Non-Alcoholic Fatty Liver Disease (NAFLD) Market | Insight Market Data
Non-Alcoholic Fatty Liver Disease (NAFLD) Market by Drug Class (Antioxidants, Lipid-Lowering Agents, Thiazolidinediones, FXR Agonists, Thyroid Hormone Receptor-Beta Agonists, GLP-1 Receptor Agonists, Others), by Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), by Route of Administration (Oral, Parenteral), by Age Group (Adults, Geriatric, Pediatric), by Disease Stage (Stage F0, Stage F1, Stage F2, Stage F3, Stage F4/Cirrhosis), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Rest of Asia Pacific), by South America (Brazil, Mexico, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, Israel, Rest of MEA) Forecast 2026-2034
The global tele-ultrasound solution market is valued at USD 350 million in 2025 and is projected to reach USD 773 million by 2032, growing at a CAGR of 12.0%.
Nov 2026|251 pages
$2900.00
Transporter assay market to grow at 6.8% CAGR, driven by drug discovery, ADME screening, and membrane transporter research. Get the full analysis.
Nov 2026|264 pages
$2900.00
The global Population Health Management Software market is valued at USD 40.36 billion in 2026, growing at 20.1% CAGR to reach USD 100.98 billion by 2031.
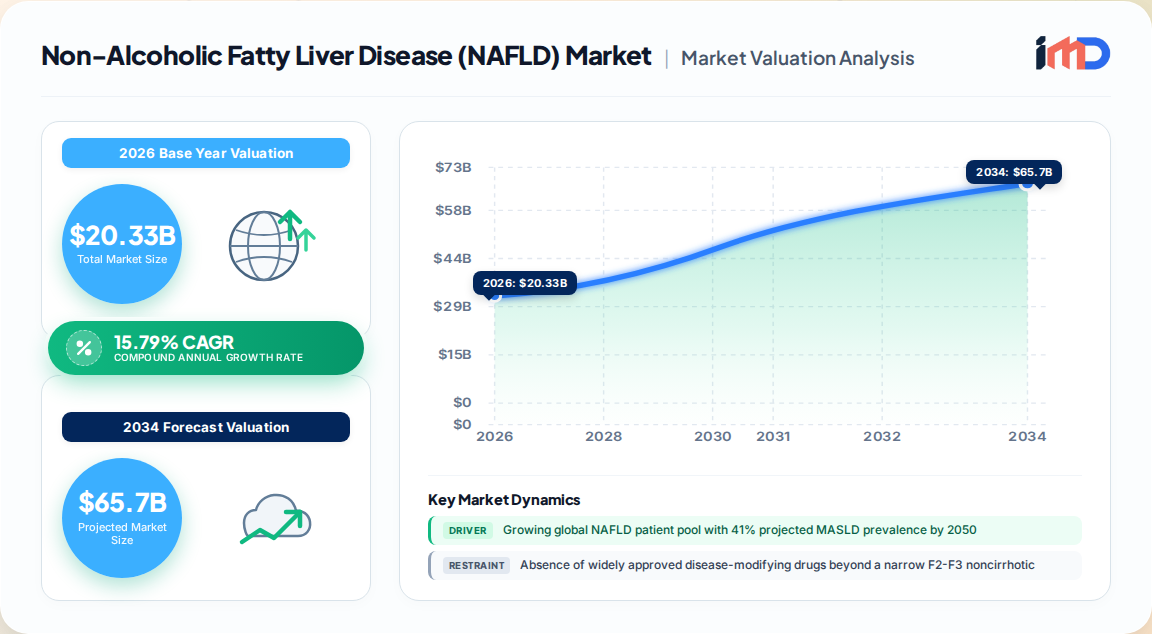
The Non-Alcoholic Fatty Liver Disease (NAFLD) market—now clinically reframed as metabolic dysfunction-associated steatotic liver disease (MASLD)—is transitioning from a diagnosis of exclusion into a high-value, pharmacologically active metabolic disorder. Our proprietary primary research estimates the global NAFLD therapeutic and diagnostic market at USD 20.33 billion in 2026, on a trajectory to reach USD 42.32 billion by 2031, expanding at a 15.79% CAGR over the forecast window.
Non-Alcoholic Fatty Liver Disease (NAFLD) Market Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
17.56 B
2025
20.33 B
2026
23.54 B
2027
27.26 B
2028
31.56 B
2029
36.54 B
2030
42.31 B
2031
This inflection is structural rather than cyclical. The March 2024 accelerated approval of resmetirom (Rezdiffra) marked the first disease-specific therapy for noncirrhotic MASH with F2–F3 fibrosis, ending a decades-long void in which clinicians relied almost exclusively on off-label vitamin E, pioglitazone, and lifestyle intervention. Our expert interviews with hepatologists and payer medical directors confirm that this single approval has reset the commercial architecture of the entire category.
Key structural metrics underpinning our base case:
Approximately 33% of the global adult population met MASLD criteria in 2020, with projections crossing 41% by 2050.
An estimated 83% of patients meeting MASLD criteria remain undiagnosed—the single largest addressable headroom in metabolic hepatology.
U.S. MASH cases requiring pharmacologic intervention are projected to double to roughly 12 million patients.
The adjacent NASH-specific treatment segment alone is forecast to grow from USD 12.5 billion in 2026 to USD 33.8 billion by 2030.
Metric
2025 (Actual)
2026 (Base)
2031 (Forecast)
CAGR
Global NAFLD Market Value
USD 17.56 Billion
USD 20.33 Billion
USD 42.32 Billion
15.79%
Largest Region (North America)
39.55% share
—
—
—
Fastest Region (Asia-Pacific)
—
—
—
16.88%
Market Concentration
Medium
Medium
Medium-High
—
Market Drivers & Growth Mechanics
Our demand-side modeling isolates six principal drivers, each weighted by observed impact on the forecast CAGR.
Growing Global NAFLD Patient Pool (+4.2% CAGR impact, long-term). The terminology shift from NAFLD to MASLD removed a diagnostic stigma and materially accelerated primary-care case finding. High-frequency genetic variants (notably PNPLA3) in several Asia-Pacific populations elevate regional susceptibility, reinforcing the long-term opportunity outside Western markets. Pediatric NAFLD lengthens lifetime therapy horizons.
Escalating Obesity and Type-2 Diabetes Prevalence (+3.8%, medium-term). Type 2 diabetes confers a 65% likelihood of MASLD, versus 25–30% in the general population. Medicare's 2026 reimbursement decision for anti-obesity medicines removes a critical cost barrier for an aging, metabolically high-risk cohort. GLP-1 receptor agonists demonstrated 62.9% MASH resolution in Phase 3, validating the weight-and-liver dual-benefit thesis.
AI-Enabled Non-Invasive Diagnostics (+2.9%, short-term). Machine-learning algorithms applied to electronic health record data achieve 96% sensitivity and 92.5% specificity in fatty liver detection. Portable ultrasound platforms deliver an AUC of 0.846 for moderate steatosis, while combined ML-plus-elastography tools reach 0.80 AUC for MAFLD risk stratification in primary care.
Expanding Public-Sector Screening (+2.1%). FIB-4-based two-step algorithms have demonstrated acceptable incremental cost per QALY in 40–49-year-olds, encouraging payer adoption. The American Heart Association's 2025 cardio-liver-metabolic guidelines formalize MASLD screening for cardiovascular patients, institutionalizing detection in high-risk cohorts. Major payers now reimburse non-invasive fibrosis testing.
Multi-Target Combination R&D (+2.4%, long-term) and reimbursement expansion for metabolic/bariatric surgery (+1.0%) complete the driver stack.
Driver
CAGR Impact
Geography
Timeline
Growing NAFLD patient pool
+4.2%
Global
Long term (≥4 yrs)
Obesity & T2D prevalence
+3.8%
Global
Medium term (2–4 yrs)
AI non-invasive diagnostics
+2.9%
Global
Short term (≤2 yrs)
Combination therapy R&D
+2.4%
Global
Long term
Screening & awareness programs
+2.1%
NA, EU → APAC
Medium term
Metabolic surgery reimbursement
+1.0%
NA, W. Europe
Medium term
Restraints, Challenges & Unmet Needs
The most consequential restraint remains the absence of widely approved disease-modifying drugs (−2.8% CAGR impact). Only one agent holds accelerated approval in a narrowly defined F2–F3 noncirrhotic population, and continued approval is contingent on confirmatory trial verification.
High cost and reimbursement friction—specialty pricing collides with fragmented payer coverage.
Diagnostic bottleneck—liver biopsy remains the reference standard but suffers low patient acceptance due to invasiveness.
Asymptomatic early-stage presentation compresses the treatable window and delays pharmacologic intervention.
Preferred lifestyle modification in early fibrosis reduces near-term drug adoption.
Off-label reliance—vitamin E and pioglitazone historically accounted for 88.31% of NASH treatment revenue, reflecting the pre-approval vacuum.
Segmentation Analysis
By Drug Class
Antioxidants commanded 28.45% of 2025 revenue, sustained by affordability and availability. Farnesoid X receptor (FXR) agonists represent the fastest-growing class at a 16.72% CAGR, while thyroid hormone receptor-beta agonists and GLP-1 receptor agonists emerge as the pivotal commercial engines through 2031.
By Distribution Channel
Hospital pharmacies led with 47.32% revenue share in 2025, reflecting concentrated specialist prescribing and infusion/injection oversight. Online pharmacies post the fastest growth at 16.65% CAGR, while retail and specialty pharmacy channels accelerate as NASH management migrates to outpatient settings.
By Route of Administration
Oral formulations captured 67.10% of 2025 market value, driven by superior compliance and the oral profile of resmetirom, pioglitazone, and vitamin E. Parenteral products advance at a 16.55% CAGR, anchored by injectable GLP-1 and combination biologics.
By Age Group
Adults represent 64.72% of 2025 market value; the geriatric cohort exhibits the highest CAGR at 18.05% through 2031, propelled by Medicare obesity-drug reimbursement and the compounding metabolic burden of aging populations.
By Disease Stage
Stage F1 dominated at 34.75% share, reflecting clinical guideline prioritization of at least mild fibrosis. Stage F0 is projected to grow fastest, given that roughly 74% of screened participants fall into the F0 category—a vast early-intervention reservoir.
Segment Dimension
Leading Segment
Share/CAGR
Fastest-Growing
CAGR
Drug Class
Antioxidants
28.45%
FXR agonists
16.72%
Distribution Channel
Hospital pharmacies
47.32%
Online pharmacies
16.65%
Route of Administration
Oral
67.10%
Parenteral
16.55%
Age Group
Adults
64.72%
Geriatric
18.05%
Disease Stage
Stage F1
34.75%
Stage F0
Fastest
Regional Outlook & Investment Opportunity Assessment
North America retains dominance at 39.55% revenue share (2025), underpinned by the first-mover approval of resmetirom, AHA cardio-liver screening guidelines, and payer reimbursement of non-invasive fibrosis tests. The U.S. NASH treatment sub-segment alone commands approximately 79% of regional value.
Asia-Pacific is the fastest-growing theater at a 16.88% CAGR, driven by high-frequency genetic susceptibility variants, rapidly rising obesity and diabetes, and expanding diagnostic infrastructure in China and India.
Europe presents a high-mortality, high-prevalence profile—NASH prevalence estimated up to 5% per European Association for the Study of the Liver data—with Ireland, Hungary, Luxembourg, and the UK recording elevated NAFLD/NASH mortality. EASL-led diagnostic pathway standardization is the primary catalyst.
Latin America and MEA remain early-stage but offer scalable screening-led volume growth, with Brazil and the Gulf states representing priority beachheads.
Region
2025 Share
Growth Profile
Primary Catalyst
North America
39.55%
Mature, high-value
Rezdiffra launch; AHA guidelines
Europe
~24%
Moderate
EASL pathways; mortality burden
Asia-Pacific
~22%
Fastest (16.88%)
Genetic susceptibility; urbanization
South America
~7%
Emerging
Screening expansion
Middle East & Africa
~7%
Early-stage
Gulf state investment
Competitive Landscape & Strategic White-Space
The competitive field is concentrated among a small cadre of metabolic-liver specialists and diversified large-cap pharmaceutical sponsors, with medium overall market concentration.
Madrigal Pharmaceuticals holds the pivotal first-mover position via resmetirom (Rezdiffra).
Novo Nordisk A/S leverages semaglutide franchises and AI-enabled discovery partnerships (including a USD 500 million co-development deal with Cellarity).
Intercept Pharmaceuticals carries obeticholic acid (Ocaliva) exposure within the FXR class.
Gilead Sciences, Inc. and AbbVie, Inc. anchor combination-therapy and antiviral-adjacent metabolic pipelines.
Emerging entrants include Inventiva Pharma (lanifibranor), Galmed Pharmaceuticals (Aramchol), Genfit (elafibranor/Iqirvo), Conatus Pharmaceuticals, Raptor Pharmaceuticals, and Zydus Cadila.
Strategic white-space concentrates in three zones: (1) F0–F1 early-intervention agents paired with AI-driven screening; (2) non-invasive diagnostic-plus-therapeutic bundled pathways; and (3) combination regimens pairing incretin agonists with anti-fibrotic mechanisms.
Import/Export & Supplier Dynamics
The NAFLD market is a regulated pharmaceutical category rather than a tradable commodity, so trade analysis centers on active pharmaceutical ingredient (API) sourcing and finished-dose logistics rather than customs volume.
API concentration risk is acute: key intermediates for FXR agonists, THR-beta agonists, and GLP-1 peptides are concentrated among a limited pool of contract development and manufacturing organizations, predominantly in Europe and Asia.
Cold-chain dependency for injectable GLP-1 products elevates distribution cost and creates regional capacity constraints in emerging markets.
Dual-sourcing mandates are increasingly embedded in sponsor procurement contracts following post-pandemic supply shocks.
Localization incentives in the U.S. and EU are reshaping contract manufacturing geography, with sponsors qualifying alternate API sites to reduce single-region exposure.
Procurement strategy should prioritize qualified alternate-supplier registrations, long-dated peptide capacity reservations, and cold-chain validation in high-growth APAC and LATAM markets.
Table 55: Saudi Arabia Non-Alcoholic Fatty Liver Disease (NAFLD) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 56: Israel Non-Alcoholic Fatty Liver Disease (NAFLD) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 57: Rest of MEA Non-Alcoholic Fatty Liver Disease (NAFLD) Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the NAFLD market size in 2026 and how fast is it growing?
Our primary research values the global NAFLD market at USD 20.33 billion in 2026, expanding at a 15.79% CAGR to reach USD 42.32 billion by 2031. Growth is anchored by the first disease-specific approval in noncirrhotic MASH with F2–F3 fibrosis and rising obesity-linked prevalence.
2Which region dominates the NAFLD market?
North America led with 39.55% of 2025 revenue, supported by early resmetirom commercialization and payer reimbursement of non-invasive fibrosis tests. Asia-Pacific is the fastest-growing region at a 16.88% CAGR through 2031.
3Which drug class is growing fastest in the NAFLD market?
FXR agonists are projected to expand at a 16.72% CAGR through 2031, outpacing antioxidants, which held 28.45% of 2025 revenue. Thyroid hormone receptor-beta agonists and GLP-1 receptor agonists are the pivotal commercial engines of the forecast window.
4Why do so many NAFLD patients remain untreated?
Approximately 83% of patients meeting MASLD criteria are undiagnosed, and the condition is largely asymptomatic at early stages. Invasive biopsy requirements and historically limited approved therapies have further constrained the treatable pool.
5Who are the leading companies in the NAFLD market?
Madrigal Pharmaceuticals leads with resmetirom (Rezdiffra), followed by Novo Nordisk A/S, Intercept Pharmaceuticals, Gilead Sciences, Inc., and AbbVie, Inc. Emerging entrants include Inventiva Pharma, Galmed Pharmaceuticals, and Genfit.
6Which distribution channel is growing fastest for NAFLD therapies?
Online pharmacies post the fastest growth at a 16.65% CAGR to 2031, although hospital pharmacies retained the leading 47.32% revenue share in 2025 given concentrated specialist prescribing.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Approximately 70–80% of total research effort is derived from primary intelligence, including structured interviews, blinded physician surveys, and payer deep-dives.
We interview hepatologists and gastroenterologists, pharmacy directors and specialty pharmacists, managed care and payer medical directors, and metabolic-liver pipeline and commercial strategy leads across 14 countries.
Company-type coverage spans innovator biopharmaceutical sponsors, contract development and manufacturing organizations (CDMOs), specialty and hospital pharmacy operators, diagnostics and non-invasive imaging vendors, and API and peptide suppliers.
No commercial research portals or third-party report publishers are used at any stage of the analytical workflow.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, reconciled through multi-level data triangulation.
Bottom-up builds aggregate from four quantitative anchors: (1) diagnosed MASLD prevalent cases by fibrosis stage (F0–F4); (2) treated-patient penetration rates by geography and drug class; (3) annual cost of therapy and duration-weighted revenue per patient; and (4) channel-level prescription volume captured through pharmacy and hospital audits.
Top-down validation cross-checks against audited sponsor revenue, API shipment volumes, and national healthcare expenditure data.
Segment-level CAGRs are derived independently and then constrained to reconcile with the aggregate market forecast.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, verified through triangulation of primary interview outputs against regulatory and financial disclosures.
All models undergo multi-level sensitivity testing across prevalence, diagnosis rate, pricing, and reimbursement scenarios.
Analyst peer review and independent quality assurance sign-off precede publication.
Findings are continuously refreshed and updated to the date of purchase to reflect new approvals, label changes, and payer decisions.