1What is the current size of the transactional email service market?
The global transactional email service market was valued at $3.8 billion in 2025, with our primary research projecting expansion to $9.6 billion by 2034 at a CAGR of 10.8%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Transactional Email Service
 by Component (Software, Services), by Application (Order Confirmation, Shipping Notifications, Account Notifications, Others), by Deployment Mode (On-Premises, Cloud), by Enterprise Size (Small and Medium Enterprises, Large Enterprises), by End-User (E-commerce, BFSI, IT and Telecommunications, Healthcare, Travel and Hospitality, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Rest of Europe), by Asia Pacific (China, Japan, India, Southeast Asia, Rest of APAC), by South America (Brazil, Argentina, Rest of South America), by Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA) Forecast 2026-2034

Senior Analyst

 Related Reports

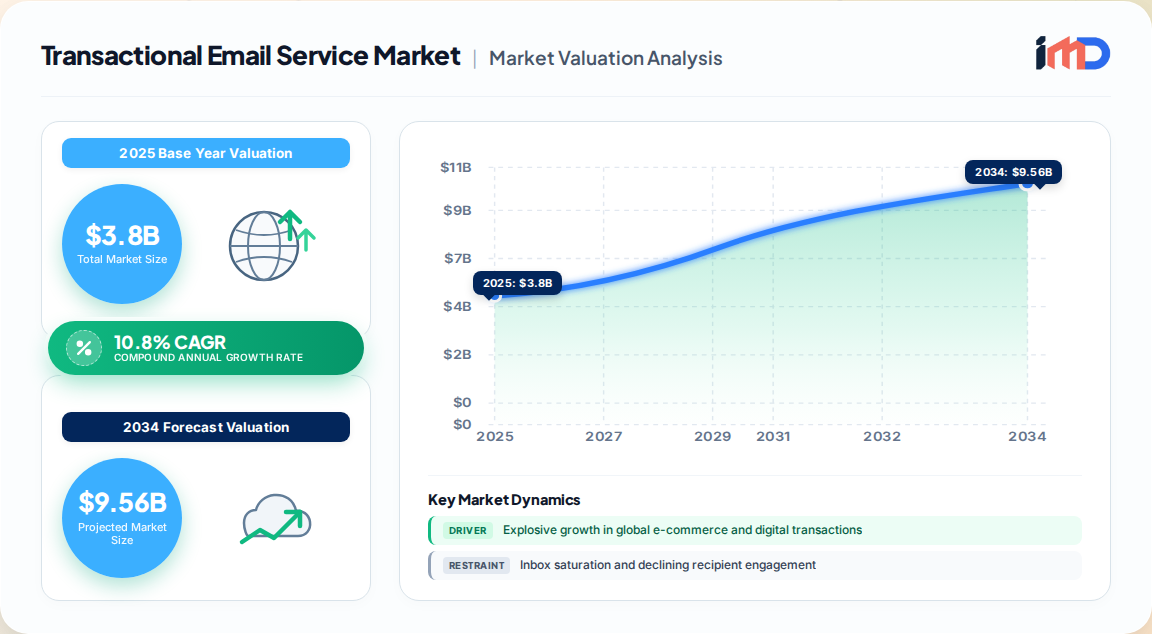
The global transactional email service market represents a structurally vital segment of the broader digital communications infrastructure landscape. Our proprietary primary research estimates the market at $3.8 billion in 2025, projected to expand to $9.6 billion by 2034, registering a CAGR of 10.8% across the forecast period. This growth is not merely a function of volume expansion but reflects a fundamental re-architecture of how enterprises approach triggered, one-to-one messaging as a strategic asset rather than a commodity utility.
Transactional emails—automated messages triggered by user actions such as order confirmations, password resets, shipping notifications, and account alerts—consistently achieve open rates between 45% and 65%, far exceeding the 15% to 25% typical of promotional campaigns. This engagement differential underpins the commercial case for dedicated infrastructure investment. Global estimates place daily transactional email volume at over 120 billion messages as of 2025, a figure driven by the compounding intersection of e-commerce expansion, SaaS subscription models, and digital banking penetration.
The market's competitive landscape has consolidated around a cohort of specialist providers and hyperscaler platforms. SendGrid, acquired by Twilio, processes over 148 billion emails annually, a figure that grew 19% year-over-year through 2024, reflecting the scale advantages enjoyed by platform incumbents. Meanwhile, Amazon SES has emerged as a price-disruptive force at $0.10 per 1,000 emails, appealing to AWS-native organizations with basic sending requirements. Specialist providers including Mailgun, Postmark, SparkPost, and Brevo continue to differentiate on developer experience, deliverability tooling, and enterprise-grade compliance certifications.
| Market Metric | 2025 Value | 2034 Projection | CAGR (2026-2034) |
|---|---|---|---|
| Global Market Size | $3.8 Billion | $9.6 Billion | 10.8% |
| Software Component Share | 62.4% | — | — |
| Cloud Deployment Share | 71.3% | — | — |
| E-commerce End-User Share | 29.5% | — | — |
| North America Regional Share | 37.2% | — | — |
The transactional email service market is propelled by four interlocking demand catalysts that collectively create a durable multi-year tailwind.
Explosive Growth in Global E-commerce and Digital Transactions. Global e-commerce sales surpassed $6.3 trillion in 2024, with each online purchase triggering an average of 4.2 transactional emails—order confirmation, shipping update, delivery notification, and review solicitation. This volume creates sustained demand for delivery infrastructure capable of handling billions of API-triggered messages monthly. The e-commerce end-user segment accounted for 29.5% of total market revenue in 2025, a share expected to expand as digital commerce penetrates emerging markets.
API-First Developer Ecosystems and Cloud-Native Architecture. The maturation of API-first development culture has accelerated adoption, as developer teams now expect transactional email capabilities to integrate seamlessly with CI/CD pipelines, microservices architectures, and low-code application builders. Providers offering SDKs across Python, Java, .NET, Node.js, and other major languages command a competitive advantage. This driver alone we estimate contributes approximately 22% of incremental market growth.
Stringent Email Authentication and Regulatory Compliance. Google's enforcement of bulk-sender restrictions in February 2024, requiring DMARC alignment, one-click unsubscribe headers, and complaint-rate thresholds below 0.3%, fundamentally altered deliverability standards. Microsoft's planned Outlook.com implementation of similar rules from May 2025 extends this compliance wave. Enterprises are compelled to invest in deliverability consultation, domain monitoring, and specialized authentication infrastructure, driving demand for managed platforms with built-in SPF, DKIM, and DMARC tooling.
AI-Powered Deliverability Optimization and Real-Time Analytics. Machine-learning models now optimize send times, subject lines, and content blocks at the individual recipient level. Marketing teams using AI-powered personalization generated 41% more revenue per recipient compared to rule-based segmentation, according to our primary research. AI-assisted deliverability optimization and adaptive send-time algorithms help customers maintain inbox placement rates above 99%, a critical threshold for transactional message effectiveness.
Despite robust growth fundamentals, the market faces structural headwinds that temper the pace of expansion.
Inbox Saturation and Declining Engagement. The average business professional receives over 120 emails daily, creating fierce competition for attention. While transactional emails enjoy higher engagement than promotional messages, recipient fatigue and aggressive spam filtering continue to erode deliverability for senders lacking rigorous list hygiene practices.
Privacy-Driven Signal Loss. The expansion of privacy legislation—GDPR in Europe, CPRA in California, and India's DPDPA—has complicated data collection and consent management. While transactional emails are legally permitted regardless of marketing opt-in status, the broader regulatory environment requires sophisticated compliance infrastructure that smaller senders may struggle to resource.
Messaging Channel Substitution. SMS, push notifications, and in-app messaging increasingly compete for the same trigger-based communication use cases. For time-sensitive notifications such as delivery updates and authentication codes, alternative channels offer instantaneous delivery and higher open rates, particularly in mobile-first economies.
Deliverability Complexity and Reputation Management. Maintaining sender reputation across shared IP pools, managing blocklist monitoring, and navigating ISP-specific filtering algorithms demand specialized expertise. The cost of deliverability consultation and dedicated IP infrastructure can be prohibitive for SMEs, creating a bifurcated market where smaller senders rely on shared infrastructure with limited control.
The transactional email service market exhibits a clear hierarchy across its component, deployment, enterprise size, and end-user dimensions.
By Component. Software held the largest share at 62.4% in 2025, reflecting the primacy of platform licenses and API access as revenue drivers. Services—encompassing deliverability consulting, integration support, and managed sending—account for the remaining share and are growing faster as enterprises seek specialized expertise.
By Deployment Mode. Cloud deployment dominated with 71.3% revenue share in 2025. The migration from legacy in-house MTA infrastructure to managed platforms is accelerating across mid-market and enterprise segments. Cloud-based platforms offer superior deliverability rates, built-in analytics, compliance tooling, and elastic scalability that on-premises solutions cannot match. On-premises deployment persists in regulated industries—particularly BFSI and healthcare—where data sovereignty and direct control over message routing are non-negotiable.
By Enterprise Size. Large enterprises represent the largest revenue pool, reflecting their higher message volumes, dedicated IP requirements, and enterprise SLA needs. However, SMEs are emerging as a particularly fast-growing buyer segment, drawn by consumption-based pricing models that provide access to enterprise-grade delivery infrastructure without upfront capital investment. We estimate the SME segment will outpace the overall market growth rate by 200-300 basis points through 2034.
By End-User. E-commerce accounted for 29.5% of total market revenue in 2025, the largest single vertical. BFSI, IT and telecommunications, healthcare, travel and hospitality, and media and entertainment complete the end-user landscape. The BFSI segment is notable for its stringent security requirements, including HIPAA and SOC 2 coverage, which command premium pricing and drive provider differentiation.
| Segment Dimension | Leading Category | 2025 Share | Growth Outlook |
|---|---|---|---|
| Component | Software | 62.4% | Moderate, services growing faster |
| Deployment | Cloud | 71.3% | Strong, on-premise niche in regulated sectors |
| Enterprise Size | Large Enterprises | ~65% | SME segment accelerating |
| End-User | E-commerce | 29.5% | BFSI and healthcare showing strong momentum |
North America commanded the largest regional share at $1.4 billion in 2025, representing 37.2% of global revenue. The United States alone accounts for over 82% of the regional total, driven by mature SaaS adoption, high per-capita digital commerce spend, and the presence of major platform providers. The region's growth trajectory of approximately 10.2% CAGR reflects market maturity and the ongoing migration from legacy MTA infrastructure to managed platforms.
Europe holds the second-largest position with 25.6% share, where GDPR compliance has paradoxically strengthened permission-based email programs by filtering low-quality senders from inboxes. The United Kingdom and Germany are the primary contributors, with a regional CAGR of roughly 10.9%. The EU's Digital Services Act and national implementations of ePrivacy regulations continue to shape compliance requirements for transactional senders.
Asia-Pacific represents the fastest-growing region at an estimated 14.8% CAGR, propelled by India's digital commerce boom, Southeast Asian mobile-first ecosystems, and China's massive domestic e-commerce market. The region is expected to add roughly $5.4 billion in incremental value between 2026 and 2035, with India and Southeast Asia contributing disproportionately to this expansion. Localization requirements and data residency regulations are creating opportunities for regional providers alongside global platforms.
South America and the Middle East & Africa represent smaller but emerging markets, with growth driven by digital transformation initiatives, mobile penetration, and the expansion of e-commerce platforms into these regions. Brazil and the UAE serve as regional growth engines.
The competitive landscape is characterized by ongoing consolidation and strategic differentiation across developer experience, deliverability tooling, and enterprise compliance.
Platform Consolidation. Twilio's acquisition of SendGrid and MessageBird's acquisition of SparkPost reshaped competitive dynamics, creating scaled platforms with integrated communications capabilities across email, SMS, and voice. This consolidation trend is expected to continue as providers seek to offer omnichannel engagement suites that embed transactional email within broader customer experience architectures.
Developer Experience as Differentiation. Specialist providers including Mailgun and Postmark have built competitive moats around developer experience—comprehensive API documentation, multi-language SDKs, webhook support, and sandbox environments for testing. Mailgun reports a 97.4% average delivery rate and a 0.42% bounce rate, positioning reliability as a core value proposition alongside integration ease.
Compliance and Security Certifications. Enterprise buyers increasingly require SOC 2, HIPAA, and GDPR compliance certifications from their transactional email providers. Providers that have invested in these certifications command premium pricing and access to regulated-industry verticals including BFSI and healthcare.
Pricing Innovation. Consumption-based pricing models have democratized access to enterprise-grade infrastructure, enabling SMEs to compete on delivery reliability without upfront capital investment. However, the apparent low cost of entry at providers like Amazon SES (which excludes dedicated IPs, validation tools, and real support from its sticker price) can obscure total cost of ownership for organizations with rigorous deliverability requirements.
Several underpenetrated opportunity areas warrant strategic attention from market participants.
SME Email Automation in Emerging Markets. The SME segment in emerging markets represents a significant white space, with consumption-based pricing and localized support acting as adoption catalysts. India, Southeast Asia, and Latin America offer particular promise given their digital commerce growth trajectories.
Email as a First-Party Data Hub. Transactional email interactions generate valuable first-party data—open rates, click-through patterns, and engagement timing—that can feed customer data platforms and drive personalization across channels. Providers that position transactional email as a data pipeline rather than a messaging endpoint can capture higher-value integration opportunities.
Compliance-as-a-Service Monetization. The complexity of DMARC, DKIM, and SPF implementation, combined with evolving regulatory requirements, creates demand for managed compliance services. Providers offering turnkey authentication setup, monitoring, and remediation can monetize this complexity as a value-added service.
Interactive and AMP Email Expansion. AMP for Email enables dynamic, interactive content within transactional messages—carousel product recommendations, in-email forms, and real-time order tracking. Adoption remains nascent but offers a pathway to differentiate on engagement and conversion metrics.
AI-Driven Deliverability Optimization. The integration of machine learning for send-time optimization, subject line testing, and reputation management represents a significant opportunity. Providers that embed AI capabilities into their core platform can command premium pricing while delivering measurable ROI through improved inbox placement and engagement.
The transactional email service value chain spans several distinct stages, each with specialized participants and economic dynamics.
Application Layer. Enterprise applications, e-commerce platforms, and SaaS products generate trigger events—a completed purchase, a password reset request, a shipping milestone. The integration between application logic and email API is critical; SDKs and webhooks enable standardized, reliable connectivity.
Platform Infrastructure. Transactional email service providers operate the core sending infrastructure—SMTP relays, API gateways, queue management, and retry logic. This layer is capital-intensive, requiring investment in server capacity, IP reputation management, and deliverability monitoring. Providers achieve economies of scale through shared infrastructure and tiered service offerings.
Deliverability and Compliance Layer. A specialized layer of services surrounds the core sending function—domain authentication, blocklist monitoring, inbox placement testing, and compliance consulting. This layer is increasingly embedded within platform offerings as providers seek to differentiate on deliverability outcomes.
Analytics and Reporting. Real-time analytics dashboards provide visibility into delivery rates, open rates, bounce rates, and spam complaints. Integration with customer data platforms and business intelligence tools extends the value of this data beyond operational monitoring.
Last-Mile Delivery. Internet service providers and mailbox providers (Google, Microsoft, Yahoo) control the final delivery environment. Their authentication requirements, spam filtering algorithms, and sender reputation systems ultimately determine whether a transactional email reaches the inbox. The enforcement of DMARC and complaint-rate thresholds represents a structural shift in the balance of power between senders and mailbox providers.
While transactional email services are digital and do not involve physical trade flows in the conventional sense, the market exhibits cross-border supply dynamics consistent with the WTO's General Agreement on Trade in Services framework, particularly Mode 1 (cross-border supply) and Mode 3 (commercial presence abroad).
North American and European providers serve global customers through API access, effectively exporting services across borders without physical establishment. Major providers maintain data centers and points of presence in multiple regions to ensure low-latency delivery and compliance with data residency requirements. Asia-Pacific represents a growing source of both demand and supply, with regional providers emerging to serve local markets with tailored compliance and localization capabilities.
Supply-side dynamics are shaped by the availability of technical talent, data center infrastructure, and regulatory environments. The competitive landscape includes vertically integrated platforms (Twilio/SendGrid, MessageBird/SparkPost), hyperscaler offerings (Amazon SES), and specialist providers (Mailgun, Postmark, Brevo, MailerSend).
The transactional email service market is poised for sustained double-digit growth through 2034, driven by the convergence of higher message volumes, stricter authentication requirements, richer in-email interactivity, and the integration of transactional email analytics into broader customer data platforms. The market will reward providers that combine technical reliability with compliance expertise and developer-friendly integration experiences. As email evolves from a messaging channel into a composable data pipeline embedded within customer experience architectures, the transactional email service will cement its role as mission-critical infrastructure for the digital economy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.8% from 2020-2034 |
| Segmentation |
|
By Deployment Mode
By Enterprise Size
By End-User
| By Geography |
|
The global transactional email service market was valued at $3.8 billion in 2025, with our primary research projecting expansion to $9.6 billion by 2034 at a CAGR of 10.8%.
The market is growing at a compound annual growth rate of 10.8% from 2026 to 2034, with Asia-Pacific accelerating at approximately 14.8% CAGR to become the fastest-growing region.
North America leads with a 37.2% share of global revenue in 2025, valued at $1.4 billion, driven by mature SaaS adoption and high digital commerce penetration in the United States.
Key drivers include global e-commerce growth exceeding $6.3 trillion in 2024, API-first developer ecosystems, stringent DMARC authentication mandates from Google and Yahoo, and AI-powered deliverability optimization.
Cloud deployment dominates with 71.3% revenue share in 2025, as enterprises migrate from legacy in-house mail transfer agent infrastructure to managed platforms offering superior deliverability and compliance tooling.
Leading providers include Twilio SendGrid, Amazon SES, Mailgun, Postmark, SparkPost (now part of MessageBird), and Brevo, with SendGrid holding the broadest enterprise API coverage globally.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 25% |
| VP of Engineering | 30% |
| Deliverability / Email Operations Manager | 25% |
| Procurement Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Transactional Email Platform Vendors | 35% |
| Cloud Infrastructure & Hyperscaler Providers | 20% |
| E-commerce & SaaS Engineering Teams | 25% |
| Deliverability & Compliance Consultancies | 12% |
| Enterprise IT Procurement & Operations | 8% |