1What is the size of the strategy consulting service market?
The global strategy consulting service market is estimated at USD 77.53 billion in 2026 and is forecast to reach USD 95.49 billion by 2031, growing at a 4.25% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Strategy Consulting Service
 by Service Type (Corporate Strategy, Business-Model Transformation, Functional Strategy, Digital Strategy, Mergers & Acquisitions, Economic Policy, Organizational Strategy), by Organization Size (Large Enterprises, Small & Medium Enterprises), by Engagement Model (Project-Based Advisory, Retained Advisory, Outcome-Based Consulting), by End-User Industry (Financial Services, Life Sciences & Healthcare, IT & Telecommunications, Government, Energy, Retail, Manufacturing, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, Australia, South Korea), by South America (Brazil, Argentina), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034

Senior Analyst

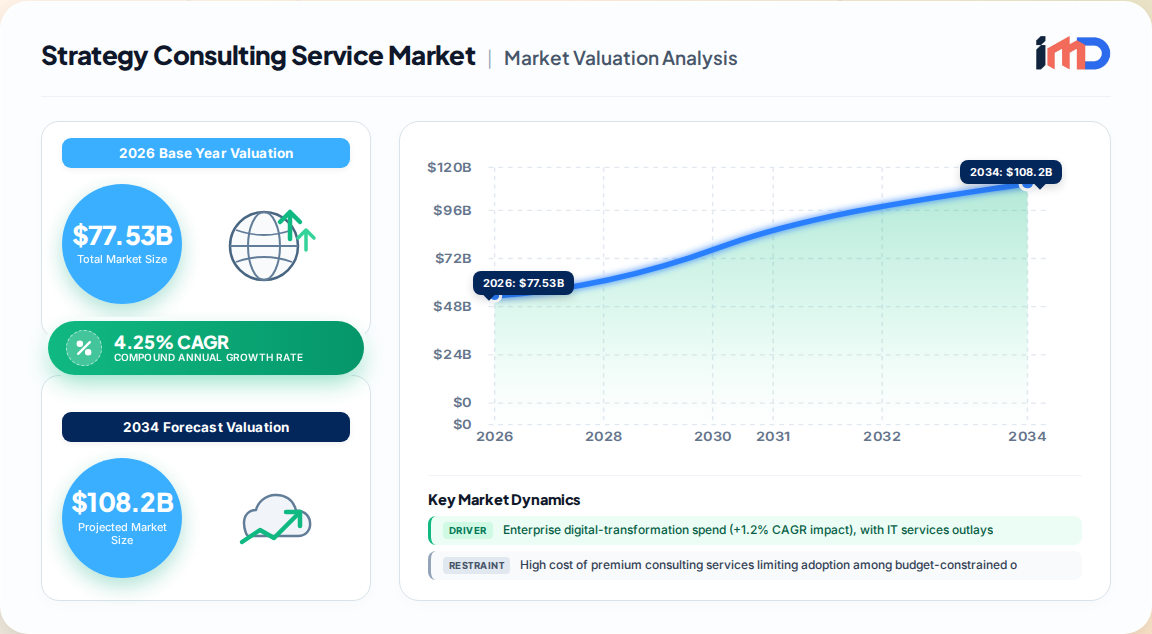
The global strategy consulting service market is entering a decisive phase of reinvention. Our proprietary primary research estimates the market at USD 77.53 billion in 2026, expanding at a 4.25% CAGR to reach USD 95.49 billion by 2031. This measured growth trajectory reflects a sector transitioning from a period of digital-transformation-fueled expansion into a more complex operating environment defined by AI diffusion, regulatory intensity, and shifting client expectations.
Unlike the broad management consulting industry—which our estimates place at approximately USD 420 billion in the US alone—strategy consulting remains a high-value, premium-advisory segment. It is increasingly characterized by outcome-based engagements, platform-enabled delivery, and the reinvention of the traditional leverage model. Competitive intensity has never been higher, with boutique specialists, independent freelancers, and AI-powered advisory platforms eroding the historic dominance of large incumbents.
| Market Metric | 2025 (Actual) | 2026 (Estimated) | 2031 (Forecast) |
|---|---|---|---|
| Market Value | USD 74.37 Billion | USD 77.53 Billion | USD 95.49 Billion |
| CAGR (2026–2031) | — | — | 4.25% |
| Largest Region | North America (36.55% share) | — | — |
| Fastest-Growing Region | — | — | Asia-Pacific (4.82% CAGR) |
The strategy consulting market is being reshaped by six principal demand drivers, each exerting a quantifiable impact on the sector's growth trajectory.
Principal Growth Drivers
Principal Restraints
The strategy consulting service market exhibits clear structural preferences across its four primary segmentation axes.
| Segment Dimension | Leading Segment (2025 Share) | Fastest-Growing Segment (CAGR to 2031) |
|---|---|---|
| By Service Type | Functional Strategy (38.22%) | Digital Strategy (4.67%) |
| By Organization Size | Large Enterprises (62.32%) | Small Enterprises (5.28%) |
| By Engagement Model | Project-Based Advisory (54.05%) | Outcome-Based Consulting (5.15%) |
| By End-User Industry | Financial Services (29.63%) | Healthcare & Life Sciences |
Service Type Dynamics
Functional strategy consulting—encompassing corporate strategy, organizational design, and business-model transformation—remains the anchor of the market. However, digital strategy consulting is growing at the fastest rate as clients prioritize AI roadmaps, data monetization, and platform economics. M&A advisory and economic policy consulting round out the service portfolio, with M&A benefiting from the robust transaction pipeline.
Engagement Model Shift
The migration from project-based advisory toward outcome-based consulting is one of the most consequential structural trends in the sector. Clients increasingly demand fee structures aligned with measurable business results, pressuring firms to build implementation capabilities and risk-sharing frameworks. Retained advisory models remain relevant for long-term transformation programs but are growing more slowly.
End-User Industry Deep Dive
Financial services leads with 29.63% revenue share, driven by regulatory complexity and digital modernization. Healthcare and life sciences is the fastest-growing vertical, propelled by value-based-care frameworks, FDA digital-therapeutics guidelines, and clinical-operations transformation. IT and telecommunications, retail, manufacturing, and energy round out the demand base, with energy clients increasingly focused on decarbonization and ESG reporting compliance.
The geographic distribution of strategy consulting demand reflects both the maturity of Western markets and the rapid institutional development of emerging economies.
| Region | 2025 Share | Growth Outlook | Key Demand Themes |
|---|---|---|---|
| North America | 36.55% | Moderate | Digital transformation, M&A integration, AI governance |
| Europe | ~27.5% | Moderate | Regulatory compliance (EU AI Act, DORA), sustainability |
| Asia-Pacific | ~24.0% | 4.82% CAGR (fastest) | Business-model transformation, SME advisory, digital commerce |
| South America | ~6.5% | Emerging | Globalization, market entry, regulatory navigation |
| Middle East & Africa | ~5.4% | Emerging | Sovereign transformation programs, infrastructure strategy |
North America remains the largest and most sophisticated market, with US consultancies pivoting aggressively toward business strategy and financial management advisory as clients hedge against tariff uncertainty and inflationary pressure. Asia-Pacific is the growth engine, driven by rising foreign investment, SME digital adoption, and government-led transformation initiatives. Europe presents a compliance-heavy demand profile, with the EU's regulatory agenda generating multi-year advisory mandates. Eurostat data underscore the region's trade intensity: EU exports of professional and management consulting services reached €127.3 billion in 2023, up 6.6% year-over-year, with the United States and United Kingdom as dominant partners.
The strategy consulting market is characterized by low concentration, with no single firm holding dominant share. The competitive field comprises three distinct strata:
Recent Strategic Developments
Strategy consulting is a highly tradable service, and trade data provide a critical lens on regional competitiveness. Official Eurostat figures reveal that EU imports of professional and management consulting services reached €164.3 billion in 2023, up 8.2% year-over-year, producing a €37 billion trade deficit. This structural deficit—persistent since 2010—highlights the dominance of US and UK firms in high-value advisory exports.
The United States accounted for 29.7% of EU exports and 37.2% of EU imports of these services, while the UK contributed 22.8% and 25.1%, respectively. These flows underscore the transatlantic concentration of strategic advisory expertise.
Supply-Side Risks
Mitigation Strategies
Leading firms are responding by investing in proprietary AI platforms, building nearshore delivery centers, and restructuring talent pyramids to emphasize senior expertise and implementation capability.
Our primary research identifies several underpenetrated opportunity areas for strategy consulting providers:
The strategy consulting value chain comprises five stages: demand origination (client relationship and diagnostics), research and synthesis (data gathering and analysis), strategy formulation (frameworks and recommendations), implementation support (change management and capability building), and outcome measurement (ROI tracking and continuous improvement).
Procurement Trends
Sourcing Considerations
Organizations are advised to evaluate consulting partners on four dimensions: sector depth, implementation track record, technology enablement, and commercial flexibility. Multi-sourcing—combining Tier One firms for transformation programs with boutiques for specialized work—is an increasingly common procurement strategy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.25% from 2020-2034 |
| Segmentation |
|
By Organization Size
By Engagement Model
By End-User Industry
| By Geography |
|
The global strategy consulting service market is estimated at USD 77.53 billion in 2026 and is forecast to reach USD 95.49 billion by 2031, growing at a 4.25% CAGR.
North America holds the largest share at 36.55% in 2025, driven by strong digital transformation spending and a robust M&A pipeline. Asia-Pacific is the fastest-growing region at 4.82% CAGR.
Enterprise digital-transformation spending (+1.2% CAGR impact), a rising global M&A pipeline nearing USD 3.5 trillion (+0.8%), and regulatory compliance proliferation (+0.6%) are the primary growth drivers.
Functional strategy consulting held 38.22% of the market in 2025. Digital strategy consulting is the fastest-growing service type at 4.67% CAGR through 2031.
Key players include Deloitte, Accenture, Ernst & Young, KPMG, PwC, McKinsey & Company, Boston Consulting Group, Bain & Company, and Oliver Wyman.
Outcome-based consulting is expanding at 5.15% CAGR as clients demand fee structures aligned with measurable business results, pressuring firms to build implementation capabilities and risk-sharing frameworks.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Strategy Officer | 30% |
| Procurement Director | 25% |
| Practice Leader / Managing Partner | 25% |
| Digital Transformation Head | 20% |
| Company Type | Representation (%) |
|---|---|
| Global Multi-Service Consulting Firms | 35% |
| Specialized Strategy Boutiques | 25% |
| Independent & Fractional Consultants | 15% |
| AI-Enabled Advisory Platforms | 10% |
| Corporate In-House Strategy Teams (Buyers) | 15% |
 Related Reports
