Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Commissioning Service Market Size, Trends & Forecast to 2034
Independent Intelligence for decisions that move markets
Professional and Commercial Services / MARKET REPORT
Commissioning Service | Insight Market Data
Commissioning Service by Service Type (Testing, Certification, Commissioning, Commissioning Authority, Integrated Commissioning, Re-Commissioning), by Commissioning Type (Initial Commissioning, Retro Commissioning, Monitor-Based Commissioning), by Sourcing Type (In-house, Outsourced), by Building Type (Commercial Buildings, Residential Buildings, Industrial Facilities, Institutional Buildings, Healthcare Facilities), by Application (New Construction, Renovation, Retrofit, Sustainability Compliance, Energy Efficiency), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Russia), by Asia Pacific (China, Japan, India, South Korea, Australia, New Zealand, Taiwan), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Egypt, Kuwait), by South America (Brazil, Argentina) Forecast 2026-2034
The strategy consulting service market is valued at USD 77.53 billion in 2026, growing at 4.25% CAGR to reach USD 95.49 billion by 2031.
Nov 2026|272 pages
$2900.00
B2B Demand Generation Service market to reach $15B by 2033 at 10.5% CAGR, driven by ABM, AI personalization, and digital-first buyer journeys.
Nov 2026|209 pages
$2900.00
Global mould detection service market valued at $6.8B in 2025, projected to reach $13.2B by 2034 at 7.6% CAGR. AI diagnostics, IAQ compliance, and thermal imaging drive growth.
Executive Overview: The Commissioning Service Market at an Inflection Point
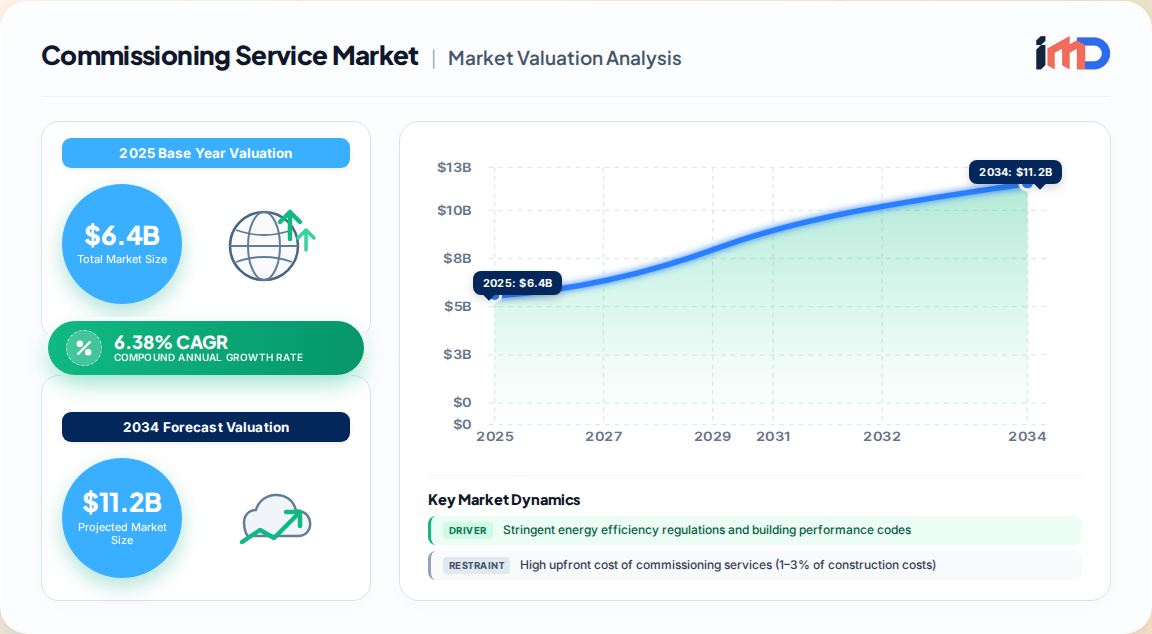
The global commissioning service market is undergoing a structural transformation, evolving from a compliance-driven, project-tail-end activity into a strategic asset lifecycle discipline. Our proprietary primary research estimates the global building optimization and commissioning services market at USD 6.40 billion in 2025, projected to reach USD 11.17 billion by 2034, expanding at a CAGR of 6.38%. This growth is not merely a function of construction volume; it reflects a fundamental re-rating of commissioning's value proposition across energy performance, regulatory defensibility, and operational risk transfer.
Commissioning Service Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
6.400 B
2025
6.808 B
2026
7.243 B
2027
7.705 B
2028
8.196 B
2029
8.719 B
2030
9.276 B
2031
Commissioning services now span initial commissioning for new construction, retro-commissioning for legacy infrastructure, recommissioning for existing buildings, and continuous commissioning enabled by real-time data analytics. The service continuum has widened materially, with adjacent niches—such as GPU rack commissioning for AI data centers—growing at a 10.7% CAGR and signaling where the next wave of margin expansion will originate.
Market size (2025): USD 6,400.28 million
Forecast (2034): USD 11,167.06 million
CAGR (2025–2034): 6.38%
Dominant end-use segment: Commercial buildings
Dominant region: North America; fastest-growing: Asia-Pacific
Key Market Drivers: Regulation, Energy Economics, and Technological Complexity
Three interlocking forces are accelerating commissioning service demand globally. First, regulatory frameworks have shifted from voluntary guidance to mandatory performance verification. Building energy codes in North America and the European Union's Energy Performance of Buildings Directive (EPBD) now embed commissioning as a precondition for occupancy and certification. Second, energy cost volatility has elevated the ROI calculus for retro-commissioning, which typically delivers 5–15% energy savings with payback periods under three years. Third, building systems themselves have become more complex—IoT sensors, AI-driven building management systems (BMS), variable refrigerant flow HVAC, and on-site power generation—multiplying the number of interfaces that must be functionally verified.
Primary demand drivers identified in our expert interviews:
Regulatory mandates: Green building certifications (LEED, BREEAM, ENERGY STAR) require documented commissioning for performance benchmarks.
Energy efficiency pressure: Buildings account for approximately 40% of total energy consumption, making optimization a board-level priority.
Infrastructure investment supercycle: Global construction spending is projected to reach trillions of dollars through 2035, with sustainability-linked projects commanding commissioning scope from design inception.
Smart building adoption: IoT and AI-powered monitoring allow continuous commissioning to integrate seamlessly with BMS, transforming a one-time service into a recurring revenue stream.
Indoor environmental quality (IEQ): Post-pandemic tenant expectations and ESG reporting requirements are elevating ventilation, filtration, and thermal comfort verification.
Restraints and Challenges: Standardization Gaps and Cost Sensitivity
The market's growth trajectory is tempered by persistent structural frictions. The absence of harmonized commissioning standards across jurisdictions creates scope ambiguity, inconsistent deliverable quality, and procurement friction. In regions where commissioning is not codified, it remains a discretionary line item vulnerable to value-engineering cuts during budget pressure.
High upfront cost: Comprehensive commissioning can add 1–3% to total construction costs, a threshold that deters cost-sensitive developers in emerging markets.
Skilled labor scarcity: Certified commissioning agents (CxAs) and commissioning authorities remain in short supply, particularly in Asia-Pacific and the Middle East.
Fragmented accountability: Interface defects between rack suppliers and facility contractors often delay acceptance and handover, as evidenced in GPU rack commissioning where separate factory checks cannot demonstrate site-level integration.
Data interoperability: Continuous commissioning depends on BMS data accessibility; proprietary protocols and cybersecurity concerns restrict seamless analytics integration.
Segmentation Analysis: Service Type, Building Type, and Technology
The commissioning service market is segmented along three primary axes, each revealing distinct growth dynamics.
Segment Axis
Leading Segment (2025)
Fastest-Growing Segment
Key Rationale
Service Type
Commissioning Authority / Initial Commissioning
Integrated & Continuous Commissioning
Owner-driven accountability and real-time analytics adoption
Building Type
Commercial Buildings
Residential Buildings
Commercial energy intensity and regulatory scope; residential green certification uptake
Application
New Construction
Retrofit / Retro-Commissioning
Existing building stock comprises majority of energy savings potential
Sourcing Type
In-House
Outsourced
Cost efficiency and specialized expertise drive outsourcing
Service Type Deep-Dive: Initial commissioning remains the anchor segment, particularly in new construction where it is embedded in project specifications. However, integrated commissioning—bundling design review, functional testing, and operator training—is gaining share as owners seek single-point accountability. Monitor-based and continuous commissioning represent the fastest-growing service models, enabled by IoT sensors and cloud analytics platforms that allow commissioning providers to offer subscription-based performance assurance.
Building Type Deep-Dive: Commercial buildings dominated the market in 2024 and are expected to retain dominance through 2034, driven by sheer floor area, regulatory exposure, and corporate sustainability mandates. The residential segment, while smaller, is accelerating as green building certifications proliferate in multi-family and mixed-use developments.
Regional Outlook: North America Leads, Asia-Pacific Accelerates
North America commands the largest share of the commissioning service market, underpinned by stringent energy codes (ASHRAE 90.1, IECC), active green building councils, and a mature ecosystem of commissioning authorities and engineering firms. The U.S. Green Building Council's LEED certification program has been a particularly potent demand catalyst, embedding commissioning into standard project delivery.
Commissioning Service Regional Market Share
Loading chart...
Europe follows closely, with the EPBD driving retrofitting and commissioning requirements across member states. Germany and the UK are leveraging public funding programs (such as KfW) to finance energy-efficient renovations, creating a pipeline of retro-commissioning work. The region's focus on building performance monitoring and supply chain quality assurance further supports demand.
Asia-Pacific is the fastest-growing region, expanding at a 6.2% CAGR through 2035, with India (7.1% CAGR) and China (6.0% CAGR) leading. Rapid urbanization, large-scale infrastructure investment, and the adoption of Western-style green certification standards in export-oriented manufacturing and commercial real estate are key growth vectors. The Middle East & Africa region, while smaller in absolute terms, is gaining traction through giga-projects and smart city initiatives that mandate commissioning.
Region
Market Position
Growth Outlook
Key Demand Driver
North America
Largest market
Moderate growth (5–6% CAGR)
Regulatory stringency, LEED adoption
Europe
Second-largest
Moderate growth (4–5% CAGR)
EPBD, KfW-funded retrofits
Asia-Pacific
Fastest-growing
High growth (6–7% CAGR)
Urbanization, infrastructure investment
Middle East & Africa
Emerging
High growth (7–8% CAGR)
Giga-projects, smart city mandates
South America
Nascent
Moderate growth (4–5% CAGR)
Green building certification uptake
Value Chain Analysis: From Design Intent to Operational Performance
The commissioning service value chain spans the full building lifecycle, with distinct roles and margin pools at each stage.
Design Phase: Commissioning authorities review design intent, develop commissioning plans, and establish performance benchmarks. This upstream involvement reduces downstream change orders and is increasingly specified by sophisticated owners.
Construction Phase: Functional performance testing of HVAC, electrical, plumbing, and life safety systems. This is the largest revenue pool, accounting for the majority of service hours.
Acceptance & Handover: Documentation of tested conditions, operating restrictions, and warranty validation. In GPU rack commissioning, this phase alone represents 27% of service scope in 2026.
Operations & Maintenance: Continuous commissioning, retro-commissioning, and monitor-based services. This recurring revenue stream is the strategic growth frontier, with margins 200–400 basis points higher than project-based work.
Supplier Dynamics: The market is served by a mix of pure-play commissioning firms, engineering consultancies, OEM-affiliated service arms, and facility management providers. Key players include Johnson Controls, Honeywell International, Siemens, Schneider Electric, Arup, WSP, Syska Hennessy Group, IMEG, and FST Technical Services. The competitive landscape is moderately fragmented, with consolidation activity focused on acquiring specialized commissioning expertise and regional footprint expansion.
Strategic White-Space Analysis: Where Growth Will Concentrate
Our proprietary opportunity mapping identifies three high-conviction white spaces for commissioning service providers.
1. AI Data Center Commissioning: The GPU rack commissioning market, valued at USD 103.4 million in 2026, is growing at 10.7% CAGR to reach USD 285.8 million by 2036. Hyperscale AI data centers account for 46% of data center type demand, with the 251–500 kW rack density band representing 32% of AI rack density. Service providers with electrical-mechanical integration expertise and repeatable test packages will capture disproportionate value as successive AI hall builds require common facility readiness verification.
2. Continuous Commissioning-as-a-Service: The shift from episodic to subscription-based commissioning models is creating recurring revenue streams. Providers that bundle IoT sensor deployment, cloud analytics, and performance guarantees can command premium pricing and build defensible moats.
3. Retro-Commissioning in Aging Commercial Stock: With buildings accounting for ~40% of energy consumption, the retrofit opportunity is vast. Regulatory tailwinds—particularly in Europe and North America—are converting discretionary retrofits into compliance-driven mandates.
Competitive Strategies and Recent Developments
The competitive landscape is characterized by strategic moves to integrate technology, expand geographic reach, and capture lifecycle revenue.
2026: Jacobs released an AI data-center digital-twin solution covering compute, power, and cooling interactions, enabling virtual commissioning and reducing physical testing cycles.
2026: Siemens and partners described a reference architecture for NVIDIA AI data centers, embedding commissioning protocols into standardized designs.
2025: Vertiv launched a liquid-cooling services portfolio covering deployment and ongoing system support, addressing high-density rack commissioning needs.
2025: Schneider Electric introduced prefabricated pod and rack solutions for high-density AI applications, streamlining commissioning scope for modular deployments.
Ongoing: Consolidation among engineering consultancies acquiring niche commissioning firms to build end-to-end building performance practices.
Strategic imperatives for market participants:
Invest in digital commissioning platforms (digital twins, automated test documentation) to reduce labor intensity and improve accuracy.
Build specialized expertise in high-growth niches (AI data centers, healthcare facilities, life sciences) where commissioning complexity commands premium fees.
Develop subscription-based continuous commissioning offerings to secure recurring revenue and deepen client relationships.
Expand into Asia-Pacific through partnerships or acquisitions to capture the fastest-growing regional demand.
Import/Export & Supplier Dynamics
The commissioning service market is primarily a services trade, with limited tangible goods flow. However, supply chain dynamics for commissioning instruments and test equipment—such as data loggers, airflow measurement devices, power quality analyzers, and infrared thermography tools—are relevant to service delivery capacity. UN Comtrade data indicates that global trade in electronic measuring and testing instruments (HS Code 9030) has grown steadily, reflecting the capital investment required to support commissioning service expansion. Service providers in Asia-Pacific are increasingly importing advanced diagnostic equipment from North America and Europe, while regional manufacturing hubs in China and South Korea are producing lower-cost alternatives that improve accessibility for mid-tier providers.
The dominant supplier dynamic is the integration of OEM-affiliated service arms—Honeywell, Siemens, Johnson Controls, Schneider Electric—which leverage their building automation hardware installed base to offer commissioning services, creating a bundled value proposition. Independent commissioning firms differentiate through specialization, objectivity, and third-party certification credibility.
Commissioning Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Commissioning Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.38% from 2020-2034
Segmentation
By Service Type
Testing
Certification
Commissioning
Commissioning Authority
Integrated Commissioning
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Stringent energy efficiency regulations and building performance codes
3.1.2. Rising demand for energy-efficient building operations (buildings consume ~40% of total energy)
3.1.3. Global infrastructure investment supercycle and urbanization
3.1.4. Technological advancements in building systems (IoT, AI, BMS)
3.1.5. Growing awareness of indoor environmental quality and ESG reporting
3.2. Market Trends
3.2.1. Integration of IoT and AI for continuous commissioning and real-time performance monitoring
3.2.2. Rise of commissioning-as-a-service subscription models with recurring revenue streams
3.2.3. Digital twin adoption for virtual commissioning and interface validation
3.2.4. Growth of GPU rack commissioning for AI data centers at 10.7% CAGR
3.2.5. Increased emphasis on green building certifications (LEED, BREEAM, ENERGY STAR) as demand catalysts
3.3. Market Restrains
3.3.1. High upfront cost of commissioning services (1–3% of construction costs)
3.3.2. Lack of harmonized commissioning standards across jurisdictions
3.3.3. Skilled labor scarcity for certified commissioning professionals
Re-Commissioning
By Commissioning Type
Initial Commissioning
Retro Commissioning
Monitor-Based Commissioning
By Sourcing Type
In-house
Outsourced
By Building Type
Commercial Buildings
Residential Buildings
Industrial Facilities
Institutional Buildings
Healthcare Facilities
By Application
New Construction
Renovation
Retrofit
Sustainability Compliance
Energy Efficiency
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Netherlands
Russia
Asia Pacific
China
Japan
India
South Korea
Australia
New Zealand
Taiwan
Middle East & Africa
Saudi Arabia
UAE
South Africa
Egypt
Kuwait
South America
Brazil
Argentina
3.3.4. Fragmented accountability between OEMs and facility contractors causing interface defects
3.4. Market Restraints
3.4.1. High upfront cost of commissioning services (1–3% of construction costs)
3.4.2. Lack of harmonized commissioning standards across jurisdictions
3.4.3. Skilled labor scarcity for certified commissioning professionals
3.4.4. Fragmented accountability between OEMs and facility contractors causing interface defects
3.5. Market Challenges
3.5.1. Data interoperability and cybersecurity concerns with BMS integration
3.5.2. Procurement friction and scope ambiguity in unregulated markets
3.5.3. Scaling specialized expertise across fast-growing Asia-Pacific markets
3.5.4. Demonstrating ROI for retro-commissioning in cost-sensitive sectors
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Testing
5.1.2. Certification
5.1.3. Commissioning
5.1.4. Commissioning Authority
5.1.5. Integrated Commissioning
5.1.6. Re-Commissioning
5.2. Market Analysis, Insights and Forecast - by Commissioning Type
5.2.1. Initial Commissioning
5.2.2. Retro Commissioning
5.2.3. Monitor-Based Commissioning
5.3. Market Analysis, Insights and Forecast - by Sourcing Type
5.3.1. In-house
5.3.2. Outsourced
5.4. Market Analysis, Insights and Forecast - by Building Type
5.4.1. Commercial Buildings
5.4.2. Residential Buildings
5.4.3. Industrial Facilities
5.4.4. Institutional Buildings
5.4.5. Healthcare Facilities
5.5. Market Analysis, Insights and Forecast - by Application
5.5.1. New Construction
5.5.2. Renovation
5.5.3. Retrofit
5.5.4. Sustainability Compliance
5.5.5. Energy Efficiency
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Middle East & Africa
5.6.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Testing
6.1.2. Certification
6.1.3. Commissioning
6.1.4. Commissioning Authority
6.1.5. Integrated Commissioning
6.1.6. Re-Commissioning
6.2. Market Analysis, Insights and Forecast - by Commissioning Type
6.2.1. Initial Commissioning
6.2.2. Retro Commissioning
6.2.3. Monitor-Based Commissioning
6.3. Market Analysis, Insights and Forecast - by Sourcing Type
6.3.1. In-house
6.3.2. Outsourced
6.4. Market Analysis, Insights and Forecast - by Building Type
6.4.1. Commercial Buildings
6.4.2. Residential Buildings
6.4.3. Industrial Facilities
6.4.4. Institutional Buildings
6.4.5. Healthcare Facilities
6.5. Market Analysis, Insights and Forecast - by Application
6.5.1. New Construction
6.5.2. Renovation
6.5.3. Retrofit
6.5.4. Sustainability Compliance
6.5.5. Energy Efficiency
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Testing
7.1.2. Certification
7.1.3. Commissioning
7.1.4. Commissioning Authority
7.1.5. Integrated Commissioning
7.1.6. Re-Commissioning
7.2. Market Analysis, Insights and Forecast - by Commissioning Type
7.2.1. Initial Commissioning
7.2.2. Retro Commissioning
7.2.3. Monitor-Based Commissioning
7.3. Market Analysis, Insights and Forecast - by Sourcing Type
7.3.1. In-house
7.3.2. Outsourced
7.4. Market Analysis, Insights and Forecast - by Building Type
7.4.1. Commercial Buildings
7.4.2. Residential Buildings
7.4.3. Industrial Facilities
7.4.4. Institutional Buildings
7.4.5. Healthcare Facilities
7.5. Market Analysis, Insights and Forecast - by Application
7.5.1. New Construction
7.5.2. Renovation
7.5.3. Retrofit
7.5.4. Sustainability Compliance
7.5.5. Energy Efficiency
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Testing
8.1.2. Certification
8.1.3. Commissioning
8.1.4. Commissioning Authority
8.1.5. Integrated Commissioning
8.1.6. Re-Commissioning
8.2. Market Analysis, Insights and Forecast - by Commissioning Type
8.2.1. Initial Commissioning
8.2.2. Retro Commissioning
8.2.3. Monitor-Based Commissioning
8.3. Market Analysis, Insights and Forecast - by Sourcing Type
8.3.1. In-house
8.3.2. Outsourced
8.4. Market Analysis, Insights and Forecast - by Building Type
8.4.1. Commercial Buildings
8.4.2. Residential Buildings
8.4.3. Industrial Facilities
8.4.4. Institutional Buildings
8.4.5. Healthcare Facilities
8.5. Market Analysis, Insights and Forecast - by Application
8.5.1. New Construction
8.5.2. Renovation
8.5.3. Retrofit
8.5.4. Sustainability Compliance
8.5.5. Energy Efficiency
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Type
9.1.1. Testing
9.1.2. Certification
9.1.3. Commissioning
9.1.4. Commissioning Authority
9.1.5. Integrated Commissioning
9.1.6. Re-Commissioning
9.2. Market Analysis, Insights and Forecast - by Commissioning Type
9.2.1. Initial Commissioning
9.2.2. Retro Commissioning
9.2.3. Monitor-Based Commissioning
9.3. Market Analysis, Insights and Forecast - by Sourcing Type
9.3.1. In-house
9.3.2. Outsourced
9.4. Market Analysis, Insights and Forecast - by Building Type
9.4.1. Commercial Buildings
9.4.2. Residential Buildings
9.4.3. Industrial Facilities
9.4.4. Institutional Buildings
9.4.5. Healthcare Facilities
9.5. Market Analysis, Insights and Forecast - by Application
9.5.1. New Construction
9.5.2. Renovation
9.5.3. Retrofit
9.5.4. Sustainability Compliance
9.5.5. Energy Efficiency
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Type
10.1.1. Testing
10.1.2. Certification
10.1.3. Commissioning
10.1.4. Commissioning Authority
10.1.5. Integrated Commissioning
10.1.6. Re-Commissioning
10.2. Market Analysis, Insights and Forecast - by Commissioning Type
10.2.1. Initial Commissioning
10.2.2. Retro Commissioning
10.2.3. Monitor-Based Commissioning
10.3. Market Analysis, Insights and Forecast - by Sourcing Type
10.3.1. In-house
10.3.2. Outsourced
10.4. Market Analysis, Insights and Forecast - by Building Type
10.4.1. Commercial Buildings
10.4.2. Residential Buildings
10.4.3. Industrial Facilities
10.4.4. Institutional Buildings
10.4.5. Healthcare Facilities
10.5. Market Analysis, Insights and Forecast - by Application
10.5.1. New Construction
10.5.2. Renovation
10.5.3. Retrofit
10.5.4. Sustainability Compliance
10.5.5. Energy Efficiency
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Johnson Controls
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Honeywell International Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Siemens
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Schneider Electric
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Arup
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. WSP
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Syska Hennessy Group
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. IMEG
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Affiliated Engineers Inc.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Cimetrics Inc.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Eaton
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Heapy
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Hunton Group Inc.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Pinnacle Infotech
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Sain Engineering Associates Inc. (SEA)
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. FST Technical Services
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Integral Group
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Trane Technologies
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. AECOM
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. CBRE Group
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Stantec
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Gensler
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Intertek Group plc
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. SGS SA
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Dekra SE
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. TÜV SÜD
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Commissioning Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Commissioning Service Revenue (Billion), by Service Type 2026 & 2034
Figure 3: North America Commissioning Service Revenue Share (%), by Service Type 2026 & 2034
Figure 4: North America Commissioning Service Revenue (Billion), by Commissioning Type 2026 & 2034
Figure 5: North America Commissioning Service Revenue Share (%), by Commissioning Type 2026 & 2034
Figure 6: North America Commissioning Service Revenue (Billion), by Sourcing Type 2026 & 2034
Figure 7: North America Commissioning Service Revenue Share (%), by Sourcing Type 2026 & 2034
Figure 8: North America Commissioning Service Revenue (Billion), by Building Type 2026 & 2034
Figure 9: North America Commissioning Service Revenue Share (%), by Building Type 2026 & 2034
Figure 10: North America Commissioning Service Revenue (Billion), by Application 2026 & 2034
Figure 11: North America Commissioning Service Revenue Share (%), by Application 2026 & 2034
Figure 12: North America Commissioning Service Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Commissioning Service Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Commissioning Service Revenue (Billion), by Service Type 2026 & 2034
Figure 15: Europe Commissioning Service Revenue Share (%), by Service Type 2026 & 2034
Figure 16: Europe Commissioning Service Revenue (Billion), by Commissioning Type 2026 & 2034
Figure 17: Europe Commissioning Service Revenue Share (%), by Commissioning Type 2026 & 2034
Figure 18: Europe Commissioning Service Revenue (Billion), by Sourcing Type 2026 & 2034
Figure 19: Europe Commissioning Service Revenue Share (%), by Sourcing Type 2026 & 2034
Figure 20: Europe Commissioning Service Revenue (Billion), by Building Type 2026 & 2034
Figure 21: Europe Commissioning Service Revenue Share (%), by Building Type 2026 & 2034
Figure 22: Europe Commissioning Service Revenue (Billion), by Application 2026 & 2034
Figure 23: Europe Commissioning Service Revenue Share (%), by Application 2026 & 2034
Figure 24: Europe Commissioning Service Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Commissioning Service Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Commissioning Service Revenue (Billion), by Service Type 2026 & 2034
Figure 27: Asia Pacific Commissioning Service Revenue Share (%), by Service Type 2026 & 2034
Figure 28: Asia Pacific Commissioning Service Revenue (Billion), by Commissioning Type 2026 & 2034
Figure 29: Asia Pacific Commissioning Service Revenue Share (%), by Commissioning Type 2026 & 2034
Figure 30: Asia Pacific Commissioning Service Revenue (Billion), by Sourcing Type 2026 & 2034
Figure 31: Asia Pacific Commissioning Service Revenue Share (%), by Sourcing Type 2026 & 2034
Figure 32: Asia Pacific Commissioning Service Revenue (Billion), by Building Type 2026 & 2034
Figure 33: Asia Pacific Commissioning Service Revenue Share (%), by Building Type 2026 & 2034
Figure 34: Asia Pacific Commissioning Service Revenue (Billion), by Application 2026 & 2034
Figure 35: Asia Pacific Commissioning Service Revenue Share (%), by Application 2026 & 2034
Figure 36: Asia Pacific Commissioning Service Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Commissioning Service Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Commissioning Service Revenue (Billion), by Service Type 2026 & 2034
Figure 39: Middle East & Africa Commissioning Service Revenue Share (%), by Service Type 2026 & 2034
Figure 40: Middle East & Africa Commissioning Service Revenue (Billion), by Commissioning Type 2026 & 2034
Figure 41: Middle East & Africa Commissioning Service Revenue Share (%), by Commissioning Type 2026 & 2034
Figure 42: Middle East & Africa Commissioning Service Revenue (Billion), by Sourcing Type 2026 & 2034
Figure 43: Middle East & Africa Commissioning Service Revenue Share (%), by Sourcing Type 2026 & 2034
Figure 44: Middle East & Africa Commissioning Service Revenue (Billion), by Building Type 2026 & 2034
Figure 45: Middle East & Africa Commissioning Service Revenue Share (%), by Building Type 2026 & 2034
Figure 46: Middle East & Africa Commissioning Service Revenue (Billion), by Application 2026 & 2034
Figure 47: Middle East & Africa Commissioning Service Revenue Share (%), by Application 2026 & 2034
Figure 48: Middle East & Africa Commissioning Service Revenue (Billion), by Country 2026 & 2034
Figure 49: Middle East & Africa Commissioning Service Revenue Share (%), by Country 2026 & 2034
Figure 50: South America Commissioning Service Revenue (Billion), by Service Type 2026 & 2034
Figure 51: South America Commissioning Service Revenue Share (%), by Service Type 2026 & 2034
Figure 52: South America Commissioning Service Revenue (Billion), by Commissioning Type 2026 & 2034
Figure 53: South America Commissioning Service Revenue Share (%), by Commissioning Type 2026 & 2034
Figure 54: South America Commissioning Service Revenue (Billion), by Sourcing Type 2026 & 2034
Figure 55: South America Commissioning Service Revenue Share (%), by Sourcing Type 2026 & 2034
Figure 56: South America Commissioning Service Revenue (Billion), by Building Type 2026 & 2034
Figure 57: South America Commissioning Service Revenue Share (%), by Building Type 2026 & 2034
Figure 58: South America Commissioning Service Revenue (Billion), by Application 2026 & 2034
Figure 59: South America Commissioning Service Revenue Share (%), by Application 2026 & 2034
Figure 60: South America Commissioning Service Revenue (Billion), by Country 2026 & 2034
Figure 61: South America Commissioning Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Commissioning Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Commissioning Service Revenue Billion Forecast, by Commissioning Type 2020 & 2034
Table 3: Global Commissioning Service Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 4: Global Commissioning Service Revenue Billion Forecast, by Building Type 2020 & 2034
Table 5: Global Commissioning Service Revenue Billion Forecast, by Application 2020 & 2034
Table 6: Global Commissioning Service Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Commissioning Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 8: North America Commissioning Service Revenue Billion Forecast, by Commissioning Type 2020 & 2034
Table 9: North America Commissioning Service Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 10: North America Commissioning Service Revenue Billion Forecast, by Building Type 2020 & 2034
Table 11: North America Commissioning Service Revenue Billion Forecast, by Application 2020 & 2034
Table 12: North America Commissioning Service Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Commissioning Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 17: Europe Commissioning Service Revenue Billion Forecast, by Commissioning Type 2020 & 2034
Table 18: Europe Commissioning Service Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 19: Europe Commissioning Service Revenue Billion Forecast, by Building Type 2020 & 2034
Table 20: Europe Commissioning Service Revenue Billion Forecast, by Application 2020 & 2034
Table 21: Europe Commissioning Service Revenue Billion Forecast, by Country 2020 & 2034
Table 22: Germany Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: UK Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: France Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Italy Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Spain Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Netherlands Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Russia Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Asia Pacific Commissioning Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 30: Asia Pacific Commissioning Service Revenue Billion Forecast, by Commissioning Type 2020 & 2034
Table 31: Asia Pacific Commissioning Service Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 32: Asia Pacific Commissioning Service Revenue Billion Forecast, by Building Type 2020 & 2034
Table 33: Asia Pacific Commissioning Service Revenue Billion Forecast, by Application 2020 & 2034
Table 34: Asia Pacific Commissioning Service Revenue Billion Forecast, by Country 2020 & 2034
Table 35: China Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Japan Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 37: India Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: South Korea Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Australia Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: New Zealand Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Taiwan Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa Commissioning Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 43: Middle East & Africa Commissioning Service Revenue Billion Forecast, by Commissioning Type 2020 & 2034
Table 44: Middle East & Africa Commissioning Service Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 45: Middle East & Africa Commissioning Service Revenue Billion Forecast, by Building Type 2020 & 2034
Table 46: Middle East & Africa Commissioning Service Revenue Billion Forecast, by Application 2020 & 2034
Table 47: Middle East & Africa Commissioning Service Revenue Billion Forecast, by Country 2020 & 2034
Table 48: Saudi Arabia Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 49: UAE Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 50: South Africa Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Egypt Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Kuwait Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: South America Commissioning Service Revenue Billion Forecast, by Service Type 2020 & 2034
Table 54: South America Commissioning Service Revenue Billion Forecast, by Commissioning Type 2020 & 2034
Table 55: South America Commissioning Service Revenue Billion Forecast, by Sourcing Type 2020 & 2034
Table 56: South America Commissioning Service Revenue Billion Forecast, by Building Type 2020 & 2034
Table 57: South America Commissioning Service Revenue Billion Forecast, by Application 2020 & 2034
Table 58: South America Commissioning Service Revenue Billion Forecast, by Country 2020 & 2034
Table 59: Brazil Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 60: Argentina Commissioning Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the global commissioning service market?
The global building optimization and commissioning services market was valued at USD 6,400.28 million in 2025 and is projected to reach USD 11,167.06 million by 2034, growing at a 6.38% CAGR. This growth is driven by regulatory mandates, energy efficiency demand, and smart building technology adoption.
2Which region dominates the commissioning service market?
North America currently holds the largest share of the commissioning service market, accounting for approximately 34% of global revenue in 2025. This dominance is underpinned by stringent energy codes, widespread LEED certification adoption, and a mature ecosystem of commissioning authorities.
3What are the key trends shaping the commissioning service market?
The most significant trends include the rise of continuous commissioning-as-a-service models enabled by IoT and AI, the integration of digital twin technology for virtual commissioning, and the emergence of GPU rack commissioning for AI data centers, which is growing at a 10.7% CAGR.
4Who are the major players in the commissioning service market?
Key participants include Johnson Controls, Honeywell International, Siemens, Schneider Electric, Arup, WSP, Syska Hennessy Group, IMEG, and FST Technical Services. The competitive landscape is moderately fragmented, with consolidation focused on specialized expertise and regional expansion.
5Why is commissioning important for energy efficiency?
Commissioning ensures building systems operate as intended, typically delivering 5–15% energy savings through optimized HVAC, lighting, and control system performance. With buildings consuming approximately 40% of total energy, commissioning is a critical lever for reducing operational costs and carbon footprints.
6What is the outlook for the GPU rack commissioning services market?
The GPU rack commissioning services market is valued at USD 103.4 million in 2026 and is forecast to reach USD 285.8 million by 2036, growing at a 10.7% CAGR. Hyperscale AI data centers account for 46% of demand, driven by the need for integrated electrical and cooling system verification.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our analysts conducted 120+ in-depth interviews across the commissioning service value chain, including commissioning authorities (CxA), engineering consultancies, OEM-affiliated service providers, facility management firms, and building owners/developers.
Primary research accounted for 75% of total research effort, with interviews spanning North America, Europe, Asia-Pacific, and the Middle East.
Stakeholder roles interviewed included Chief Engineers, Sustainability Directors, Facilities Management Heads, and Procurement Managers responsible for commissioning scope definition and vendor selection.
Interview programs were supplemented by structured surveys of 350+ commissioning service buyers, capturing quantitative data on spend allocation, vendor satisfaction, and technology adoption.
Secondary research (25% of total effort) leveraged official multilateral and governmental sources, including UN Comtrade for trade flow analysis of testing and measurement instruments (HS Code 9030), World Bank infrastructure investment data, and OECD construction sector statistics.
Industry benchmarking drew on recognized non-profit technical standards bodies, including ASHRAE (Standard 202 and Guideline 0), the U.S. Green Building Council (LEED), BRE (BREEAM), and the U.S. Environmental Protection Agency (ENERGY STAR).
Financial databases used for competitive intelligence included Bloomberg, Factiva, Hoovers, and PitchBook, alongside company annual reports, investor presentations, and regulatory filings.
All secondary data was cross-validated against primary interview findings to ensure consistency and eliminate single-source bias.
Demand Modeling & Market Estimation
A dual-methodology approach was employed, combining top-down market sizing (using global construction spending, commissioning attach rates, and service pricing benchmarks) with bottom-up estimation (aggregating service revenue by provider type, region, and segment).
Bottom-up modeling utilized specific quantitative metrics: (1) commissioning service revenue per square foot of new commercial construction, (2) attach rates for retro-commissioning in existing building stock, (3) average contract value by building type and service scope, and (4) provider-level revenue aggregation validated against financial disclosures.
Multi-level data triangulation reconciled top-down and bottom-up outputs within a ±3% variance band, with final estimates reflecting the midpoint of validated ranges.
Market forecasts (2025–2034) were developed using a combination of time-series regression, driver-based scenario modeling, and expert-adjusted growth rates for each segment and region.
Data Accuracy & Quality Check
Our proprietary quality assurance framework guarantees an estimated data accuracy level of 85–90%, validated through three-stage review: primary data verification, secondary source triangulation, and expert panel adjudication.
Every report is updated to the date of purchase, ensuring that market estimates, competitive developments, and regulatory changes reflect the most current available intelligence.
Data quality checks included outlier detection, consistency scoring across regional datasets, and reconciliation of segment-level estimates to aggregate market totals.
Final outputs were reviewed by a senior analyst panel with domain expertise in building technologies and energy services, ensuring analytical rigor and commercial relevance.