1What is the current size of the temporary building market?
The global temporary building market is estimated at USD 9.1 billion in 2024, with a projected value of USD 13.3 billion by 2030, growing at a CAGR of 6.4%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Temporary Building Market
 by Material Type (Fabric-Based Structures, Metal-Framed Structures), by Application (Industrial Warehousing, Logistics, Construction, Agriculture, Defense, Others), by End User (Logistics & Warehousing Companies, Construction Firms, Industrial Manufacturers, Agriculture & Food Supply, Government & Defense Agencies), by Ownership (Rental Fleet, Direct Sale, Lease Program), by Structure (Industrial Canopies, Insulated Buildings, Storage Protect Range), by Installation (Freestanding, Lean-to, Gable Span), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Netherlands), by Asia Pacific (China, India, Japan, Australia), by Latin America (Brazil, Mexico), by Middle East & Africa (UAE, Saudi Arabia, South Africa) Forecast 2026-2034

Research Analyst

 Related Reports

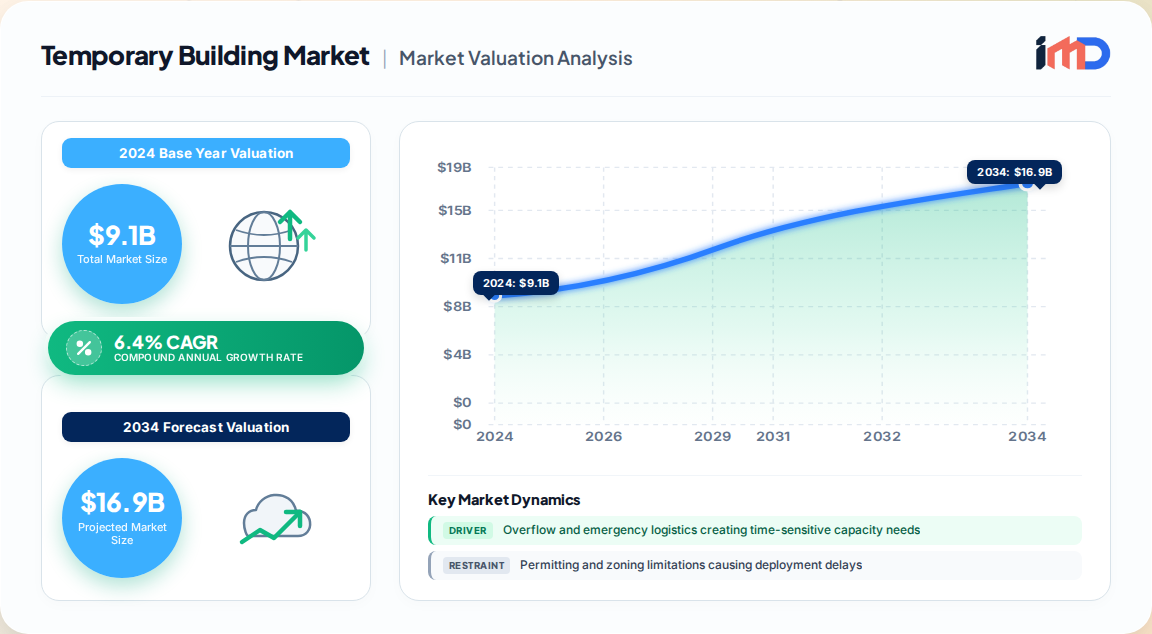
The global temporary building market represents a critical enabler of operational agility across logistics, construction, defense, and emergency response sectors. Our proprietary primary research estimates the market at USD 9.1 billion in 2024, with a projected expansion to USD 13.3 billion by 2030, reflecting a CAGR of 6.4% during the forecast period. This growth is underpinned by structural shifts in warehousing demand, rapid urbanization, and the increasing normalization of modular infrastructure as strategic—not merely auxiliary—assets.
Temporary buildings, encompassing fabric-based structures, metal-framed warehouses, and modular shelters, have evolved from stopgap solutions to engineered, code-compliant installations. The market's value proposition now centers on speed-to-deploy, reusability, and integration with digital supply chain ecosystems. Demand is particularly acute in North America and Europe, where warehouse vacancy rates remain near historic lows, and in Asia Pacific, where infrastructure development outpaces permanent zoning approvals.
The primary growth engine is the global warehousing shortage. E-commerce penetration, which crossed USD 1 trillion annually in the U.S., has intensified demand for rapid-deployment storage near urban consumption hubs. Temporary buildings bridge the gap between demand surges and permanent construction timelines, which often stretch 18–24 months.
Despite favorable demand fundamentals, the market faces friction from regulatory variability and skilled labor shortages.
The temporary building value chain spans material suppliers, OEMs, rental fleet operators, and installation service providers. Each link is differentiated by specialization—fabric versus metal structures—and service model—direct sale versus leasing.
The market is segmented by material, application, end user, and structure type. Fabric-based structures dominate with 57% share in 2024, valued at approximately USD 5.19 billion, favored for rapid deployment and lower cost. Metal-framed structures, at 43% share (USD 3.91 billion), are preferred for durability and high load-bearing applications.
| Segment | Share (2024) | Value (USD Billion) | Key Drivers |
|---|---|---|---|
| Fabric-Based Structures | 57% | 5.19 | Ease of installation, cost, seasonal storage |
| Metal-Framed Structures | 43% | 3.91 | Durability, load capacity, semi-permanent use |
| Industrial Warehousing (Application) | 34% | 3.09 | Manufacturing overflow, distribution |
| Logistics (Application) | 22% | 2.00 | E-commerce, 3PL expansion |
| Construction (Application) | 16% | 1.46 | On-site material storage |
| Agriculture (Application) | 12% | 1.09 | Seasonal crop and machinery storage |
| Defense (Application) | 9% | 0.82 | Field operations, deployment infrastructure |
By structure, industrial canopies account for 40.4% of demand in 2026, providing covered handling space for operations where full enclosure is unnecessary. Storage buildings lead type demand at 50.6%, reflecting the need for enclosed, protected capacity. Ownership is dominated by rental fleets (57%), with direct sales and lease programs comprising the remainder.
North America leads the market with 32% share (USD 2.91 billion in 2024), driven by advanced logistics infrastructure and federal disaster-response funding. The U.S. alone is estimated at USD 2.39 billion in 2024, projected to reach USD 3.55 billion by 2030 at a 6.8% CAGR. Demand is concentrated in coastal logistics hubs and the Midwest construction belt.
Europe holds 25% share (USD 2.28 billion), with Germany, France, and the UK driving adoption through regulatory support for modular infrastructure and sustainability mandates. The region is a hub for structural innovation, including cold-chain and defense-grade solutions.
Asia Pacific is the fastest-growing region at 30% share (USD 2.73 billion in 2024), led by China, India, and Southeast Asia. Industrial expansion, space constraints in megacities, and zoning delays for permanent builds are key growth catalysts. Australia and Japan are testing AI-equipped temporary warehouses with sensor integration.
Latin America, the Middle East, and Africa represent underpenetrated frontiers. Brazil and Mexico are seeing uptake in logistics and agriculture, while Gulf states deploy modular warehouses for mega-projects and religious tourism. Africa's adoption is driven by donor-funded health and emergency initiatives.
The competitive landscape is fragmented, with specialized OEMs, regional fabricators, and service providers vying on speed, compliance, and customization. Differentiation increasingly hinges on service models—leasing and redeployment—rather than product specs alone.
Successful players are those that offer integrated service packages, including site preparation, installation, maintenance, and teardown. Compliance with local building codes, fire safety, and environmental standards is non-negotiable for high-value applications such as pharmaceuticals and defense.
Several underleveraged opportunities exist across the value chain:
Buyers of temporary buildings must evaluate suppliers on a matrix of deployment speed, structural compliance, total cost of ownership, and service flexibility. Key procurement considerations include:
Through 2036, the temporary building market is expected to maintain a growth trajectory, with total value potentially reaching USD 6.0 billion for the storage-focused segment alone at a 6.1% CAGR. The broader market, including all applications, is projected to grow from USD 9.1 billion in 2024 to USD 13.3 billion by 2030.
Growth will be shaped by:
The market's future is not merely about providing temporary space but about delivering operational certainty, speed, and long-term reusability—transforming temporary buildings into strategic infrastructure.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
By End User
By Ownership
By Structure
By Installation
| By Geography |
|
The global temporary building market is estimated at USD 9.1 billion in 2024, with a projected value of USD 13.3 billion by 2030, growing at a CAGR of 6.4%.
North America leads with approximately 32% market share in 2024, driven by strong logistics infrastructure and disaster-response funding, followed closely by Asia Pacific at 30%.
Key drivers include warehousing shortages, e-commerce expansion, rapid deployment needs for emergency response, and cost efficiency—modular construction can save up to 20% compared to traditional builds.
The market is segmented into fabric-based structures (57% share) and metal-framed structures (43% share), with industrial canopies and storage buildings being prominent structure types.
Logistics and warehousing companies account for 31% of end-user demand, using temporary structures for overflow storage, seasonal capacity, and port congestion relief.
Recent innovations include Sprung Structures' cold-chain modular warehouses with IoT monitoring (2024), Röder HTS Höcker's installation-time reduction of 35% (2023), and Mahaffey USA's expanded turnkey leasing services (2024).
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Operations Manager | 25% |
| Logistics Director | 25% |
| Project Engineer | 20% |
| Company Type | Representation (%) |
|---|---|
| Fabric Structure OEMs | 35% |
| Metal-Framed Building Manufacturers | 25% |
| Rental Fleet Operators | 20% |
| Installation Contractors | 12% |
| Modular Building Distributors | 8% |