1What is the Property And Casualty Reinsurance Market size in 2025?
Our proprietary research values the Property And Casualty Reinsurance Market at USD 441.8 Billion in 2025, following a 2024 base valuation of USD 398.3 Billion.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Property And Casualty Reinsurance Market
 by Coverage (Fire Insurance, Marine Insurance, Professional Liability Insurance, Workers' Compensation Insurance, Health Insurance), by Distribution Channel (Agents and Brokers, Direct Insurers, Online Platforms, Bancassurance), by Risk Type (Property Insurance, Casualty Insurance, Financial Lines Insurance, Specialty Lines Insurance), by Client Type (Commercial, Residential, Industrial, Government), by Reinsurance Type (Proportional Reinsurance, Non-Proportional Reinsurance, Excess of Loss Reinsurance, Quota Share Reinsurance), by North America (USA, Canada, Bermuda, Mexico), by Europe (Germany, UK, France, Switzerland), by Asia Pacific (China, Japan, South Korea, India), by South America (Brazil, Argentina, Colombia), by Middle East & Africa (South Africa, Saudi Arabia, UAE) Forecast 2026-2034

Research Analyst


 Related Reports

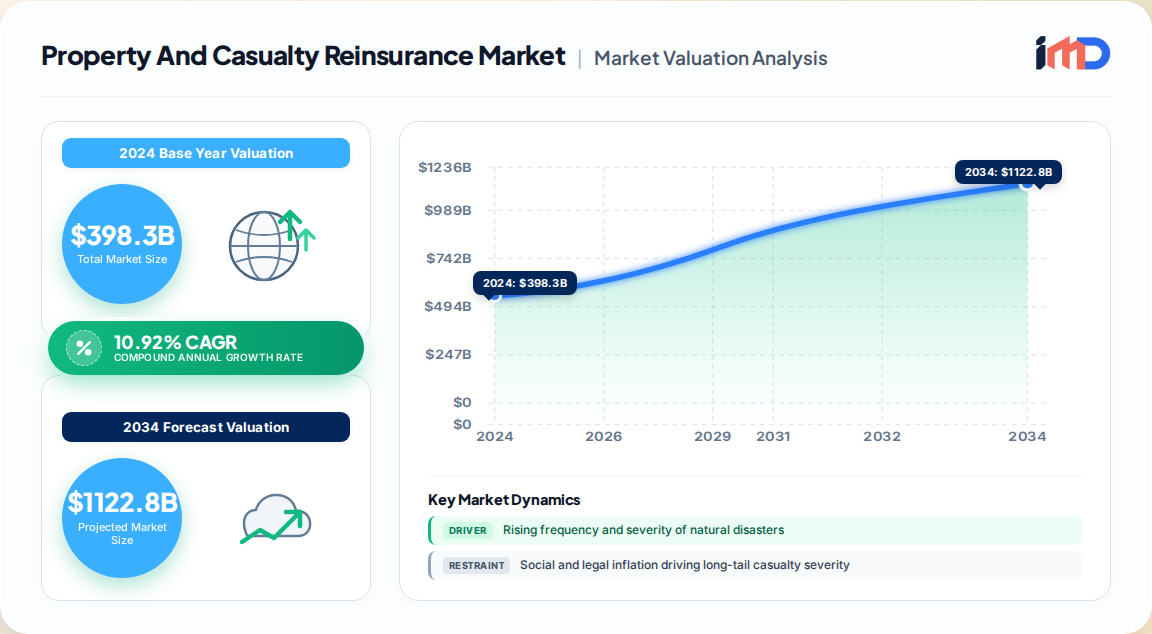
The Property And Casualty Reinsurance Market represents the financial shock-absorber of the global insurance ecosystem, absorbing the volatility that primary carriers cannot retain on their own balance sheets. Our proprietary first-party research estimates the market at USD 398.3 Billion in 2024, rising to USD 441.8 Billion in 2025 and expanding to USD 1,245.46 Billion by 2035, reflecting a robust CAGR of 10.92% across the 2025–2035 forecast window.
This growth trajectory is not a simple recovery story. It is a structural re-rating of risk. Three forces are converging: climate-driven catastrophe frequency, the emergence of intangible mega-risks (cyber, litigation-driven social inflation), and a technological step-change in how exposure is measured and priced.
| Metric | Value |
|---|---|
| 2024 Market Size | USD 398.3 Billion |
| 2025 Market Size | USD 441.8 Billion |
| 2035 Market Size | USD 1,245.46 Billion |
| CAGR (2025–2035) | 10.92% |
| Largest Coverage Segment | Health Insurance |
| Fastest-Growing Coverage Segment | Workers' Compensation Insurance |
| Largest Distribution Channel | Agents and Brokers |
| Fastest-Growing Distribution Channel | Online Platforms |
| Largest Risk Type | Property Insurance |
| Fastest-Growing Risk Type | Specialty Lines Insurance |
Reinsurance is no longer a passive capacity product sold at renewal. It is an analytics-driven capital allocation decision, and cedents increasingly select partners on modeling sophistication rather than balance-sheet size alone.
Insured losses from secondary perils — wildfire, convective storm, flood — have repeatedly breached historical norms. Primary carriers facing earnings volatility are purchasing deeper and broader catastrophe layers, including aggregate protections that did not exist as mainstream products a decade ago. This is the single largest demand lever in the market.
Cyber is the fastest-emerging specialty exposure. Ransomware, supply-chain compromise, and systemic cloud dependency create correlated loss potential that primary insurers cannot responsibly retain. Reinsurers are building dedicated cyber aggregates, and demand for cyber liability reinsurance is compounding annually.
Risk-based capital regimes and operational resilience mandates push cedents toward volatility transfer even when gross premiums are flat. Compliance cost is also a consolidation accelerant, favoring larger, better-capitalized reinsurers.
AI-enabled exposure aggregation, granular policy-level data, and parametric triggers compress the pricing cycle and enable tailored structures. Insurers digitizing exposure management buy reinsurance more frequently and with tighter attachment-point precision.
Health Insurance holds the largest share, reflecting the scale of delegated health risk transfer. Workers' Compensation Insurance is the fastest-growing coverage line, propelled by wage growth, medical-cost inflation, and regulatory benefit expansions.
Agents and Brokers remain the dominant channel, controlling complex treaty and facultative placements. Online Platforms are the fastest-growing channel as digital placement, API-driven submissions, and e-trading reduce friction in smaller and mid-market risks.
Property Insurance leads on volume, driven by catastrophe layers. Specialty Lines Insurance is the fastest-growing risk type, covering cyber, marine, crop, aviation, and surety exposures tied to supply-chain and economic-cycle variability.
Proportional and Non-Proportional structures both remain essential. Excess of Loss dominates catastrophe and per-risk protections, while Quota Share supports capital relief and new-business growth for cedents.
| Segment Dimension | Largest Segment | Fastest-Growing Segment |
|---|---|---|
| Coverage | Health Insurance | Workers' Compensation Insurance |
| Distribution Channel | Agents and Brokers | Online Platforms |
| Risk Type | Property Insurance | Specialty Lines Insurance |
| Client Type | Commercial | Government |
| Reinsurance Type | Non-Proportional (Excess of Loss) | Quota Share |
North America leads global reinsurance demand, anchored by U.S. and Bermuda markets and the highest catastrophe-loss concentration globally. Europe follows, shaped by Solvency II capital optimization and DORA-driven operational resilience requirements. Asia-Pacific is the fastest-growing region, supported by urbanization, rising insurance penetration, and open-insurance regulatory initiatives.
| Region | Market Position | Primary Demand Driver |
|---|---|---|
| North America | Largest share | Catastrophe protection and litigation-driven casualty |
| Europe | Mature, stable | Solvency capital optimization, ESG integration |
| Asia-Pacific | Fastest-growing | Penetration growth, urbanization, cyber awareness |
| South America | Emerging | Parametric and agricultural reinsurance |
| Middle East & Africa | Niche growth | Infrastructure and energy specialty covers |
The market is anchored by globally diversified reinsurers with deep catastrophe modeling capability and multi-decade cedent relationships. Competitive differentiation is shifting from capacity to intelligence — the ability to price correlation, quantify secondary perils, and deliver parametric certainty.
Key strategic developments observed in our primary channel checks:
Three underpenetrated opportunities warrant board-level attention:
Reinsurers that pair granular data with tailored structures will capture disproportionate margin as the market doubles in size over the forecast horizon.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.92% from 2020-2034 |
| Segmentation |
|
By Distribution Channel
By Risk Type
By Client Type
By Reinsurance Type
| By Geography |
|
Our proprietary research values the Property And Casualty Reinsurance Market at USD 441.8 Billion in 2025, following a 2024 base valuation of USD 398.3 Billion.
The market is projected to expand at a CAGR of 10.92% over the 2025–2035 forecast period, reaching USD 1,245.46 Billion by 2035.
Health Insurance is the largest coverage segment, while Property Insurance leads by risk type and Agents and Brokers dominate distribution.
North America holds the largest share, anchored by U.S. and Bermuda reinsurance capacity and the highest concentration of catastrophe losses globally.
Leading players include Munich Re, Swiss Re, Hannover Re, Berkshire Hathaway, Lloyd's of London, SCOR SE, Everest Re, PartnerRe, and Reinsurance Group of America.
Wage growth, medical-cost inflation, and expanding regulatory benefit mandates are driving strong reinsurance demand for Workers' Compensation Insurance.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Underwriting Officer | 32% |
| Head of Reinsurance Buying / Ceded Re | 28% |
| Chief Risk Officer | 22% |
| Reinsurance Broker / Treaty Placement Lead | 18% |
| Company Type | Representation (%) |
|---|---|
| Global and regional reinsurers (treaty and facultative) | 34% |
| Primary P&C insurance carriers (cedents) | 26% |
| Reinsurance brokers and placement advisers | 20% |
| Catastrophe modeling and risk analytics firms | 12% |
| Regulators, solvency supervisors, and trade bodies | 8% |