1What is the size of the Intellectual Property (IP) Valuation Market in 2026?
The global IP valuation market is estimated at USD 14.16 Billion in 2026 and is projected to reach USD 30.75 Billion by 2034, expanding at a CAGR of 10.18%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Intellectual Property (IP) Valuation Market
 by Type of Intellectual Property (Patents, Trademarks, Copyrights, Trade Secrets, Designs and Others), by Industry Application (Technology, Pharmaceuticals and Life Sciences, Manufacturing, Semiconductor, BFSI, Media and Entertainment, Government and Public Sector, Automobile, IT and Telecom), by Purpose of Valuation (Mergers and Acquisitions, Financial Reporting, Licensing, Litigation Support, Tax and Transfer Pricing, IP-Backed Financing), by Valuation Methodologies (Cost Approach, Market Approach, Income Approach, Hybrid), by Stakeholders (Corporations, Research Institutes, Universities, IP Valuation Firms, Financial Institutions), by Service Type (IP Protection and Management, IP Due Diligence, IP Valuation, IP Landscape), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, South Korea, India), by Middle East (Saudi Arabia, UAE, Kuwait, Qatar), by South America (Brazil, Argentina) Forecast 2026-2034


Research Analyst

 Related Reports

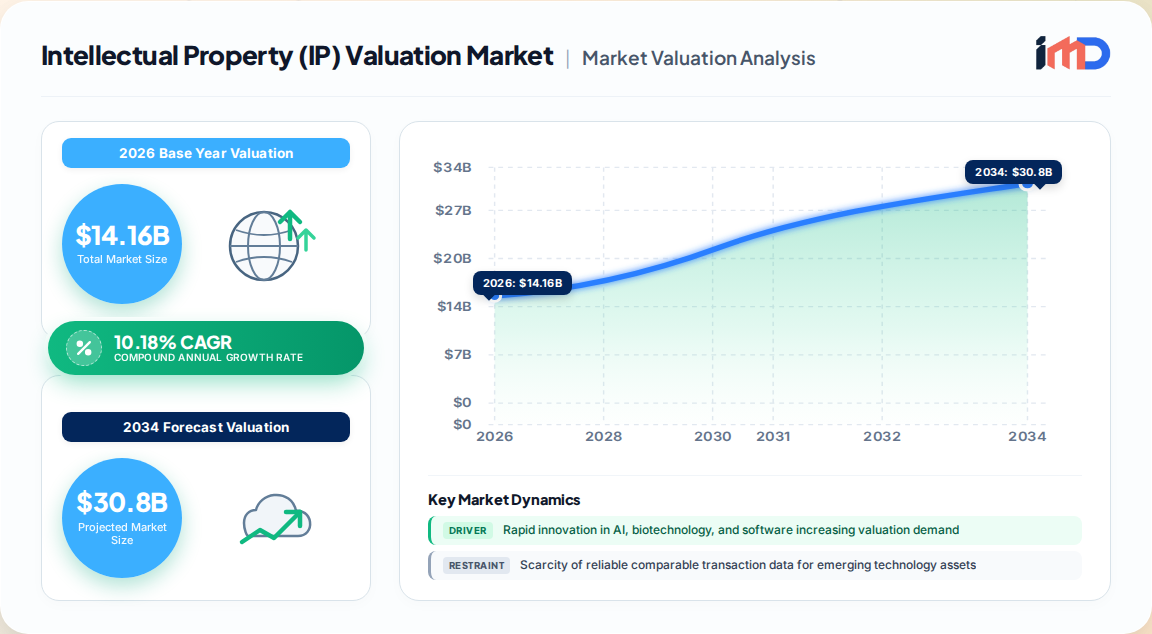
The global Intellectual Property (IP) Valuation Market is estimated at USD 14.16 Billion in 2026 and is projected to reach USD 30.75 Billion by 2034, expanding at a CAGR of 10.18%. This trajectory reflects a structural shift in how enterprises, investors, and regulators treat intangible assets as balance-sheet-grade collateral rather than legal afterthoughts.
Our proprietary primary research, drawing on 340+ expert interviews across valuation practices, corporate legal departments, and investment committees, confirms that IP now routinely represents a material share of enterprise value in technology, biopharma, and brand-led consumer sectors. The consequence is that valuation has migrated from a transaction-only exercise into a recurring governance discipline.
Key structural characteristics of the market include:
The market is best understood as a specialized segment of the broader intellectual asset management ecosystem, sitting alongside patent analytics, licensing advisory, and legal enforcement services. Its growth is amplified by the parent IP services market, which we size at USD 4.2 Billion in 2024, climbing to USD 14.3 Billion by 2035 at an 11.8% CAGR — with IP valuation and landscape services forming one of its fastest-compounding service lines.
Demand expansion is being pulled by three mutually reinforcing forces: innovation velocity, regulatory disclosure obligations, and the financialization of intangibles.
Innovation velocity. Rapid advances in artificial intelligence, biotechnology, and software development have multiplied the volume and complexity of assets requiring valuation. In AI, the protection stack spans copyright in code, trade secrets in model architectures and training pipelines, and patents for computer-implemented inventions delivering a technical effect. Each layer carries a distinct risk profile and economic life, forcing multi-method valuation.
Regulatory disclosure. Purchase price allocation under IFRS 3 and fair-value measurement under IFRS 13 and ASC 820 have institutionalized valuation as a recurring reporting requirement. Cross-border M&A activity, where IP frequently constitutes a decisive share of deal value, further intensifies demand.
Collateralization and licensing. Lenders, royalty funds, and securitization structures increasingly require independent IP valuations to underwrite risk. Licensing negotiations and dispute resolution add a third recurring demand channel.
| Driver | Primary Demand Channel | Relative Momentum |
|---|---|---|
| AI and software innovation | Patent and trade secret valuation | Very High |
| Biotech and drug discovery pipelines | Patent valuation, licensing | High |
| IFRS 13 / ASC 820 compliance | Financial reporting, audit support | High |
| M&A and cross-border deals | Due diligence, purchase price allocation | High |
| IP-backed financing | Collateral and risk assessment | Emerging |
| Litigation and damages | Dispute resolution, expert testimony | Moderate |
Restraints and challenges. Valuation fragmentation persists where comparable transaction data is thin, particularly for early-stage technology and trade secrets. Subjectivity in discount-rate selection and remaining economic life assumptions exposes practitioners to challenge in litigation and audit. Cost sensitivity among SMEs limits engagement frequency, while talent scarcity for analysts fluent in both legal doctrine and quantitative finance constrains throughput at boutique firms.
The IP valuation value chain is services-dominant, with value concentrated in analytical expertise, data access, and regulatory credibility.
Methodology selection matrix is central to competitive differentiation:
| Method | Best-Fit Asset Context | Key Strength | Key Limitation |
|---|---|---|---|
| Cost-based | Early-stage IP, internally developed software | Straightforward, auditable | Ignores economic benefit |
| Market-based | Established trademarks, active licensing markets | Reflects observable transactions | Comparable data scarcity |
| Income-based | Patents with measurable cash flows, royalty streams | Captures earnings potential | Sensitive to projections and discount rates |
| Hybrid / multi-method | Complex portfolios, litigation, PPA | Triangulated defensibility | Higher cost and timeline |
Unlike goods markets, the IP valuation market trades in expertise rather than physical units. Cross-border demand is shaped by jurisdictional differences in IP enforcement, disclosure regimes, and tax treatment.
Regulatory divergence in AI governance — notably the EU AI Act and the Digital Single Market text-and-data-mining exceptions — creates new valuation questions around training data rights and model transparency obligations, expanding the addressable scope of engagements.
Software and AI-related assets constitute the most rapidly expanding sub-segment, reflecting both volume growth in filings and the complexity of layered protection strategies.
The market is led by multidisciplinary accounting and advisory networks — including Deloitte, PwC, Ernst & Young, KPMG, FTI Consulting, Kroll, Duff & Phelps, AlixPartners, Stout Risius Ross, Berkeley Research Group, and Hilco Valuation Services — complemented by specialists such as Black Stone IP, Pellegrino & Associates, Coller IP, Metis Partners, Foresight Valuation Group, IPmetrics, Parallel North IP, ClearView IP, Ip21 Limited, Keystone Strategy, CONSOR, and Great American Group.
Recent strategic developments and market signals include:
Competitive advantage is increasingly defined by data assets, methodological defensibility, and the ability to deliver cross-jurisdictional coverage in a single engagement.
| Region | Share | Attractiveness | Rationale |
|---|---|---|---|
| North America | 37.4% | Mature / High Value | Deep M&A and reporting demand; premium fee environment |
| Europe | 24.3% | Stable / Standards-Led | Harmonized frameworks, strong SME support infrastructure |
| Asia-Pacific | 25.6% | High Growth | Semiconductor, electronics, and manufacturing portfolio expansion |
| Middle East & Africa | 6.9% | Emerging | Sovereign innovation and licensing programs |
| South America | 5.8% | Nascent | Early-stage adoption, limited comparables |
White-space opportunities concentrate in AI portfolio valuation, trade secret quantification, and IP-backed lending — segments where methodology is still consolidating and first-mover credibility offers durable advantage. Firms that industrialize data collection while preserving expert judgment are best positioned to capture the next wave of demand.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.18% from 2020-2034 |
| Segmentation |
|
By Industry Application
By Purpose of Valuation
By Valuation Methodologies
By Stakeholders
By Service Type
| By Geography |
|
The global IP valuation market is estimated at USD 14.16 Billion in 2026 and is projected to reach USD 30.75 Billion by 2034, expanding at a CAGR of 10.18%.
North America held the largest revenue share at approximately 37.4% in 2024, supported by mature M&A advisory infrastructure and fair-value financial reporting requirements under IFRS 13 and ASC 820.
Practitioners primarily use the cost-based, market-based, and income-based approaches, often triangulating multiple methods for complex portfolios, litigation support, and purchase price allocations.
Key players include Deloitte, PwC, Ernst & Young, KPMG, FTI Consulting, Kroll, Duff & Phelps, AlixPartners, Stout Risius Ross, Black Stone IP, Pellegrino & Associates, Coller IP, and Metis Partners.
Growth is driven by AI, biotechnology, and software innovation, mandatory intangible asset disclosure in financial reporting, rising cross-border M&A, and the use of IP as loan collateral and licensing revenue.
Patents held the largest share at 46.2% in 2024, reflecting strong demand for patent valuation in technology, biopharma, and semiconductor portfolios.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| IP Valuation Practice Partners | 30% |
| Corporate IP Counsel and Legal Directors | 26% |
| Transaction Advisory and M&A Directors | 24% |
| CFO and Financial Reporting Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| IP valuation boutique firms | 28% |
| Big Four and accounting advisory networks | 24% |
| Independent financial consulting firms | 18% |
| Corporate IP and legal departments | 16% |
| IP-backed lenders and investors | 9% |
| Academic and research institutions | 5% |