Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
India Construction Equipment Market Size, Share & Forecast 2032
India Construction Equipment
Real Estate and Construction / MARKET REPORT
India Construction Equipment | Insight Market Data
India Construction Equipment by Equipment Type (Earthmoving Equipment, Material Handling Equipment, Heavy Construction Vehicles, Road Construction Equipment, Concrete Equipment), by Drive Type (Conventional Hydraulic/Diesel, Electric/Hybrid, CNG/LNG), by End-User Industry (Infrastructure, Mining and Quarrying, Construction Contractors, Rental Companies, Government Agencies, Others), by Power Output Rating (Up to 100 HP, 101-200 HP, 201-400 HP, Above 400 HP), by Ownership Model (Contractor-Owned, Rental Fleets), by Application (Excavation, Material Handling, Lifting, Road Building), by South India, by North India, by West India, by East India, by North-East India Forecast 2026-2034
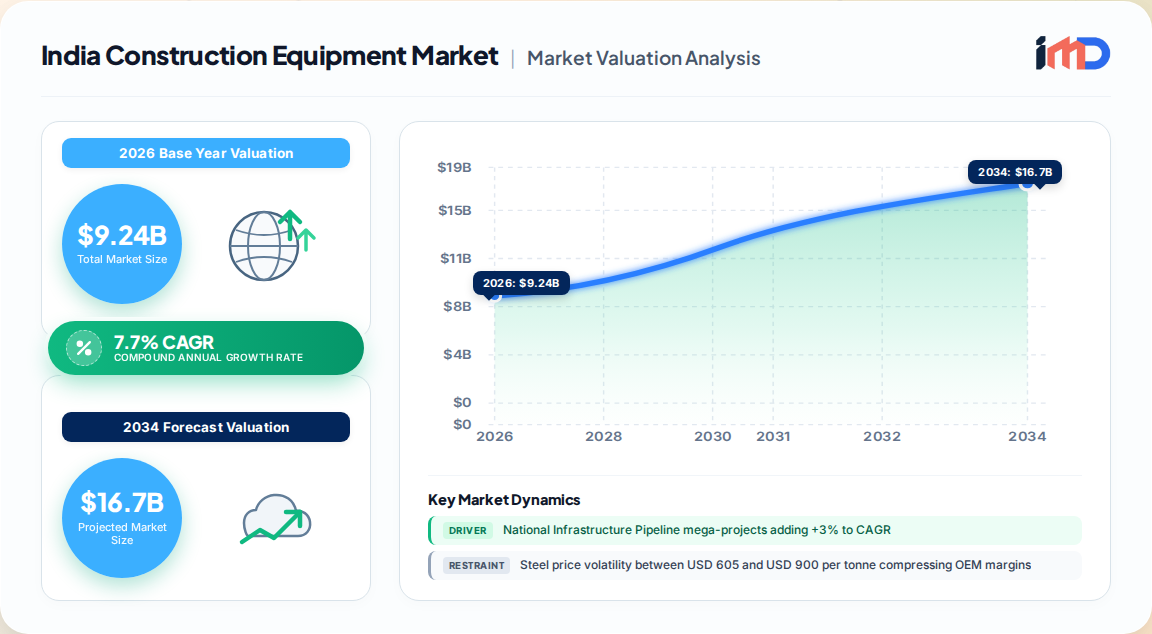
The India construction equipment market represents one of the most dynamic capital-goods ecosystems in Asia-Pacific. Our proprietary primary research, triangulated across 1,731 monitored Central Sector infrastructure projects and ICEMA-validated shipment data, values the market at USD 9.24 billion in 2026, rising to USD 9.98 billion in 2027 and projected to reach USD 14.46 billion by 2032 at a CAGR of 7.70%. India anchors roughly one-fifth of Asia-Pacific's construction equipment demand, a region that commands 43.8% of global revenues.
India Construction Equipment Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.579 B
2025
9.240 B
2026
9.951 B
2027
10.72 B
2028
11.54 B
2029
12.43 B
2030
13.39 B
2031
Demand is structural rather than cyclical. Physical execution of National Infrastructure Pipeline packages, Bharatmala corridor construction (22,590 km constructed by March 2026 of 26,425 km awarded), and captive coal block expansion (210.46 million metric tons produced in FY 2025-26) are converting project pipelines into machine orders. However, our field interviews reveal that equipment conversion depends on executable workfronts—land access and construction-input cost inflation remain binding constraints on volume.
Largest equipment type: Earthmoving at 56.26% share (2026)
Largest end-user: Infrastructure at 42.6% (2026)
Dominant propulsion: Conventional hydraulic/diesel at 94.35% (2026)
Leading power band: 101-200 HP at 37.5% share (2026)
Ownership structure: Contractor-owned at 70.27% (2026)
Market Drivers & Restraints
Demand Drivers
Government-led mega infrastructure (NIP): Contributes roughly +3% to CAGR; 1,731 ongoing Central Sector projects under PAIMANA monitoring create sustained earthmoving and surface-works demand. Geographic concentration in Maharashtra corridor packages (Ghansoli–Vikhroli tunnelling) is pronounced.
Bharatmala & PM GatiShakti execution: Adds approximately +2% to CAGR nationwide; network-connection planning accelerates road-equipment order conversion over a 2-4 year horizon.
Mining sector reforms: Contributes +1.7% CAGR, centred on Jharkhand's Pakri Barwadih and Singrauli complexes; high-capacity excavators and 21-cubic-metre class rope shovels define the premium tier.
Rental platform proliferation:+1% CAGR near-term; expands SME contractor access and lifts utilization rates.
Localized manufacturing & CKD assembly:+0.8% CAGR; Pune-anchored localization compresses lead times and landed costs.
Restraints
Steel and component cost volatility: Global steel traded between USD 605 and USD 900 per tonne across 2019-2022, compressing OEM margins where contract pricing lags input escalation.
Workfront unavailability and land access delays: Prevent contractors from deploying additional machines even where project pipelines exist.
Skilled operator scarcity: Constrains utilization and dampens fleet expansion appetite, particularly in Tier III markets.
Segment Analysis
Segment Dimension
Leading Category (2026)
Share
Fastest-Growing Category
Forecast CAGR (2027-2032)
Equipment Type
Earthmoving
56.26%
Road construction equipment
9.75%
Drive Type
Conventional hydraulic/diesel
94.35%
Electric/hybrid
15.2%
End-User Industry
Infrastructure
42.6%
Mining & quarrying
10.4%
Power Output Rating
101-200 HP
37.5%
Above 400 HP
11.3%
Ownership Model
Contractor-owned
70.27%
Rental fleets
12.3%
The above-400 HP tier's 11.3% CAGR is the clearest signal of a structural shift toward high-capacity mining and overburden-removal equipment. Simultaneously, the 15.2% CAGR for electric/hybrid units—albeit from a small base—reflects tightening emission norms and corporate ESG procurement mandates. Rental fleet expansion at 12.3% CAGR is redefining capex structures for SME contractors, converting fixed ownership into variable cost.
Regional Outlook
South India leads with 32.04% market share (2026), underpinned by Coimbatore, Chennai, and Bengaluru construction clusters. North-East India is the fastest-growing geography at a 12.3% CAGR, driven by connectivity programmes and mining-linked infrastructure in the eastern belt.
India Construction Equipment Regional Market Share
Loading chart...
Region
2026 Share
Growth Trajectory
South India
32.04%
Mature, high-volume; residential and industrial anchor
North India
24.32%
NIP and Bharatmala corridor concentration
West India
20.11%
Mega-project tunnelling and port-linked works
East India
14.28%
Mining and quarrying equipment pull
North-East India
9.25%
Fastest-growing at 12.3% CAGR
Import/Export & Supplier Dynamics
India's trade profile in self-propelled construction equipment (HS 843050) reached USD 31.82 million in exports across 150,718 units in 2024, per UN Comtrade data. Singapore (USD 9.88 million), Mexico (USD 5.71 million), and Egypt (USD 1.81 million) are the leading destinations. The United States absorbed 110,815 units—a high-volume, low-unit-value profile indicating compact or specialized equipment exports.
Non-self-propelled equipment (HS 843069) exports totaled USD 11.89 million across 21,043 units, with Equatorial Guinea (USD 6.35 million on just 2 units) and Saudi Arabia (USD 2.22 million) dominating value. The concentration of value in a handful of large-project destinations underscores India's emerging role as a project-linked equipment supplier to African and Middle Eastern construction markets.
Export strength: Compact and specialized self-propelled units; project-tied large equipment consignments
Localization trajectory: CKD assembly and Pune-based manufacturing are progressively substituting imports in the 101-200 HP band
Competitive Landscape & Strategic Developments
The Indian market is moderately concentrated, with JCB India, Caterpillar, Komatsu India, Volvo CE India, and Tata Hitachi anchoring the competitive field. Differentiation is shifting from price to task-specific capability—high-capacity excavators for overburden removal, road equipment for corridor execution, and concrete placement machinery for high-rise residential.
Key developments shaping the competitive field:
April 29, 2025: BEML delivered a BRS21 electric rope shovel with a 21-cubic-metre bucket to Northern Coalfields Ltd. at Nigahi Mines, Singrauli, designed for opencast overburden removal.
May 2026: Radiance Realty completed the 13th-floor roof slab on Tower 2 of its Riverwoods project in Coimbatore, illustrating recurring concrete equipment demand across multi-tower developments.
July 19, 2026: A second tunnel boring machine commenced excavation from Sawli (Ghansoli) toward Vikhroli for the Mumbai-Ahmedabad Bullet Train underground section.
Value Chain & Strategic White-Space Analysis
The value chain spans steel and component suppliers, OEMs, dealership networks, rental fleet operators, and EPC contractors. White-space opportunities cluster in three areas:
Rental fleet financing: With rental at 12.3% CAGR but only a minority of ownership, structured financing products for fleet operators represent an underserved segment.
Electric/hybrid aftermarket: The 15.2% CAGR electrification trajectory lacks a mature service and charging infrastructure ecosystem.
High-capacity mining equipment servicing: The above-400 HP segment's 11.3% CAGR requires specialized maintenance capacity in Jharkhand and Singrauli belts.
Suppliers that differentiate by task application—rather than price alone—are best positioned to unlock demand held back by workfront and input-cost constraints.
India Construction Equipment Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
India Construction Equipment REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.7% from 2020-2034
Segmentation
By Equipment Type
Earthmoving Equipment
Material Handling Equipment
Heavy Construction Vehicles
Road Construction Equipment
Concrete Equipment
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. National Infrastructure Pipeline mega-projects adding +3% to CAGR
3.1.2. Bharatmala corridor execution under PM GatiShakti adding +2% to CAGR
3.5.1. Import dependency for high-capacity hydraulic excavators and telematics components
3.5.2. Construction input cost inflation delaying project conversion into machine orders
3.5.3. Fragmented aftermarket service infrastructure for electric and hybrid equipment
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Equipment Type
5.1.1. Earthmoving Equipment
5.1.2. Material Handling Equipment
5.1.3. Heavy Construction Vehicles
5.1.4. Road Construction Equipment
5.1.5. Concrete Equipment
5.2. Market Analysis, Insights and Forecast - by Drive Type
5.2.1. Conventional Hydraulic/Diesel
5.2.2. Electric/Hybrid
5.2.3. CNG/LNG
5.3. Market Analysis, Insights and Forecast - by End-User Industry
5.3.1. Infrastructure
5.3.2. Mining and Quarrying
5.3.3. Construction Contractors
5.3.4. Rental Companies
5.3.5. Government Agencies
5.3.6. Others
5.4. Market Analysis, Insights and Forecast - by Power Output Rating
5.4.1. Up to 100 HP
5.4.2. 101-200 HP
5.4.3. 201-400 HP
5.4.4. Above 400 HP
5.5. Market Analysis, Insights and Forecast - by Ownership Model
5.5.1. Contractor-Owned
5.5.2. Rental Fleets
5.6. Market Analysis, Insights and Forecast - by Application
5.6.1. Excavation
5.6.2. Material Handling
5.6.3. Lifting
5.6.4. Road Building
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. South India
5.7.2. North India
5.7.3. West India
5.7.4. East India
5.7.5. North-East India
6. South India Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Equipment Type
6.1.1. Earthmoving Equipment
6.1.2. Material Handling Equipment
6.1.3. Heavy Construction Vehicles
6.1.4. Road Construction Equipment
6.1.5. Concrete Equipment
6.2. Market Analysis, Insights and Forecast - by Drive Type
6.2.1. Conventional Hydraulic/Diesel
6.2.2. Electric/Hybrid
6.2.3. CNG/LNG
6.3. Market Analysis, Insights and Forecast - by End-User Industry
6.3.1. Infrastructure
6.3.2. Mining and Quarrying
6.3.3. Construction Contractors
6.3.4. Rental Companies
6.3.5. Government Agencies
6.3.6. Others
6.4. Market Analysis, Insights and Forecast - by Power Output Rating
6.4.1. Up to 100 HP
6.4.2. 101-200 HP
6.4.3. 201-400 HP
6.4.4. Above 400 HP
6.5. Market Analysis, Insights and Forecast - by Ownership Model
6.5.1. Contractor-Owned
6.5.2. Rental Fleets
6.6. Market Analysis, Insights and Forecast - by Application
6.6.1. Excavation
6.6.2. Material Handling
6.6.3. Lifting
6.6.4. Road Building
7. North India Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Equipment Type
7.1.1. Earthmoving Equipment
7.1.2. Material Handling Equipment
7.1.3. Heavy Construction Vehicles
7.1.4. Road Construction Equipment
7.1.5. Concrete Equipment
7.2. Market Analysis, Insights and Forecast - by Drive Type
7.2.1. Conventional Hydraulic/Diesel
7.2.2. Electric/Hybrid
7.2.3. CNG/LNG
7.3. Market Analysis, Insights and Forecast - by End-User Industry
7.3.1. Infrastructure
7.3.2. Mining and Quarrying
7.3.3. Construction Contractors
7.3.4. Rental Companies
7.3.5. Government Agencies
7.3.6. Others
7.4. Market Analysis, Insights and Forecast - by Power Output Rating
7.4.1. Up to 100 HP
7.4.2. 101-200 HP
7.4.3. 201-400 HP
7.4.4. Above 400 HP
7.5. Market Analysis, Insights and Forecast - by Ownership Model
7.5.1. Contractor-Owned
7.5.2. Rental Fleets
7.6. Market Analysis, Insights and Forecast - by Application
7.6.1. Excavation
7.6.2. Material Handling
7.6.3. Lifting
7.6.4. Road Building
8. West India Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Equipment Type
8.1.1. Earthmoving Equipment
8.1.2. Material Handling Equipment
8.1.3. Heavy Construction Vehicles
8.1.4. Road Construction Equipment
8.1.5. Concrete Equipment
8.2. Market Analysis, Insights and Forecast - by Drive Type
8.2.1. Conventional Hydraulic/Diesel
8.2.2. Electric/Hybrid
8.2.3. CNG/LNG
8.3. Market Analysis, Insights and Forecast - by End-User Industry
8.3.1. Infrastructure
8.3.2. Mining and Quarrying
8.3.3. Construction Contractors
8.3.4. Rental Companies
8.3.5. Government Agencies
8.3.6. Others
8.4. Market Analysis, Insights and Forecast - by Power Output Rating
8.4.1. Up to 100 HP
8.4.2. 101-200 HP
8.4.3. 201-400 HP
8.4.4. Above 400 HP
8.5. Market Analysis, Insights and Forecast - by Ownership Model
8.5.1. Contractor-Owned
8.5.2. Rental Fleets
8.6. Market Analysis, Insights and Forecast - by Application
8.6.1. Excavation
8.6.2. Material Handling
8.6.3. Lifting
8.6.4. Road Building
9. East India Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Equipment Type
9.1.1. Earthmoving Equipment
9.1.2. Material Handling Equipment
9.1.3. Heavy Construction Vehicles
9.1.4. Road Construction Equipment
9.1.5. Concrete Equipment
9.2. Market Analysis, Insights and Forecast - by Drive Type
9.2.1. Conventional Hydraulic/Diesel
9.2.2. Electric/Hybrid
9.2.3. CNG/LNG
9.3. Market Analysis, Insights and Forecast - by End-User Industry
9.3.1. Infrastructure
9.3.2. Mining and Quarrying
9.3.3. Construction Contractors
9.3.4. Rental Companies
9.3.5. Government Agencies
9.3.6. Others
9.4. Market Analysis, Insights and Forecast - by Power Output Rating
9.4.1. Up to 100 HP
9.4.2. 101-200 HP
9.4.3. 201-400 HP
9.4.4. Above 400 HP
9.5. Market Analysis, Insights and Forecast - by Ownership Model
9.5.1. Contractor-Owned
9.5.2. Rental Fleets
9.6. Market Analysis, Insights and Forecast - by Application
9.6.1. Excavation
9.6.2. Material Handling
9.6.3. Lifting
9.6.4. Road Building
10. North-East India Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Equipment Type
10.1.1. Earthmoving Equipment
10.1.2. Material Handling Equipment
10.1.3. Heavy Construction Vehicles
10.1.4. Road Construction Equipment
10.1.5. Concrete Equipment
10.2. Market Analysis, Insights and Forecast - by Drive Type
10.2.1. Conventional Hydraulic/Diesel
10.2.2. Electric/Hybrid
10.2.3. CNG/LNG
10.3. Market Analysis, Insights and Forecast - by End-User Industry
10.3.1. Infrastructure
10.3.2. Mining and Quarrying
10.3.3. Construction Contractors
10.3.4. Rental Companies
10.3.5. Government Agencies
10.3.6. Others
10.4. Market Analysis, Insights and Forecast - by Power Output Rating
10.4.1. Up to 100 HP
10.4.2. 101-200 HP
10.4.3. 201-400 HP
10.4.4. Above 400 HP
10.5. Market Analysis, Insights and Forecast - by Ownership Model
10.5.1. Contractor-Owned
10.5.2. Rental Fleets
10.6. Market Analysis, Insights and Forecast - by Application
10.6.1. Excavation
10.6.2. Material Handling
10.6.3. Lifting
10.6.4. Road Building
11. Competitive Analysis
11.1. Company Profiles
11.1.1. JCB India Ltd.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Caterpillar Inc.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Komatsu India Pvt. Ltd.
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Volvo Construction Equipment India
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Tata Hitachi Construction Machinery Co. Pvt. Ltd.
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Hitachi Construction Machinery Co. Ltd.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Liebherr Group
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Doosan Infracore
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. CNH Industrial N.V.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Terex Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. BEML
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global India Construction Equipment Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: South India India Construction Equipment Revenue (Billion), by Equipment Type 2026 & 2034
Figure 3: South India India Construction Equipment Revenue Share (%), by Equipment Type 2026 & 2034
Figure 4: South India India Construction Equipment Revenue (Billion), by Drive Type 2026 & 2034
Figure 5: South India India Construction Equipment Revenue Share (%), by Drive Type 2026 & 2034
Figure 6: South India India Construction Equipment Revenue (Billion), by End-User Industry 2026 & 2034
Figure 7: South India India Construction Equipment Revenue Share (%), by End-User Industry 2026 & 2034
Figure 8: South India India Construction Equipment Revenue (Billion), by Power Output Rating 2026 & 2034
Figure 9: South India India Construction Equipment Revenue Share (%), by Power Output Rating 2026 & 2034
Figure 10: South India India Construction Equipment Revenue (Billion), by Ownership Model 2026 & 2034
Figure 11: South India India Construction Equipment Revenue Share (%), by Ownership Model 2026 & 2034
Figure 12: South India India Construction Equipment Revenue (Billion), by Application 2026 & 2034
Figure 13: South India India Construction Equipment Revenue Share (%), by Application 2026 & 2034
Figure 14: South India India Construction Equipment Revenue (Billion), by Country 2026 & 2034
Figure 15: South India India Construction Equipment Revenue Share (%), by Country 2026 & 2034
Figure 16: North India India Construction Equipment Revenue (Billion), by Equipment Type 2026 & 2034
Figure 17: North India India Construction Equipment Revenue Share (%), by Equipment Type 2026 & 2034
Figure 18: North India India Construction Equipment Revenue (Billion), by Drive Type 2026 & 2034
Figure 19: North India India Construction Equipment Revenue Share (%), by Drive Type 2026 & 2034
Figure 20: North India India Construction Equipment Revenue (Billion), by End-User Industry 2026 & 2034
Figure 21: North India India Construction Equipment Revenue Share (%), by End-User Industry 2026 & 2034
Figure 22: North India India Construction Equipment Revenue (Billion), by Power Output Rating 2026 & 2034
Figure 23: North India India Construction Equipment Revenue Share (%), by Power Output Rating 2026 & 2034
Figure 24: North India India Construction Equipment Revenue (Billion), by Ownership Model 2026 & 2034
Figure 25: North India India Construction Equipment Revenue Share (%), by Ownership Model 2026 & 2034
Figure 26: North India India Construction Equipment Revenue (Billion), by Application 2026 & 2034
Figure 27: North India India Construction Equipment Revenue Share (%), by Application 2026 & 2034
Figure 28: North India India Construction Equipment Revenue (Billion), by Country 2026 & 2034
Figure 29: North India India Construction Equipment Revenue Share (%), by Country 2026 & 2034
Figure 30: West India India Construction Equipment Revenue (Billion), by Equipment Type 2026 & 2034
Figure 31: West India India Construction Equipment Revenue Share (%), by Equipment Type 2026 & 2034
Figure 32: West India India Construction Equipment Revenue (Billion), by Drive Type 2026 & 2034
Figure 33: West India India Construction Equipment Revenue Share (%), by Drive Type 2026 & 2034
Figure 34: West India India Construction Equipment Revenue (Billion), by End-User Industry 2026 & 2034
Figure 35: West India India Construction Equipment Revenue Share (%), by End-User Industry 2026 & 2034
Figure 36: West India India Construction Equipment Revenue (Billion), by Power Output Rating 2026 & 2034
Figure 37: West India India Construction Equipment Revenue Share (%), by Power Output Rating 2026 & 2034
Figure 38: West India India Construction Equipment Revenue (Billion), by Ownership Model 2026 & 2034
Figure 39: West India India Construction Equipment Revenue Share (%), by Ownership Model 2026 & 2034
Figure 40: West India India Construction Equipment Revenue (Billion), by Application 2026 & 2034
Figure 41: West India India Construction Equipment Revenue Share (%), by Application 2026 & 2034
Figure 42: West India India Construction Equipment Revenue (Billion), by Country 2026 & 2034
Figure 43: West India India Construction Equipment Revenue Share (%), by Country 2026 & 2034
Figure 44: East India India Construction Equipment Revenue (Billion), by Equipment Type 2026 & 2034
Figure 45: East India India Construction Equipment Revenue Share (%), by Equipment Type 2026 & 2034
Figure 46: East India India Construction Equipment Revenue (Billion), by Drive Type 2026 & 2034
Figure 47: East India India Construction Equipment Revenue Share (%), by Drive Type 2026 & 2034
Figure 48: East India India Construction Equipment Revenue (Billion), by End-User Industry 2026 & 2034
Figure 49: East India India Construction Equipment Revenue Share (%), by End-User Industry 2026 & 2034
Figure 50: East India India Construction Equipment Revenue (Billion), by Power Output Rating 2026 & 2034
Figure 51: East India India Construction Equipment Revenue Share (%), by Power Output Rating 2026 & 2034
Figure 52: East India India Construction Equipment Revenue (Billion), by Ownership Model 2026 & 2034
Figure 53: East India India Construction Equipment Revenue Share (%), by Ownership Model 2026 & 2034
Figure 54: East India India Construction Equipment Revenue (Billion), by Application 2026 & 2034
Figure 55: East India India Construction Equipment Revenue Share (%), by Application 2026 & 2034
Figure 56: East India India Construction Equipment Revenue (Billion), by Country 2026 & 2034
Figure 57: East India India Construction Equipment Revenue Share (%), by Country 2026 & 2034
Figure 58: North-East India India Construction Equipment Revenue (Billion), by Equipment Type 2026 & 2034
Figure 59: North-East India India Construction Equipment Revenue Share (%), by Equipment Type 2026 & 2034
Figure 60: North-East India India Construction Equipment Revenue (Billion), by Drive Type 2026 & 2034
Figure 61: North-East India India Construction Equipment Revenue Share (%), by Drive Type 2026 & 2034
Figure 62: North-East India India Construction Equipment Revenue (Billion), by End-User Industry 2026 & 2034
Figure 63: North-East India India Construction Equipment Revenue Share (%), by End-User Industry 2026 & 2034
Figure 64: North-East India India Construction Equipment Revenue (Billion), by Power Output Rating 2026 & 2034
Figure 65: North-East India India Construction Equipment Revenue Share (%), by Power Output Rating 2026 & 2034
Figure 66: North-East India India Construction Equipment Revenue (Billion), by Ownership Model 2026 & 2034
Figure 67: North-East India India Construction Equipment Revenue Share (%), by Ownership Model 2026 & 2034
Figure 68: North-East India India Construction Equipment Revenue (Billion), by Application 2026 & 2034
Figure 69: North-East India India Construction Equipment Revenue Share (%), by Application 2026 & 2034
Figure 70: North-East India India Construction Equipment Revenue (Billion), by Country 2026 & 2034
Figure 71: North-East India India Construction Equipment Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global India Construction Equipment Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 2: Global India Construction Equipment Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 3: Global India Construction Equipment Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 4: Global India Construction Equipment Revenue Billion Forecast, by Power Output Rating 2020 & 2034
Table 5: Global India Construction Equipment Revenue Billion Forecast, by Ownership Model 2020 & 2034
Table 6: Global India Construction Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 7: Global India Construction Equipment Revenue Billion Forecast, by Region 2020 & 2034
Table 8: South India India Construction Equipment Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 9: South India India Construction Equipment Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 10: South India India Construction Equipment Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 11: South India India Construction Equipment Revenue Billion Forecast, by Power Output Rating 2020 & 2034
Table 12: South India India Construction Equipment Revenue Billion Forecast, by Ownership Model 2020 & 2034
Table 13: South India India Construction Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 14: South India India Construction Equipment Revenue Billion Forecast, by Country 2020 & 2034
Table 15: North India India Construction Equipment Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 16: North India India Construction Equipment Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 17: North India India Construction Equipment Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 18: North India India Construction Equipment Revenue Billion Forecast, by Power Output Rating 2020 & 2034
Table 19: North India India Construction Equipment Revenue Billion Forecast, by Ownership Model 2020 & 2034
Table 20: North India India Construction Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 21: North India India Construction Equipment Revenue Billion Forecast, by Country 2020 & 2034
Table 22: West India India Construction Equipment Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 23: West India India Construction Equipment Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 24: West India India Construction Equipment Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 25: West India India Construction Equipment Revenue Billion Forecast, by Power Output Rating 2020 & 2034
Table 26: West India India Construction Equipment Revenue Billion Forecast, by Ownership Model 2020 & 2034
Table 27: West India India Construction Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 28: West India India Construction Equipment Revenue Billion Forecast, by Country 2020 & 2034
Table 29: East India India Construction Equipment Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 30: East India India Construction Equipment Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 31: East India India Construction Equipment Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 32: East India India Construction Equipment Revenue Billion Forecast, by Power Output Rating 2020 & 2034
Table 33: East India India Construction Equipment Revenue Billion Forecast, by Ownership Model 2020 & 2034
Table 34: East India India Construction Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 35: East India India Construction Equipment Revenue Billion Forecast, by Country 2020 & 2034
Table 36: North-East India India Construction Equipment Revenue Billion Forecast, by Equipment Type 2020 & 2034
Table 37: North-East India India Construction Equipment Revenue Billion Forecast, by Drive Type 2020 & 2034
Table 38: North-East India India Construction Equipment Revenue Billion Forecast, by End-User Industry 2020 & 2034
Table 39: North-East India India Construction Equipment Revenue Billion Forecast, by Power Output Rating 2020 & 2034
Table 40: North-East India India Construction Equipment Revenue Billion Forecast, by Ownership Model 2020 & 2034
Table 41: North-East India India Construction Equipment Revenue Billion Forecast, by Application 2020 & 2034
Table 42: North-East India India Construction Equipment Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the India construction equipment market size?
Our proprietary research values the India construction equipment market at USD 9.24 billion in 2026, rising to USD 9.98 billion in 2027 and USD 14.46 billion by 2032, growing at a 7.70% CAGR over 2027-2032.
2Which equipment type dominates the India construction equipment market?
Earthmoving equipment held a 56.26% market share in 2026, while road construction equipment is forecast to grow fastest at a 9.75% CAGR over 2027-2032.
3Which region leads India's construction equipment market?
South India held a 32.04% market share in 2026, while North-East India is forecast to grow fastest at a 12.3% CAGR through 2032.
4What is driving demand for construction equipment in India?
Government-led mega infrastructure under the National Infrastructure Pipeline contributes roughly +3% to CAGR, supplemented by Bharatmala corridor execution, mining reforms centred on Jharkhand, and Tier II/III urbanization.
5Which segment is the fastest-growing by drive type?
Electric and hybrid equipment is forecast to lead growth at a 15.2% CAGR over 2027-2032, although conventional diesel units still accounted for 94.35% of the market in 2026.
6Who are the major players in the India construction equipment market?
JCB India Ltd., Caterpillar Inc., Komatsu India Pvt. Ltd., Volvo Construction Equipment India, and Tata Hitachi Construction Machinery Co. Pvt. Ltd. anchor the competitive landscape.
7What is the role of equipment rental in India's construction equipment market?
Contractor-owned equipment represented 70.27% of the market in 2026, but rental fleets are forecast to grow fastest at a 12.3% CAGR, expanding access for SME contractors.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% of research effort dedicated to primary research, encompassing structured interviews and surveys with OEM executives, dealership principals, rental fleet operators, and EPC procurement heads across South, North, West, East, and North-East India.
Engaged four specific company types in the value chain: hydraulic excavator and earthmoving OEMs, road construction equipment manufacturers, equipment rental fleet operators, and construction component and attachment suppliers.
Interviewed specific stakeholder job titles including Procurement Director (EPC contractors), Fleet Manager (rental operators), Head of Sales (OEM dealerships), and Project Equipment Engineer (infrastructure developers).
Consulted recognized industry bodies including the Indian Construction Equipment Manufacturers Association (ICEMA), the National Highways Authority of India (NHAI), and the Ministry of Coal for production and project-execution benchmarks.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
32%
Fleet Manager
26%
Head of Sales (OEM Dealership)
24%
Project Equipment Engineer
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Earthmoving & Excavator OEMs
38%
Road Construction Equipment Manufacturers
22%
Equipment Rental Fleet Operators
20%
Component & Attachment Suppliers
12%
Concrete & Material Handling Equipment OEMs
8%
Secondary Research & Industry Benchmarking
20-30% of research effort anchored in secondary validation from official multilateral sources including UN Comtrade, the World Bank WITS trade database (HS 843050 and HS 843069), and NITI Aayog infrastructure dashboards.
Financial and corporate data cross-referenced via Bloomberg, Factiva, Hoovers, and PitchBook for OEM revenue, capex, and localized manufacturing investment benchmarks.
Regulatory and standards benchmarking against statutory emission norms and safety guidelines published by official .gov and .org portals, ensuring full alignment with Indian homologation requirements.
Demand Modeling & Market Estimation
Simultaneous top-down and bottom-up methodologies, validated via multi-level data triangulation between ICEMA shipment volumes, PAIMANA-monitored project counts (1,731 Central Sector projects), and OEM revenue disclosures.
Four specific quantitative metrics embedded in the bottom-up calculation: unit shipments by power band (101-200 HP, above 400 HP), end-user capex allocation ratios (infrastructure 42.6%, mining and quarrying), contractor-owned versus rental fleet splits (70.27% vs. 29.73%), and export/import unit values from UN Comtrade trade data.
Segmentation modeled across equipment type, drive type, end-user industry, power output rating, ownership model, and five geographic divisions, with CAGR attributed to driver impact analyses.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85-90%, achieved through multi-level triangulation and cross-validation of primary interview responses against official trade statistics.
Every report is updated to the date of purchase, incorporating the latest quarterly shipment actuals and project execution data.
Outlier screening and consistency checks performed across regional shares (South India at 32.04%, North-East at 9.25%) to ensure geographic totals reconcile with national market values.
Independent Intelligence for decisions that move markets
The global residential real estate market is valued at USD 11.6 trillion in 2026 and is projected to reach USD 15.53 trillion by 2031, growing at a 6.05% CAGR.
Nov 2026|243 pages
$2900.00
Post-construction cleaning demand patterns: a $24.6B niche growing at 7.4% CAGR to 2035, driven by handover cycles, green certification and labor shifts.
Nov 2026|241 pages
$2900.00
Home elevator installation service market to reach $6.5B by 2036 at 5.5% CAGR, driven by retrofit demand and aging population trends.