1What is the size of the Spain office real estate market?
The Spain office real estate market is valued at USD 40.65 billion in 2026, up from USD 39.01 billion in 2025, and is forecast to reach USD 49.94 billion by 2031.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Spain Office Real Estate Market
 by Building Grade (Grade A, Grade B, Grade C), by Transaction Type (Rental, Sales), by End Use (Information Technology (IT & ITES), BFSI, Business Consulting & Professional Services, Other Services (Retail, Lifesciences, Energy, Legal)), by City (Madrid, Barcelona, Valencia, Rest of Spain), by Madrid, by Barcelona, by Valencia, by Rest of Spain Forecast 2026-2034

Research Analyst


 Related Reports

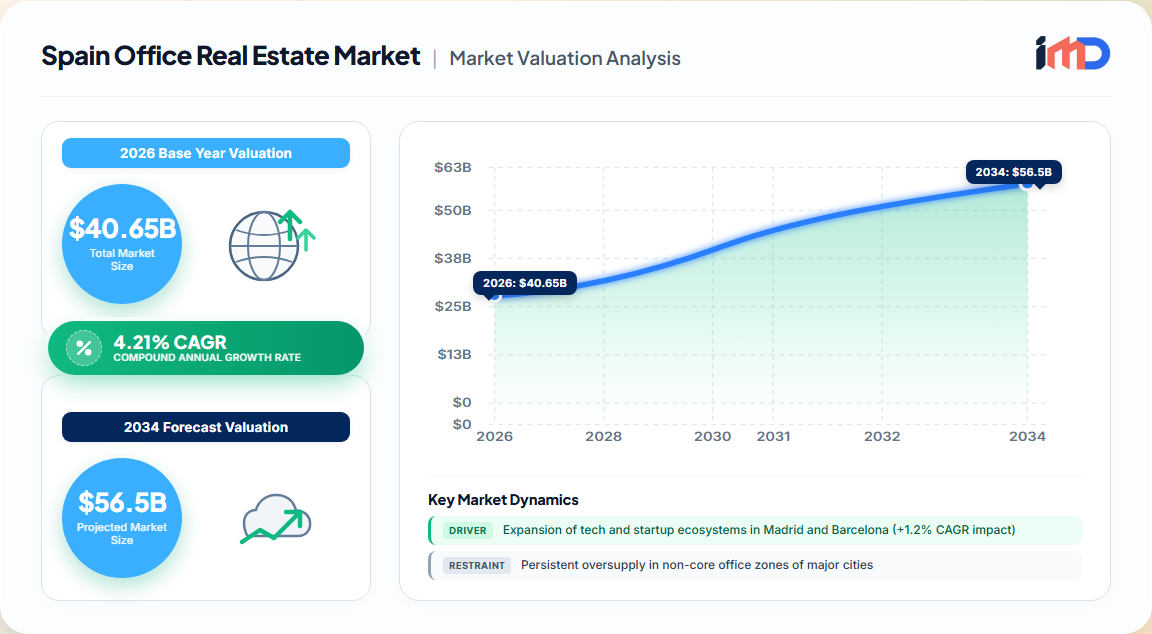
The Spain office real estate market is valued at USD 40.65 billion in 2026, expanding from USD 39.01 billion in 2025, and is projected to reach USD 49.94 billion by 2031 at a 4.21% CAGR over the 2026–2031 forecast window. Our proprietary demand modeling indicates the sector has entered a structurally bifurcated phase: prime, ESG-certified Grade A space is in acute scarcity, while secondary stock faces accelerating obsolescence.
Spain's positioning as a cost-competitive gateway into both the EU and Latin America, combined with political stability and a technology economy generating more than USD 129.6 billion in 2024 (employing 764,000 people), underpins durable occupier demand. Venture capital inflows surpassed USD 3.24 billion in 2024, supported by 2022 Startup Law incentives and a network of 300-plus incubators, feeding a pipeline of scale-ups that graduate into long-lease Grade A occupiers.
The market remains low-concentration, with no single landlord or operator controlling a dominant share. Domestic SOCIMIs and institutional platforms compete against global advisory and investment houses for a limited pool of certified prime assets.
Our primary interviews with occupiers and asset managers identify five quantifiable growth levers, each carrying a modeled impact on the forecast CAGR:
| Driver | Impact on CAGR | Geographic Relevance | Timeline |
|---|---|---|---|
| Expansion of tech and startup ecosystems | +1.2% | Madrid, Barcelona, Valencia spillover | Medium term (2–4 yrs) |
| Nearshoring of IT and shared service centers | +0.8% | Madrid, Barcelona, Valencia | Long term (≥4 yrs) |
| Surge in flexible workspaces and hybrid models | +0.9% | National, major urban centers | Short term (≤2 yrs) |
| Institutional focus on ESG-compliant assets | +0.7% | Madrid, Barcelona prime zones | Medium term (2–4 yrs) |
| Government incentives for energy-efficient retrofits | +0.6% | National, large cities | Long term (≥4 yrs) |
The single greatest drag on the Spain office real estate market is the persistent oversupply in non-core zones. Madrid's city-wide vacancy stood at 9% in 2024 and moderated to 10.2% in 2026, yet prime CBD availability remained tight at 3.2%. Barcelona's city-wide vacancy fell to 13.5%, but dropped to 4.1% in the CBD and just 1.0% in Grade A assets.
Grade A assets captured 53.60% of market share in 2025, and are forecast to grow at a 4.52% CAGR to 2031. Grade B stock is projected to post the fastest 4.58% CAGR, driven by value-add repositioning. Prime rents reached USD 41.0/m²/month in Madrid and USD 32.1/m²/month in Barcelona. Portfolio evidence underscores the premium: all-green Grade A strategies delivered 95% occupancy and 6.3% rental uplift in 2024, outpacing the broader market.
Rental transactions dominated with 78.30% of revenue in 2025, reflecting occupier preference for flexible lease structures. Sales transactions are forecast to grow at a 4.73% CAGR, supported by the investment recovery that pushed H1 2026 office investment to EUR 1.6 billion, 37% above the prior year and broadly in line with H1 2019 levels.
Information technology and IT-enabled services captured 32.70% of demand in 2025 and are set to expand at a 4.92% CAGR — the fastest of any vertical. BFSI, business consulting, and professional services follow, with retail, life sciences, energy, and legal occupiers rounding out demand.
Madrid commanded 41.40% of total activity in 2025, while Valencia is forecast to witness the highest 5.12% CAGR to 2031.
| City | 2025 Activity Share | Forecast CAGR to 2031 |
|---|---|---|
| Madrid | 41.40% | 4.4% |
| Barcelona | ~32% | 4.6% |
| Valencia | ~13% | 5.12% |
| Rest of Spain | ~13% | 3.8% |
The Spain office real estate market features a low concentration ratio, with advisory, investment, and development roles often held by distinct players. Leading market participants include CBRE, Jones Lang LaSalle, Savills, Cushman & Wakefield, Knight Frank, Merlin Properties, Colonial, GMP Property, Torre Rioja, BNP Paribas Real Estate Spain, Grupo Lar, Inmobiliaria del Sur, Acciona Inmobiliaria, FCC, ACS, Dragados, OHLA, Avintia Grupo, Aedas Homes, and Globalvia.
Key strategic patterns observed in our proprietary deal-tracking:
The Spain office real estate value chain spans land assembly through to occupier fit-out, with ES G compliance now a cross-cutting requirement at every stage.
While office real estate is not a tradable commodity, cross-border capital and corporate mobility function as the sector's equivalent trade flows. Spain's merchandise trade reached 72.19% of GDP in 2023, with goods exports of USD 419.6 billion and imports of USD 457.1 billion (World Bank WITS), evidencing the open-economy backdrop that attracts service-center nearshoring.
Madrid and Barcelona remain the anchor markets, together representing the overwhelming majority of investment and take-up. Madrid's H1 2026 take-up reached 205,000 sqm, constrained by quality-product scarcity rather than demand weakness. Barcelona exceeded 176,000 sqm in H1 2026, up 12% year on year.
Valencia emerges as the highest-growth secondary market at a 5.12% CAGR, with requests for units above 1,000 m² rising sharply in 2024, led by technology occupiers seeking plug-and-play layouts.
Looking to 2031, the outlook remains favorable: strong demand for quality buildings, limited prime supply in established locations, and recovering investment activity reinforce sector appeal. The best-positioned assets will continue attracting both occupier demand and investor interest, while unretrofitted secondary stock faces a widening performance gap.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.21% from 2020-2034 |
| Segmentation |
|
By End Use
By City
| By Geography |
|
The Spain office real estate market is valued at USD 40.65 billion in 2026, up from USD 39.01 billion in 2025, and is forecast to reach USD 49.94 billion by 2031.
The market is projected to grow at a 4.21% CAGR over the 2026–2031 forecast period, with Grade B stock posting the fastest building-grade growth at 4.58%.
Madrid commanded 41.40% of total market activity in 2025, while Valencia is forecast to record the highest CAGR at 5.12% through 2031.
Information technology and IT-enabled services captured 32.70% of demand in 2025 and are set to expand at a 4.92% CAGR, the fastest of any vertical.
Leading participants include CBRE, Jones Lang LaSalle, Savills, Cushman & Wakefield, Knight Frank, Merlin Properties, Colonial, GMP Property, and BNP Paribas Real Estate Spain, in a market with low concentration.
Grade A assets held 53.60% of market share in 2025 because modern specifications match hybrid-work requirements and rising ESG standards, with CBD vacancy under 5% and prime Madrid rents at USD 41.0/m²/month.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Head of Real Estate | 35% |
| Chief Investment Officer | 25% |
| Head of Workplace Strategy | 22% |
| Leasing Director | 18% |
| Company Type | Representation (%) |
|---|---|
| SOCIMIs and Institutional Asset Managers | 30% |
| Office Developers and General Contractors | 25% |
| Commercial Leasing Advisory and Brokerage Houses | 20% |
| Architectural and ESG Retrofit Engineering Firms | 15% |
| Flexible Workspace Operators | 10% |