About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailSouth Africa Freight and Logistics Industry
Logistics / MARKET REPORT

South Africa Freight and Logistics Industry | Insight Market Data

South Africa Freight and Logistics Industry by By Logistics Function (Freight Transport, Freight Forwarding, Warehousing & Storage, Courier Express & Parcel Services, Contract Logistics & 3PL, Customs Brokerage & Trade Facilitation, Value-Added & Project Logistics), by By Mode of Transport (Road Freight, Rail Freight, Sea Freight, Air Freight, Pipelines), by By Shipment Coverage (Domestic, Southern African Cross-Border, Intercontinental), by By End-User Industry (Manufacturing, Wholesale & Retail Trade, Mining & Minerals, Agriculture Fishing & Forestry, Automotive, Food Beverage & FMCG, Healthcare & Pharmaceuticals, Chemicals & Petrochemicals, Construction, Technology Textiles & Packaging), by Gauteng, by Western Cape, by KwaZulu-Natal, by Mpumalanga, by Eastern Cape, by Other Provinces Forecast 2026-2034
© Nov 11, 2026|Base Year: 2025|244 Pages
Sakshi Chavan

Sakshi Chavan

Research Associate

Main Logo

South Africa Freight and Logistics Industry Market Report 2032


/
/
Home
Industries
Logistics
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Author
Sakshi Chavan

Sakshi Chavan

Research Associate

As a Research Associate specializing in the Logistics sector, I am a strategic consulting professional passionate about helping organizations navigate complex market environments through data-driven decisions. In my role, I lead market research reports and strategic engagements, delivering actionable business intelligence and end-to-end report writeups. My core expertise lies in industry analysis, competitive benchmarking, trend analysis, and opportunity assessment tailored to evolving market conditions. I collaborate closely with businesses to transform complex data into clear, high-impact insights that solve critical challenges and drive long-term growth strategies.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 11, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Egypt Cold Chain Logistics Market Size, Trends & Forecast 2031

Egypt cold chain logistics market at USD 1.02 Billion in 2024, growing at 12.8% CAGR to 2032, driven by pharma, food exports & Suez hub expansion.

Nov 2026|264 pages
$2900.00View report

Indonesia CEP market: USD 8.42 Billion in 2026, growing at 7.16% CAGR to USD 11.91 Billion by 2031. E-commerce and automation drive growth.

Nov 2026|180 pages
$2900.00

The bonded warehouse services market is valued at USD 19.9 billion in 2026, projected to reach USD 38.4 billion by 2036 at a 6.8% CAGR.

Nov 2026|276 pages
$2900.00

India domestic CEP market valued at USD 6.27 billion in 2026, growing at 10.34% CAGR to reach USD 10.25 billion by 2031. Get full analysis.

Nov 2026|188 pages
$2900.00
Indonesia CEP Market Size, Growth & Forecast 2026-2031
View report
Bonded Warehouse Services Market | 2036 Forecast & CAGR
View report
India Domestic CEP Market Size, Growth & Forecast 2026-2031
View report
South Africa Freight and Logistics Industry CAGR, market size, market share

Executive Overview: The State of South African Freight and Logistics

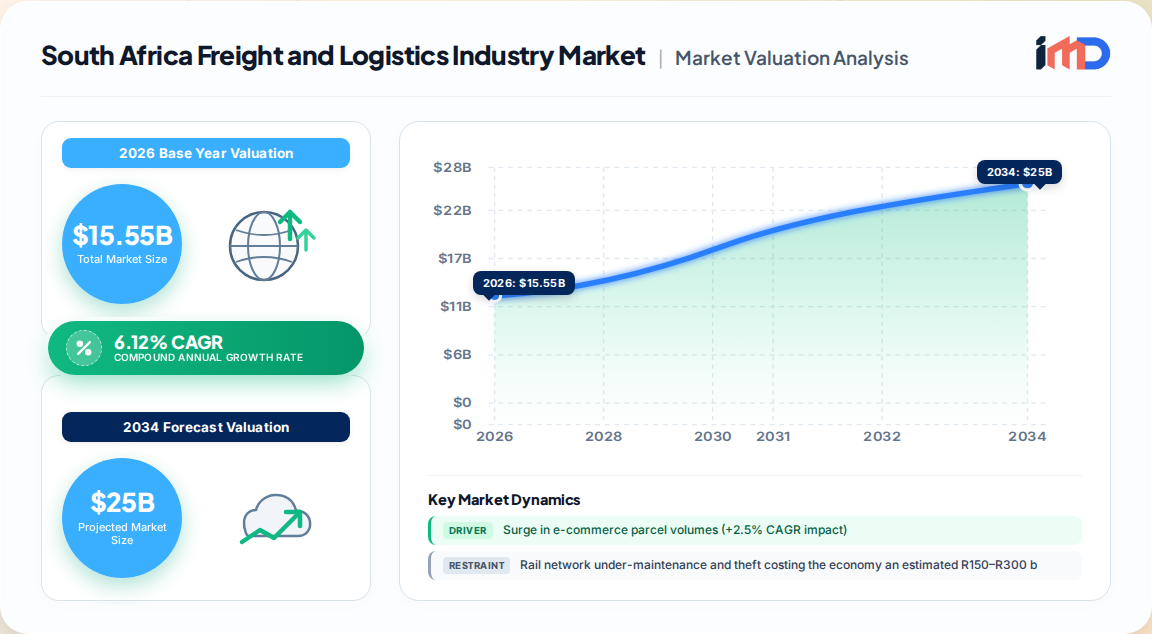
South Africa's freight and logistics industry remains the most sophisticated and structurally mature logistics system in sub-Saharan Africa, and our proprietary modelling places the market at USD 15.55 billion in 2026, advancing to USD 16.45 billion in 2027 and USD 22.14 billion by 2032 — a CAGR of 6.12% across the 2027–2032 forecast window. Roughly 4.3% year-on-year output growth in the broader logistics economy, with the sector generating in excess of half a trillion rand in annual economic output, underlines its role as the circulatory system of the national economy.

South Africa Freight and Logistics Industry Market Size (In Billion)

25.0B
20.0B
15.0B
10.0B
5.0B
0
14.65 B
2025
15.55 B
2026
16.50 B
2027
17.51 B
2028
18.58 B
2029
19.72 B
2030
20.93 B
2031
Main Logo

The market is in the middle of a once-in-a-generation structural transition. State-dominated rail and port assets are being progressively opened to contracted private operators, while demand-side pressure from e-commerce, cold-chain agro-exports and AfCFTA-driven cross-border flows is reshaping service expectations.

Metric Value
Market size, 2026 (base year) USD 15.55 Billion
Market size, 2027 USD 16.45 Billion
Market size, 2032 (forecast) USD 22.14 Billion
CAGR, 2027–2032 6.12%
Market concentration Medium
Largest end-user segment (2026) Manufacturing (37.39% share)
Fastest-growing end-user segment Wholesale & Retail Trade (6.75% CAGR)
Largest logistics function (2026) Freight Transport (73.6% share)
Fastest-growing function Courier, Express & Parcel (7.25% CAGR)
Leading province (2025) Gauteng (34.7% of activity)

South Africa's trade architecture anchors this demand: annual merchandise exports of roughly USD 116.4 billion against imports of USD 104.9 billion (2025), with trade equivalent to approximately 65% of GDP. South Africa ranked joint 19th of 139 countries on the World Bank Logistics Performance Index — a 14-place improvement — placing its infrastructure quality in the same conversation as China and the United States.

Demand Drivers and Quantified Growth Impact

Our driver attribution modelling isolates six forces, each mapped to a measurable CAGR contribution.

Driver CAGR Impact Timeline
Surge in e-commerce parcel volumes +2.5% Short term (≤2 years)
Public-private partnerships for rail revamp +2.2% Medium term (2–4 years)
Cold-chain demand from agro-exports +1.7% Short term (≤2 years)
Growing intra-Africa trade under AfCFTA +1.3% Medium term (2–4 years)
Adoption of freight visibility platforms +0.7% Medium term (2–4 years)
OEM shift to alternative-fuel truck fleets +0.3% Long term (≥4 years)
  • E-commerce parcel intensity: Network parcel volumes rose more than 26% year on year across November–December 2025, with December alone up nearly 40%. This peak concentration forces carriers to size networks for a trading window that strains last-mile capacity for the remaining ten months.
  • Cold-chain scale: South African growers exported roughly 203 million 15-kg cartons of citrus in 2025, moving in more than 120,000 reefer containers to over 100 destinations. Container availability, loading sequencing and departure coordination are now as commercially decisive as transport capacity itself.
  • Private rail access: All 11 train operating companies allocated slots on the national freight network concluded rail-access agreements in May 2026. Early private entrants have signalled first-year movements in the order of 288,000 metric tons on individual corridor allocations.
  • AfCFTA operationalisation: All rules of origin — including autos, clothing and textiles — were finalised and reported to Parliament in June 2026, giving exporters a concrete preferential-trade framework.

Restraints, Constraints and Risk Quantification

  • Rail under-maintenance and theft (-1.1% CAGR impact): Ageing infrastructure, cable theft and vandalism impose an estimated R150–R300 billion annual cost on the economy. An estimated 16% of iron ore, 12% of coal and 24% of other mining export volumes are stranded off rail and diverted to road.
  • Chronic port congestion and equipment age (-0.9%): Durban Container Terminal Pier 2 handles over 65% of Port of Durban throughput and roughly 40% of national port traffic, meaning small crane and yard productivity gains translate into outsized national effects.
  • Driver shortage and labour cost inflation (-0.4%): Road freight carries approximately 85% of land freight, concentrating exposure to wage pressure and chronic driver shortfalls.
  • Currency volatility (-0.2%): Rand weakness inflates imported fleet, fuel and equipment costs, compressing operator margins and deferring capital renewal.

Segmentation Analysis: Functions and End-User Industries

Freight transport accounted for 73.6% of market value in 2026, reflecting the structural dominance of road haulage for inland movement. Courier, Express and Parcel is the fastest-growing function at 7.25% CAGR, while warehousing and value-added services are expanding fastest on a proportional basis, driven by e-commerce fulfilment, customs compliance and cold-chain complexity.

End-User Industry 2026 Share / Growth
Manufacturing 37.39% share — largest segment
Wholesale & Retail Trade 6.75% CAGR — fastest growing
Mining & Minerals High-volume bulk corridor demand
Agriculture & Agro-Processing Fastest-growing on refrigerated intensity
Automotive Corridor-stable component flows
Food, Beverage & FMCG Cold-chain and modern facility demand
Healthcare & Pharmaceuticals Time-critical, temperature-controlled

Warehousing is shifting from passive storage to technology-intensive operations. Prime industrial rent averaged around R100 per square metre in 2025 with yields near 8.25%, and institutional capital is concentrated in a JSE-listed logistics REIT universe holding 59 logistics properties valued near R30 billion. Large-format facilities of 30,000 square metres and above cluster along the N1 and N3 corridors, with Johannesburg housing the densest concentration nationally.

Regional Outlook: Provincial Concentration and Corridor Logic

Gauteng contributed 34.7% of national freight and logistics activity in 2025, anchored by OR Tambo International Airport's international cargo connectivity and the City Deep, Isando and Jet Park warehousing clusters serving inland distribution. The Western Cape follows at 19.6%, with Cape Town's harbour-adjacent industrial nodes oriented toward export markets.

South Africa Freight and Logistics Industry Regional Market Share

Loading chart...
Main Logo
Province Activity Share Primary Logistics Role
Gauteng 34.7% Inland distribution, air cargo, fulfilment
Western Cape 19.6% Export-oriented warehousing, cold chain, agriculture
KwaZulu-Natal ~18% Port gateway (Durban), automotive corridor
Mpumalanga ~10% Bulk mining and agricultural hinterland
Eastern Cape ~8% Automotive components and port feeder flows

KwaZulu-Natal's trajectory is tied directly to the Durban Gateway Terminal transaction, valued at R10.5 billion, with a further R11 billion of investment anticipated and a planned 45% increase in export capacity.

Competitive Landscape and Strategic Positioning

The market is assessed as medium concentration, with state-owned network ownership coexisting alongside a highly competitive private operating layer that includes no single dominant player.

  • Transnet SOC Ltd — owner-operator of rail and seaport assets, returned to profit for the first time in four years as volumes rose to roughly 168 million tonnes from 160.1 million tonnes.
  • DP World (including Imperial Logistics) — turnkey automotive logistics model spanning distribution, regulatory compliance and digital dealer support across 25+ countries and 25,000+ employees.
  • A.P. Moller – Maersk — developing cold storage at Belcon Logistics Park in Cape Town and a sustainability-focused cold store at Cato Ridge.
  • DSV A/S (including DB Schenker), Kuehne+Nagel, DHL Group — integrated global forwarding and contract logistics networks.
  • Domestic courier specialists — The Courier Guy, Fastway Couriers, RAM Hand-to-Hand Couriers and City Logistics compete aggressively in last-mile and cross-border e-commerce parcels.

Differentiation increasingly hinges on the ability to orchestrate a shipper's cargo across road transport, port handling and cold storage simultaneously. Providers whose delivery and cold-storage arrangements can absorb a delayed rail or terminal stage protect fulfilment for online retailers and citrus exporters — a capability that converts operational resilience into pricing power.

Global Trade Analysis & Supply Chain Risk Assessment

South Africa's trade profile is diversified rather than concentrated, with a Hirschman-Herfindahl index of 0.07 and an export market penetration index of 14.46. Imports and exports of goods and services each represent roughly 32.4% and 32.8% of GDP, with services exports of USD 14.5 billion and services imports of USD 18.8 billion.

The Freight Logistics Roadmap, the National Logistics Crisis Committee and the Economic Regulation of Transport Act collectively create an independent Transport Economic Regulator empowered to set fair tariffs in ports and rail. Alongside this sits a R1 trillion infrastructure investment programme, including R93.1 billion for national road maintenance and R66.3 billion for passenger rail improvement.

Principal supply chain risks include mode concentration on road, single-node dependence on Durban for container throughput, energy and fuel price volatility, and skills scarcity in logistics management. Mitigation is visible in corridor diversification toward Maputo and Ngqura, dry port development, and bonded cross-border transit investment.

Strategic White-Space and Investment Opportunity Assessment

  • Temperature-controlled capacity remains the highest-conviction white space, given reefer intensity in citrus and deciduous fruit and the continent's largest, most mature cold-chain storage base.
  • Private rail operating models combining contracted network access with owned rolling stock and completed operating arrangements represent a first-mover opportunity ahead of early-2027 service commencement.
  • Digital freight platforms and visibility layers carry a +0.7% CAGR contribution, with mobile load-matching improving truck utilisation and reducing empty running.
  • Automated fulfilment and smart warehousing — exemplified by a 14,000 square metre AI-monitored, solar-powered facility in Johannesburg — signals the direction of capital deployment.
  • AfCFTA-corridor bonded logistics for autos, clothing and textiles offers defined-origin exporters a concrete framework that logistics providers can monetise through transnational warehousing.

South Africa Freight and Logistics Industry Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

South Africa Freight and Logistics Industry REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2026
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 6.12% from 2020-2034
Segmentation
  • By Logistics Function

    • Freight Transport
    • Freight Forwarding
    • Warehousing & Storage
    • Courier Express & Parcel Services
    • Contract Logistics & 3PL

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Surge in e-commerce parcel volumes (+2.5% CAGR impact)
      • 3.1.2. Public-private partnerships for rail revamp (+2.2% CAGR impact)
      • 3.1.3. Cold-chain demand from agro-exports (+1.7% CAGR impact)
      • 3.1.4. Growing intra-Africa trade under AfCFTA (+1.3% CAGR impact)
    • 3.2. Market Trends
      • 3.2.1. Private rail access agreements with 11 train operating companies adding roughly 24 million tonnes of capacity
      • 3.2.2. E-commerce peak parcel volumes rising over 26% year on year, with December up nearly 40%
      • 3.2.3. Cold-chain expansion driven by citrus exports of 203 million 15-kg cartons in over 120,000 reefer containers
      • 3.2.4. Warehousing shifting from passive storage to automation, AI monitoring and solar-powered fulfilment
    • 3.3. Market Restrains
      • 3.3.1. Rail network under-maintenance and theft costing the economy an estimated R150–R300 billion annually
      • 3.3.2. Chronic port congestion and ageing equipment at Durban and Cape Town
      • 3.3.3. Driver shortage and rising labour costs across road freight
      • 3.3.4. Currency volatility inflating imported fleet and fuel costs
  • Customs Brokerage & Trade Facilitation
  • Value-Added & Project Logistics
  • By Mode of Transport

    • Road Freight
    • Rail Freight
    • Sea Freight
    • Air Freight
    • Pipelines
  • By Shipment Coverage

    • Domestic
    • Southern African Cross-Border
    • Intercontinental
  • By End-User Industry

    • Manufacturing
    • Wholesale & Retail Trade
    • Mining & Minerals
    • Agriculture Fishing & Forestry
    • Automotive
    • Food Beverage & FMCG
    • Healthcare & Pharmaceuticals
    • Chemicals & Petrochemicals
    • Construction
    • Technology Textiles & Packaging
  • By Geography
    • Gauteng

    • Western Cape

    • KwaZulu-Natal

    • Mpumalanga

    • Eastern Cape

    • Other Provinces

  • 3.4. Market Restraints
    • 3.4.1. Rail network under-maintenance and theft costing the economy an estimated R150–R300 billion annually
    • 3.4.2. Chronic port congestion and ageing equipment at Durban and Cape Town
    • 3.4.3. Driver shortage and rising labour costs across road freight
    • 3.4.4. Currency volatility inflating imported fleet and fuel costs
  • 3.5. Market Challenges
    • 3.5.1. Structural mode imbalance with road carrying approximately 85% of land freight
    • 3.5.2. Skills shortage in logistics management and supply chain planning
    • 3.5.3. Energy insecurity and fuel supply volatility
    • 3.5.4. Cross-border regulatory fragmentation and border dwell times
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 5.1.1. Freight Transport
      • 5.1.2. Freight Forwarding
      • 5.1.3. Warehousing & Storage
      • 5.1.4. Courier Express & Parcel Services
      • 5.1.5. Contract Logistics & 3PL
      • 5.1.6. Customs Brokerage & Trade Facilitation
      • 5.1.7. Value-Added & Project Logistics
    • 5.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 5.2.1. Road Freight
      • 5.2.2. Rail Freight
      • 5.2.3. Sea Freight
      • 5.2.4. Air Freight
      • 5.2.5. Pipelines
    • 5.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 5.3.1. Domestic
      • 5.3.2. Southern African Cross-Border
      • 5.3.3. Intercontinental
    • 5.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 5.4.1. Manufacturing
      • 5.4.2. Wholesale & Retail Trade
      • 5.4.3. Mining & Minerals
      • 5.4.4. Agriculture Fishing & Forestry
      • 5.4.5. Automotive
      • 5.4.6. Food Beverage & FMCG
      • 5.4.7. Healthcare & Pharmaceuticals
      • 5.4.8. Chemicals & Petrochemicals
      • 5.4.9. Construction
      • 5.4.10. Technology Textiles & Packaging
    • 5.5. Market Analysis, Insights and Forecast - by Region
      • 5.5.1. Gauteng
      • 5.5.2. Western Cape
      • 5.5.3. KwaZulu-Natal
      • 5.5.4. Mpumalanga
      • 5.5.5. Eastern Cape
      • 5.5.6. Other Provinces
  • 6. Gauteng Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 6.1.1. Freight Transport
      • 6.1.2. Freight Forwarding
      • 6.1.3. Warehousing & Storage
      • 6.1.4. Courier Express & Parcel Services
      • 6.1.5. Contract Logistics & 3PL
      • 6.1.6. Customs Brokerage & Trade Facilitation
      • 6.1.7. Value-Added & Project Logistics
    • 6.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 6.2.1. Road Freight
      • 6.2.2. Rail Freight
      • 6.2.3. Sea Freight
      • 6.2.4. Air Freight
      • 6.2.5. Pipelines
    • 6.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 6.3.1. Domestic
      • 6.3.2. Southern African Cross-Border
      • 6.3.3. Intercontinental
    • 6.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 6.4.1. Manufacturing
      • 6.4.2. Wholesale & Retail Trade
      • 6.4.3. Mining & Minerals
      • 6.4.4. Agriculture Fishing & Forestry
      • 6.4.5. Automotive
      • 6.4.6. Food Beverage & FMCG
      • 6.4.7. Healthcare & Pharmaceuticals
      • 6.4.8. Chemicals & Petrochemicals
      • 6.4.9. Construction
      • 6.4.10. Technology Textiles & Packaging
  • 7. Western Cape Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 7.1.1. Freight Transport
      • 7.1.2. Freight Forwarding
      • 7.1.3. Warehousing & Storage
      • 7.1.4. Courier Express & Parcel Services
      • 7.1.5. Contract Logistics & 3PL
      • 7.1.6. Customs Brokerage & Trade Facilitation
      • 7.1.7. Value-Added & Project Logistics
    • 7.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 7.2.1. Road Freight
      • 7.2.2. Rail Freight
      • 7.2.3. Sea Freight
      • 7.2.4. Air Freight
      • 7.2.5. Pipelines
    • 7.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 7.3.1. Domestic
      • 7.3.2. Southern African Cross-Border
      • 7.3.3. Intercontinental
    • 7.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 7.4.1. Manufacturing
      • 7.4.2. Wholesale & Retail Trade
      • 7.4.3. Mining & Minerals
      • 7.4.4. Agriculture Fishing & Forestry
      • 7.4.5. Automotive
      • 7.4.6. Food Beverage & FMCG
      • 7.4.7. Healthcare & Pharmaceuticals
      • 7.4.8. Chemicals & Petrochemicals
      • 7.4.9. Construction
      • 7.4.10. Technology Textiles & Packaging
  • 8. KwaZulu-Natal Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 8.1.1. Freight Transport
      • 8.1.2. Freight Forwarding
      • 8.1.3. Warehousing & Storage
      • 8.1.4. Courier Express & Parcel Services
      • 8.1.5. Contract Logistics & 3PL
      • 8.1.6. Customs Brokerage & Trade Facilitation
      • 8.1.7. Value-Added & Project Logistics
    • 8.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 8.2.1. Road Freight
      • 8.2.2. Rail Freight
      • 8.2.3. Sea Freight
      • 8.2.4. Air Freight
      • 8.2.5. Pipelines
    • 8.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 8.3.1. Domestic
      • 8.3.2. Southern African Cross-Border
      • 8.3.3. Intercontinental
    • 8.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 8.4.1. Manufacturing
      • 8.4.2. Wholesale & Retail Trade
      • 8.4.3. Mining & Minerals
      • 8.4.4. Agriculture Fishing & Forestry
      • 8.4.5. Automotive
      • 8.4.6. Food Beverage & FMCG
      • 8.4.7. Healthcare & Pharmaceuticals
      • 8.4.8. Chemicals & Petrochemicals
      • 8.4.9. Construction
      • 8.4.10. Technology Textiles & Packaging
  • 9. Mpumalanga Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 9.1.1. Freight Transport
      • 9.1.2. Freight Forwarding
      • 9.1.3. Warehousing & Storage
      • 9.1.4. Courier Express & Parcel Services
      • 9.1.5. Contract Logistics & 3PL
      • 9.1.6. Customs Brokerage & Trade Facilitation
      • 9.1.7. Value-Added & Project Logistics
    • 9.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 9.2.1. Road Freight
      • 9.2.2. Rail Freight
      • 9.2.3. Sea Freight
      • 9.2.4. Air Freight
      • 9.2.5. Pipelines
    • 9.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 9.3.1. Domestic
      • 9.3.2. Southern African Cross-Border
      • 9.3.3. Intercontinental
    • 9.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 9.4.1. Manufacturing
      • 9.4.2. Wholesale & Retail Trade
      • 9.4.3. Mining & Minerals
      • 9.4.4. Agriculture Fishing & Forestry
      • 9.4.5. Automotive
      • 9.4.6. Food Beverage & FMCG
      • 9.4.7. Healthcare & Pharmaceuticals
      • 9.4.8. Chemicals & Petrochemicals
      • 9.4.9. Construction
      • 9.4.10. Technology Textiles & Packaging
  • 10. Eastern Cape Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 10.1.1. Freight Transport
      • 10.1.2. Freight Forwarding
      • 10.1.3. Warehousing & Storage
      • 10.1.4. Courier Express & Parcel Services
      • 10.1.5. Contract Logistics & 3PL
      • 10.1.6. Customs Brokerage & Trade Facilitation
      • 10.1.7. Value-Added & Project Logistics
    • 10.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 10.2.1. Road Freight
      • 10.2.2. Rail Freight
      • 10.2.3. Sea Freight
      • 10.2.4. Air Freight
      • 10.2.5. Pipelines
    • 10.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 10.3.1. Domestic
      • 10.3.2. Southern African Cross-Border
      • 10.3.3. Intercontinental
    • 10.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 10.4.1. Manufacturing
      • 10.4.2. Wholesale & Retail Trade
      • 10.4.3. Mining & Minerals
      • 10.4.4. Agriculture Fishing & Forestry
      • 10.4.5. Automotive
      • 10.4.6. Food Beverage & FMCG
      • 10.4.7. Healthcare & Pharmaceuticals
      • 10.4.8. Chemicals & Petrochemicals
      • 10.4.9. Construction
      • 10.4.10. Technology Textiles & Packaging
  • 11. Other Provinces Market Analysis, Insights and Forecast, 2020-2034
    • 11.1. Market Analysis, Insights and Forecast - by Logistics Function
      • 11.1.1. Freight Transport
      • 11.1.2. Freight Forwarding
      • 11.1.3. Warehousing & Storage
      • 11.1.4. Courier Express & Parcel Services
      • 11.1.5. Contract Logistics & 3PL
      • 11.1.6. Customs Brokerage & Trade Facilitation
      • 11.1.7. Value-Added & Project Logistics
    • 11.2. Market Analysis, Insights and Forecast - by Mode of Transport
      • 11.2.1. Road Freight
      • 11.2.2. Rail Freight
      • 11.2.3. Sea Freight
      • 11.2.4. Air Freight
      • 11.2.5. Pipelines
    • 11.3. Market Analysis, Insights and Forecast - by Shipment Coverage
      • 11.3.1. Domestic
      • 11.3.2. Southern African Cross-Border
      • 11.3.3. Intercontinental
    • 11.4. Market Analysis, Insights and Forecast - by End-User Industry
      • 11.4.1. Manufacturing
      • 11.4.2. Wholesale & Retail Trade
      • 11.4.3. Mining & Minerals
      • 11.4.4. Agriculture Fishing & Forestry
      • 11.4.5. Automotive
      • 11.4.6. Food Beverage & FMCG
      • 11.4.7. Healthcare & Pharmaceuticals
      • 11.4.8. Chemicals & Petrochemicals
      • 11.4.9. Construction
      • 11.4.10. Technology Textiles & Packaging
  • 12. Competitive Analysis
    • 12.1. Company Profiles
      • 12.1.1. Transnet SOC Ltd (Transnet Freight Rail)
        • 12.1.1.1. Company Overview
        • 12.1.1.2. Products
        • 12.1.1.3. Company Financials
        • 12.1.1.4. SWOT Analysis
      • 12.1.2. DP World (including Imperial Logistics (Pty) Ltd.)
        • 12.1.2.1. Company Overview
        • 12.1.2.2. Products
        • 12.1.2.3. Company Financials
        • 12.1.2.4. SWOT Analysis
      • 12.1.3. A.P. Moller - Maersk
        • 12.1.3.1. Company Overview
        • 12.1.3.2. Products
        • 12.1.3.3. Company Financials
        • 12.1.3.4. SWOT Analysis
      • 12.1.4. DSV A/S (including DB Schenker)
        • 12.1.4.1. Company Overview
        • 12.1.4.2. Products
        • 12.1.4.3. Company Financials
        • 12.1.4.4. SWOT Analysis
      • 12.1.5. Kuehne+Nagel
        • 12.1.5.1. Company Overview
        • 12.1.5.2. Products
        • 12.1.5.3. Company Financials
        • 12.1.5.4. SWOT Analysis
      • 12.1.6. DHL Group
        • 12.1.6.1. Company Overview
        • 12.1.6.2. Products
        • 12.1.6.3. Company Financials
        • 12.1.6.4. SWOT Analysis
      • 12.1.7. The Courier Guy
        • 12.1.7.1. Company Overview
        • 12.1.7.2. Products
        • 12.1.7.3. Company Financials
        • 12.1.7.4. SWOT Analysis
      • 12.1.8. Fastway Couriers
        • 12.1.8.1. Company Overview
        • 12.1.8.2. Products
        • 12.1.8.3. Company Financials
        • 12.1.8.4. SWOT Analysis
      • 12.1.9. RAM Hand-to-Hand Couriers
        • 12.1.9.1. Company Overview
        • 12.1.9.2. Products
        • 12.1.9.3. Company Financials
        • 12.1.9.4. SWOT Analysis
      • 12.1.10. City Logistics
        • 12.1.10.1. Company Overview
        • 12.1.10.2. Products
        • 12.1.10.3. Company Financials
        • 12.1.10.4. SWOT Analysis
      • 12.1.11. Aramex
        • 12.1.11.1. Company Overview
        • 12.1.11.2. Products
        • 12.1.11.3. Company Financials
        • 12.1.11.4. SWOT Analysis
      • 12.1.12. Equites Property Fund
        • 12.1.12.1. Company Overview
        • 12.1.12.2. Products
        • 12.1.12.3. Company Financials
        • 12.1.12.4. SWOT Analysis
    • 12.2. Market Entropy
      • 12.2.1. Company's Key Areas Served
      • 12.2.2. Recent Developments
    • 12.3. Company Market Share Analysis, 2026
      • 12.3.1. Top 5 Companies Market Share Analysis
      • 12.3.2. Top 3 Companies Market Share Analysis
    • 12.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global South Africa Freight and Logistics Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Gauteng South Africa Freight and Logistics Industry Revenue (Billion), by Logistics Function 2026 & 2034
    3. Figure 3: Gauteng South Africa Freight and Logistics Industry Revenue Share (%), by Logistics Function 2026 & 2034
    4. Figure 4: Gauteng South Africa Freight and Logistics Industry Revenue (Billion), by Mode of Transport 2026 & 2034
    5. Figure 5: Gauteng South Africa Freight and Logistics Industry Revenue Share (%), by Mode of Transport 2026 & 2034
    6. Figure 6: Gauteng South Africa Freight and Logistics Industry Revenue (Billion), by Shipment Coverage 2026 & 2034
    7. Figure 7: Gauteng South Africa Freight and Logistics Industry Revenue Share (%), by Shipment Coverage 2026 & 2034
    8. Figure 8: Gauteng South Africa Freight and Logistics Industry Revenue (Billion), by End-User Industry 2026 & 2034
    9. Figure 9: Gauteng South Africa Freight and Logistics Industry Revenue Share (%), by End-User Industry 2026 & 2034
    10. Figure 10: Gauteng South Africa Freight and Logistics Industry Revenue (Billion), by Country 2026 & 2034
    11. Figure 11: Gauteng South Africa Freight and Logistics Industry Revenue Share (%), by Country 2026 & 2034
    12. Figure 12: Western Cape South Africa Freight and Logistics Industry Revenue (Billion), by Logistics Function 2026 & 2034
    13. Figure 13: Western Cape South Africa Freight and Logistics Industry Revenue Share (%), by Logistics Function 2026 & 2034
    14. Figure 14: Western Cape South Africa Freight and Logistics Industry Revenue (Billion), by Mode of Transport 2026 & 2034
    15. Figure 15: Western Cape South Africa Freight and Logistics Industry Revenue Share (%), by Mode of Transport 2026 & 2034
    16. Figure 16: Western Cape South Africa Freight and Logistics Industry Revenue (Billion), by Shipment Coverage 2026 & 2034
    17. Figure 17: Western Cape South Africa Freight and Logistics Industry Revenue Share (%), by Shipment Coverage 2026 & 2034
    18. Figure 18: Western Cape South Africa Freight and Logistics Industry Revenue (Billion), by End-User Industry 2026 & 2034
    19. Figure 19: Western Cape South Africa Freight and Logistics Industry Revenue Share (%), by End-User Industry 2026 & 2034
    20. Figure 20: Western Cape South Africa Freight and Logistics Industry Revenue (Billion), by Country 2026 & 2034
    21. Figure 21: Western Cape South Africa Freight and Logistics Industry Revenue Share (%), by Country 2026 & 2034
    22. Figure 22: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue (Billion), by Logistics Function 2026 & 2034
    23. Figure 23: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Share (%), by Logistics Function 2026 & 2034
    24. Figure 24: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue (Billion), by Mode of Transport 2026 & 2034
    25. Figure 25: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Share (%), by Mode of Transport 2026 & 2034
    26. Figure 26: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue (Billion), by Shipment Coverage 2026 & 2034
    27. Figure 27: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Share (%), by Shipment Coverage 2026 & 2034
    28. Figure 28: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue (Billion), by End-User Industry 2026 & 2034
    29. Figure 29: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Share (%), by End-User Industry 2026 & 2034
    30. Figure 30: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue (Billion), by Country 2026 & 2034
    31. Figure 31: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Share (%), by Country 2026 & 2034
    32. Figure 32: Mpumalanga South Africa Freight and Logistics Industry Revenue (Billion), by Logistics Function 2026 & 2034
    33. Figure 33: Mpumalanga South Africa Freight and Logistics Industry Revenue Share (%), by Logistics Function 2026 & 2034
    34. Figure 34: Mpumalanga South Africa Freight and Logistics Industry Revenue (Billion), by Mode of Transport 2026 & 2034
    35. Figure 35: Mpumalanga South Africa Freight and Logistics Industry Revenue Share (%), by Mode of Transport 2026 & 2034
    36. Figure 36: Mpumalanga South Africa Freight and Logistics Industry Revenue (Billion), by Shipment Coverage 2026 & 2034
    37. Figure 37: Mpumalanga South Africa Freight and Logistics Industry Revenue Share (%), by Shipment Coverage 2026 & 2034
    38. Figure 38: Mpumalanga South Africa Freight and Logistics Industry Revenue (Billion), by End-User Industry 2026 & 2034
    39. Figure 39: Mpumalanga South Africa Freight and Logistics Industry Revenue Share (%), by End-User Industry 2026 & 2034
    40. Figure 40: Mpumalanga South Africa Freight and Logistics Industry Revenue (Billion), by Country 2026 & 2034
    41. Figure 41: Mpumalanga South Africa Freight and Logistics Industry Revenue Share (%), by Country 2026 & 2034
    42. Figure 42: Eastern Cape South Africa Freight and Logistics Industry Revenue (Billion), by Logistics Function 2026 & 2034
    43. Figure 43: Eastern Cape South Africa Freight and Logistics Industry Revenue Share (%), by Logistics Function 2026 & 2034
    44. Figure 44: Eastern Cape South Africa Freight and Logistics Industry Revenue (Billion), by Mode of Transport 2026 & 2034
    45. Figure 45: Eastern Cape South Africa Freight and Logistics Industry Revenue Share (%), by Mode of Transport 2026 & 2034
    46. Figure 46: Eastern Cape South Africa Freight and Logistics Industry Revenue (Billion), by Shipment Coverage 2026 & 2034
    47. Figure 47: Eastern Cape South Africa Freight and Logistics Industry Revenue Share (%), by Shipment Coverage 2026 & 2034
    48. Figure 48: Eastern Cape South Africa Freight and Logistics Industry Revenue (Billion), by End-User Industry 2026 & 2034
    49. Figure 49: Eastern Cape South Africa Freight and Logistics Industry Revenue Share (%), by End-User Industry 2026 & 2034
    50. Figure 50: Eastern Cape South Africa Freight and Logistics Industry Revenue (Billion), by Country 2026 & 2034
    51. Figure 51: Eastern Cape South Africa Freight and Logistics Industry Revenue Share (%), by Country 2026 & 2034
    52. Figure 52: Other Provinces South Africa Freight and Logistics Industry Revenue (Billion), by Logistics Function 2026 & 2034
    53. Figure 53: Other Provinces South Africa Freight and Logistics Industry Revenue Share (%), by Logistics Function 2026 & 2034
    54. Figure 54: Other Provinces South Africa Freight and Logistics Industry Revenue (Billion), by Mode of Transport 2026 & 2034
    55. Figure 55: Other Provinces South Africa Freight and Logistics Industry Revenue Share (%), by Mode of Transport 2026 & 2034
    56. Figure 56: Other Provinces South Africa Freight and Logistics Industry Revenue (Billion), by Shipment Coverage 2026 & 2034
    57. Figure 57: Other Provinces South Africa Freight and Logistics Industry Revenue Share (%), by Shipment Coverage 2026 & 2034
    58. Figure 58: Other Provinces South Africa Freight and Logistics Industry Revenue (Billion), by End-User Industry 2026 & 2034
    59. Figure 59: Other Provinces South Africa Freight and Logistics Industry Revenue Share (%), by End-User Industry 2026 & 2034
    60. Figure 60: Other Provinces South Africa Freight and Logistics Industry Revenue (Billion), by Country 2026 & 2034
    61. Figure 61: Other Provinces South Africa Freight and Logistics Industry Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    2. Table 2: Global South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    3. Table 3: Global South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    4. Table 4: Global South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    5. Table 5: Global South Africa Freight and Logistics Industry Revenue Billion Forecast, by Region 2020 & 2034
    6. Table 6: Gauteng South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    7. Table 7: Gauteng South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    8. Table 8: Gauteng South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    9. Table 9: Gauteng South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    10. Table 10: Gauteng South Africa Freight and Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
    11. Table 11: Western Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    12. Table 12: Western Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    13. Table 13: Western Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    14. Table 14: Western Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    15. Table 15: Western Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
    16. Table 16: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    17. Table 17: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    18. Table 18: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    19. Table 19: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    20. Table 20: KwaZulu-Natal South Africa Freight and Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
    21. Table 21: Mpumalanga South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    22. Table 22: Mpumalanga South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    23. Table 23: Mpumalanga South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    24. Table 24: Mpumalanga South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    25. Table 25: Mpumalanga South Africa Freight and Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
    26. Table 26: Eastern Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    27. Table 27: Eastern Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    28. Table 28: Eastern Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    29. Table 29: Eastern Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    30. Table 30: Eastern Cape South Africa Freight and Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034
    31. Table 31: Other Provinces South Africa Freight and Logistics Industry Revenue Billion Forecast, by Logistics Function 2020 & 2034
    32. Table 32: Other Provinces South Africa Freight and Logistics Industry Revenue Billion Forecast, by Mode of Transport 2020 & 2034
    33. Table 33: Other Provinces South Africa Freight and Logistics Industry Revenue Billion Forecast, by Shipment Coverage 2020 & 2034
    34. Table 34: Other Provinces South Africa Freight and Logistics Industry Revenue Billion Forecast, by End-User Industry 2020 & 2034
    35. Table 35: Other Provinces South Africa Freight and Logistics Industry Revenue Billion Forecast, by Country 2020 & 2034

    Frequently Asked Questions

    1What is the size of the South Africa freight and logistics market?

    The market was valued at USD 15.55 billion in 2026 and is forecast to reach USD 22.14 billion by 2032, expanding at a CAGR of 6.12% over 2027–2032.

    2Which segment dominates the South Africa freight and logistics market?

    Freight transport accounted for 73.6% of market value in 2026, while manufacturing was the largest end-user industry at a 37.39% share.

    3Which is the fastest-growing segment in the South African logistics market?

    Courier, Express and Parcel (CEP) is the fastest-growing logistics function at a 7.25% CAGR, while wholesale and retail trade leads end-user growth at 6.75% CAGR.

    4Which province leads freight and logistics activity in South Africa?

    Gauteng led provincial activity with 34.7% of national freight and logistics output in 2025, supported by OR Tambo International Airport's cargo connectivity, followed by the Western Cape at 19.6%.

    5Who are the major players in the South Africa freight and logistics industry?

    Key participants include Transnet SOC Ltd, DP World (including Imperial Logistics), A.P. Moller – Maersk, DSV A/S (including DB Schenker), Kuehne+Nagel and DHL Group, alongside domestic courier specialists such as The Courier Guy and Fastway Couriers.

    6How is private sector participation reshaping South African rail freight?

    All 11 train operating companies allocated slots concluded rail-access agreements in May 2026, adding roughly 24 million tonnes of corridor capacity, with rail volumes rising to about 168 million tonnes and Transnet returning to profit.

    7What is driving cold-chain logistics demand in South Africa?

    Agro-export intensity is the core driver: roughly 203 million 15-kg citrus cartons moved in over 120,000 reefer containers to more than 100 destinations in 2025, contributing a +1.7% CAGR impact.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Between 70% and 80% of all inputs are gathered through primary research, with the residual 20–30% sourced from secondary benchmarking and public institutional data.
    • Structured interviews and depth discussions are conducted with rail and intermodal operators, contract logistics and 3PL/4PL providers, courier and last-mile parcel networks, cold-chain and reefer specialists, and freight forwarders and customs brokers across Gauteng, KwaZulu-Natal and the Western Cape.
    • Stakeholder interviews target Supply Chain Directors, Heads of Network and Linehaul Operations, Chief Commercial Officers at logistics providers, and Procurement and Logistics Managers at manufacturing, retail and agro-export shippers.
    • Every report is refreshed to the date of purchase, with base-year estimates combining nine months of actuals and fourth-quarter projections.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Supply Chain Director32%
    Head of Network & Linehaul Operations26%
    Chief Commercial Officer23%
    Procurement & Logistics Manager19%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Contract Logistics & 3PL/4PL Providers30%
    Rail, Port & Intermodal Operators22%
    Courier, Express & Parcel Networks18%
    Freight Forwarders & Customs Brokers16%
    Cold-Chain & Warehousing Specialists14%

    Secondary Research & Industry Benchmarking

    • Cross-validation against official multilateral and governmental datasets, including UN Comtrade via WITS, World Bank Logistics Performance Index, UNCTAD, and OECD trade and transport statistics.
    • Regulatory and institutional benchmarking against the Economic Regulation of Transport Act framework, the Freight Logistics Roadmap, and the National Logistics Crisis Committee publications.
    • Industry association and standards inputs from recognised non-profit transport and logistics bodies, alongside terminal, port and rail throughput disclosures.
    • Financial databases utilised for corporate verification and capital structure analysis: Bloomberg, Factiva, Hoovers and PitchBook.

    Demand Modeling & Market Estimation

    • Simultaneous top-down and bottom-up methodologies are applied, then reconciled through multi-level data triangulation.
    • Bottom-up sizing is constructed from annual rail freight tonnage (approx. 168 million tonnes), container throughput at Durban Container Terminal Pier 2 (over 65% of port throughput), reefer container export volumes (over 120,000 units), and provincial logistics activity shares (Gauteng at 34.7%).
    • Segment revenue pools are built from per-function yield curves, then aggregated to national market value in USD.
    • Driver and restraint impacts are quantified as additive percentage-point contributions to the forecast CAGR.

    Data Accuracy & Quality Check

    • Guaranteed estimated data accuracy level of 85–90%, enforced through multi-level triangulation and cross-source reconciliation.
    • Independent analyst review of every segment total against modal share, tonnage and value-per-shipment sanity checks.
    • Anomaly screening flags any segment where implied growth deviates more than two standard deviations from corridor-level volume evidence.
    • Final outputs are stress-tested against energy price volatility, currency movements and rail execution risk scenarios.