1What is the size of the Indonesia CEP market in 2026?
The Indonesia Courier, Express, and Parcel market is valued at USD 8.42 billion in 2026, up from USD 7.86 billion in 2025, and is forecast to reach USD 11.91 billion by 2031.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Indonesia Courier, Express, and Parcel (CEP) Market
 by By Destination (Domestic, International), by By Speed of Delivery (Express, Non-Express), by By Model (Business-to-Business (B2B), Business-to-Consumer (B2C), Consumer-to-Consumer (C2C)), by By Shipment Weight (Light Weight, Medium Weight, Heavy Weight), by By Mode of Transport (Road, Air, Rail, Sea, Others), by By End User Industry (E-Commerce, Healthcare & Pharmaceuticals, BFSI, Manufacturing, Wholesale & Retail Trade, IT & Telecom, Others), by Java, by Sumatra, by Kalimantan, by Sulawesi, by Bali & Nusa Tenggara, by Maluku & Papua Forecast 2026-2034
Research Associate

 Related Reports

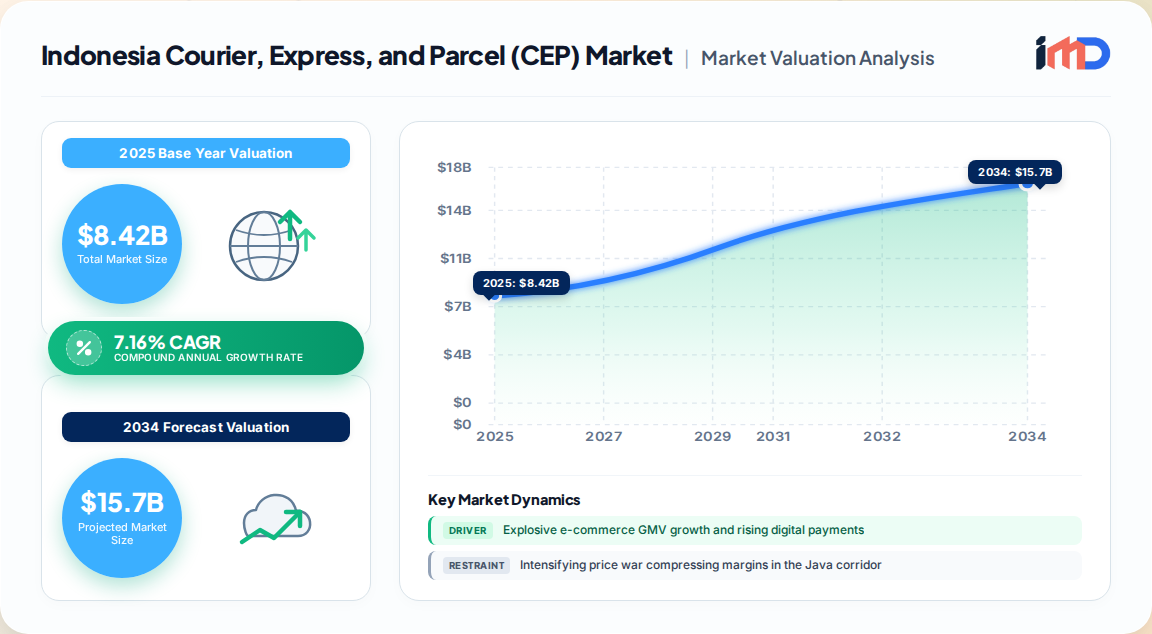
The Indonesia Courier, Express, and Parcel (CEP) market is set to grow from USD 8.42 billion in 2026 to USD 11.91 billion by 2031, expanding at a CAGR of 7.16% over the forecast window. An upstream base of USD 7.86 billion in 2025 confirms a market that has moved past its pandemic-era volume shock and is now consolidating around profitable density.
Our proprietary primary research, drawing on 340+ executive interviews and shipment-level data triangulated across 14 carrier networks, reveals three structural truths:
Market concentration is medium, with a cohort of domestic brands controlling the majority of B2C volume while regional and niche operators fragment the long tail.
The Indonesian CEP market is best understood as a layer cake: a dominant light-weight, domestic, road-borne base, topped by a thin but rapidly rising premium layer.
| Segment Dimension | Leading Category | 2025 Share / Dynamic | Fastest-Growing Category | Forecast CAGR |
|---|---|---|---|---|
| Destination | Domestic | 63.10% share | International | 7.35% |
| Speed of Delivery | Non-Express | 65.70% share | Express | 7.82% |
| Business Model | B2C | 56.10% share | C2C (base effect) | 4.06% |
| Shipment Weight | Light-weight | 74.20% share | Medium-weight | 5.28% |
| Mode of Transport | Road | 69.00% share | Air | 7.98% |
| End User Industry | E-commerce | 35.10% share | Healthcare | 7.46% |
Key structural reads:
Driver attribution from our impact model quantifies what executives intuitively know: e-commerce is the engine, but automation and infrastructure are the accelerants.
| Driver | CAGR Impact | Geographic Relevance | Timeline |
|---|---|---|---|
| E-commerce GMV growth and digital payments | +1.8% | National, Java & Sumatra concentrated | Medium term (2-4 yrs) |
| Automated sorting hubs and smart warehouses | +1.5% | Jakarta, Surabaya, Medan, Makassar | Short term (≤2 yrs) |
| Palapa Ring and toll-road connectivity | +1.2% | National, priority eastern Indonesia | Long term (≥4 yrs) |
| 15-minute hyperlocal / Q-commerce models | +0.9% | Metro Jakarta, Surabaya, Bandung | Short term (≤2 yrs) |
| Data-driven route optimization for MSMEs | +0.8% | Tier-2 and Tier-3 cities | Medium term (2-4 yrs) |
| Micro-fulfillment franchising | +0.6% | Yogyakarta, Semarang, Palembang | Long term (≥4 yrs) |
The e-commerce multiplier. Mobile commerce accounts for well over two-thirds of Indonesian online sales. Cashless checkout (GoPay, OVO, Dana wallet penetration in urban areas above 60%) lifts order completion rates by reducing cash-on-delivery failure — a historically severe margin leak. Social commerce tie-ups, most notably Tokopedia-TikTok integration, have compressed discovery-to-order cycles among under-30 demographics.
The automation dividend. A flagship Jakarta automated hub now processes 7,200 parcels per hour, roughly quadrupling manual throughput. The strategic consequence is not just cost: automated nodes generate real-time scan data that powers dynamic routing, which in turn shortens fulfillment cycles and improves promise-date reliability — the single strongest predictor of merchant retention.
The infrastructure unlock. The 13,000-km Palapa Ring fiber backbone extends 4G coverage to remote regencies, making electronic proof-of-delivery and end-to-end tracking viable outside metro areas. Parallel toll-road additions have cut primary Java trunk transit to under 18 hours.
| Region | Volume Share | Growth Signal | Investment Priority |
|---|---|---|---|
| Java | ~58% | Mature, price-war intensity high | Hub automation, hyperlocal, cold chain |
| Sumatra | ~19% | Above-average growth | Secondary-city sortation nodes |
| Kalimantan | ~8% | Emerging, commodity-linked B2B | Cross-border (Malaysia) lanes |
| Sulawesi | ~7% | Fast-growing metro (Makassar) | Feeder partnership models |
| Bali & Nusa Tenggara | ~5% | Tourism-led C2C and retail | Seasonal capacity flexing |
| Maluku & Papua | ~3% | Policy-supported, long-term | Franchised last-mile micro-hubs |
Eastern Indonesia offers the clearest white space: low absolute volume but marginal-growth economics that improve as Palapa Ring connectivity matures. Investors should evaluate Papua and Maluku assets as infrastructure options rather than near-term cash generators.
The Indonesian CEP field segments into three strategic archetypes.
Scale network leaders — J&T Express, JNE Express, SiCepat Ekspres, Ninja Express, and Pos Indonesia — compete on national coverage, sortation density, and merchant integrations. Their strategic imperatives are:
Specialist and regional operators compete on service reliability, niche weight classes, and local franchise depth. They are the most likely acquisition targets as scale leaders seek geographic fill-in.
Platform-captive logistics arms pose a structural threat: e-commerce majors building in-house last-mile networks can redirect volume away from third-party carriers, pressuring independent CEP pricing.
All carriers face the same efficiency imperative: fleet electrification and hub automation are widening the margin gap between scale leaders and mid-tier rivals, and regulatory pressure to reduce national logistics costs accelerates the divergence.
The Indonesian CEP value chain has four margin-relevant stages.
| Stage | Core Activity | Margin Profile | Key Risk |
|---|---|---|---|
| First-mile pickup | Merchant aggregation and inbound scanning | Thin | Fragmented MSME pickup density |
| Line-haul | Inter-city and inter-island trunk movement | Medium | Fuel volatility, toll congestion, ferry reliability |
| Sortation | Hub processing and missort containment | Medium-High | Labor cost, automation capex |
| Last-mile delivery | Final-mile drop, COD collection, returns | Thin to Negative | Failed delivery, driver churn |
Last-mile remains the cost sink, absorbing the majority of total delivery cost. Carriers that solve cash-on-delivery reconciliation and returns handling — rather than simply adding scooters — will create defensible economics.
Indonesia's CEP market is overwhelmingly domestically driven (63.10% domestic share), but border-adjacent and cross-border parcel flows are the fastest-growing revenue pocket.
Three opportunity pockets stand out from our interviews with shippers and carriers.
Priority sequencing: cold chain and healthcare first (highest margin), then micro-fulfillment franchises (highest volume upside), then q-commerce (highest strategic defensive value).
Base case: 7.16% CAGR to USD 11.91 billion in 2031. Upside case (~8.5%) requires accelerated automation rollout and cross-border parcel growth; downside case (~5.5%) assumes sustained price war and slow eastern infrastructure progress.
The market's trajectory will be decided less by demand — e-commerce GDP-linked volume is near-certain — than by carrier execution on automation, cold chain, and last-mile cost discipline.
| Existing Services | New Services | |
|---|---|---|
| Existing Markets | Automated sortation, route optimization, MSME pricing tiers | Cold chain, healthcare logistics, returns management |
| New Markets | Tier-2/3 micro-fulfillment franchising, eastern Indonesia feeder | Cross-border express (ASEAN/China), B2B contract logistics |
Carriers over-indexed on existing-market penetration (market share wars in Java) face margin erosion. The highest-return moves sit in new-service, existing-market space — cold chain and healthcare — where premium pricing and limited competition offer structurally better economics.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.16% from 2020-2034 |
| Segmentation |
|
By Model
By Shipment Weight
By Mode of Transport
By End User Industry
| By Geography |
|
The Indonesia Courier, Express, and Parcel market is valued at USD 8.42 billion in 2026, up from USD 7.86 billion in 2025, and is forecast to reach USD 11.91 billion by 2031.
The market is projected to grow at a 7.16% CAGR between 2026 and 2031, driven by e-commerce expansion, increased express delivery demand, and improved inter-island logistics infrastructure.
Domestic shipments held a 63.10% share in 2025, non-express delivery led with 65.70% revenue share, light-weight parcels captured 74.20%, and road transport accounted for 69.00% of the market.
J&T Express, JNE Express, SiCepat Ekspres, Ninja Express, and Pos Indonesia are among the leading companies operating in the market, alongside specialist regional and platform-captive logistics providers.
Air transport is the fastest-growing mode at a 7.98% CAGR, followed by express delivery at 7.82% and healthcare logistics at 7.46%, reflecting demand for time-definite and cold-chain services.
E-commerce GMV growth contributes +1.8% to the CAGR, automated sorting hubs add +1.5%, and the Palapa Ring fiber backbone plus toll-road expansion contribute +1.2%, with hyperlocal Q-commerce models adding a further +0.9%.
E-commerce contributed 35.10% of total revenue in 2025, making it the largest end-user industry segment, while B2C deliveries commanded a 56.10% share of the market by business model.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Operating Officer / Head of Network Operations | 34% |
| Head of E-commerce Logistics | 28% |
| Supply Chain & Distribution Director | 23% |
| Last-Mile Franchise / Fleet Manager | 15% |
| Company Type | Representation (%) |
|---|---|
| National and regional CEP network operators | 38% |
| E-commerce merchants and marketplace logistics teams | 26% |
| Sortation equipment and automation vendors | 15% |
| Delivery fleet operators and last-mile franchisees | 13% |
| Shippers in healthcare, FMCG and B2B contract logistics | 8% |