1What is the bonded warehouse services market size in 2026?
Our proprietary research values the global bonded warehouse services market at USD 19.9 billion in 2026, with a projected CAGR of 6.8% through 2036, reaching USD 38.4 billion.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Bonded Warehouse Services Market
 by Service Type (Bonded Warehousing, Free Zone Storage and Customs Clearance), by Facility Type (Free Trade Zones, Bonded Warehouses, Public Warehouses, Private Warehouses), by End Use (Electronics, Manufacturing, Consumer Goods, Food and Beverage, Retail, Healthcare, Other End-User Industries), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, India, Japan, UAE), by Middle East & Africa, by South America Forecast 2026-2034
Research Associate


 Related Reports

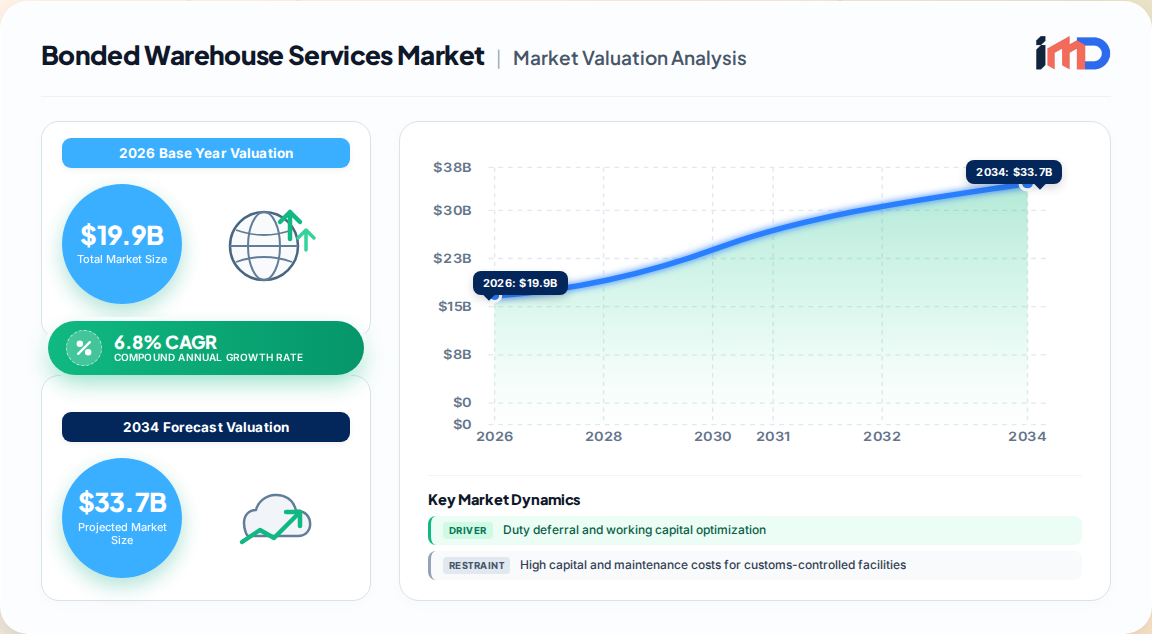
The bonded warehouse services market represents a critical yet often underappreciated node in global trade facilitation. Our proprietary primary research estimates the global market at USD 19.9 billion in 2026, with a clear trajectory to reach USD 38.4 billion by 2036, expanding at a 6.8% CAGR. This growth is not merely a function of rising trade volumes but reflects a structural shift in how importers manage customs exposure, inventory timing, and working capital.
Bonded warehousing is no longer a passive storage function. It is an active financial and operational lever. Shippers increasingly demand facilities where goods can be held under customs control, duties deferred, consignments split or redirected, and value-added activities performed before final market release. Operators that treat bonded space as a commodity will lose share to those that integrate customs handling, real-time inventory visibility, and distribution execution.
Demand for bonded warehouse services is being reshaped by three primary forces identified through our executive interviews and trade-flow modeling.
Drivers:
Restraints:
Our analysis segments the market by service type, facility type, and end-use sector. The following table summarizes the leading segments and their 2026 share estimates.
| Segment Dimension | Leading Segment | 2026 Share | Key Rationale |
|---|---|---|---|
| Service Type | Bonded Warehousing | 31.4% | Direct duty deferral and release-control value; strong in high-value imports |
| Facility Type | Free Trade Zones | 34.8% | Broader service layers including consolidation, value-added handling, and redistribution |
| End-Use | Electronics | 24.6% | High-value inventory, rapid obsolescence, need for import flexibility |
Service Type: Bonded warehousing remains the anchor service, but its value is increasingly realized when bundled with customs clearance and distribution planning. Standalone bonded storage is commoditizing; integrated service models command premium margins.
Facility Type: Free trade zones offer a wider operating envelope than traditional bonded warehouses, supporting staging, relabeling, repacking, and re-export without additional duty exposure. This breadth explains their lead and suggests continued investment in zone-linked logistics capacity.
End-Use: Electronics leads due to high product value and the need to time market release precisely. Healthcare, automotive, and consumer goods follow, each with distinct compliance and handling requirements.
Asia-Pacific is the dominant and fastest-growing region, accounting for 41% of global market share in 2026. India (8.2% CAGR), China (7.8% CAGR), and the United Arab Emirates (7.6% CAGR) lead growth, driven by trade gateway expansion, re-export activity, and customs modernization. North America (27% share) and Europe (24% share) remain mature but steady, with the United States at 6.9% CAGR and Germany at 6.4% CAGR, anchored in established free trade zone frameworks and compliance-intensive industrial trade.
The competitive landscape is moderately consolidated but remains open to regional specialists. Leading global logistics providers and specialized bonded warehouse operators compete on customs expertise, technology integration, and multi-country network coverage. Our primary research reveals that shippers replace storage vendors relatively easily but are far stickier with providers that control the customs-release interface.
Key strategic imperatives include:
The bonded warehouse value chain spans from trade documentation through to final domestic release or re-export.
| Stage | Key Activities | Value Contribution |
|---|---|---|
| Customs Clearance & Brokerage | Classification, duty calculation, documentation, compliance filing | Enables duty deferral and legal release; high margin |
| Bonded Storage | Controlled warehousing, inventory management, security | Core service; moderate margin, scale-dependent |
| Value-Added Handling | Repacking, labeling, assembly, quality inspection | Drives differentiation and premium pricing |
| Distribution & Release | Order fulfillment, transport, last-mile delivery | Captures integrated logistics spend |
| Re-export & Consolidation | Multi-market staging, consolidation, redirection | High value for multi-country shippers |
Operators that only provide storage compete on price. Those that integrate customs brokerage, bonded storage, and distribution capture a disproportionate share of wallet and enjoy higher retention rates.
Bonded warehouse demand is tightly coupled to import/export flows and customs regimes. Our analysis identifies several supply chain risk factors shaping operator strategy.
Operators should prioritize flexibility in bonded space design, robust IT integration with customs authorities, and scenario planning for major trade corridors.
Our primary research identifies several underserved opportunities in the bonded warehouse services market.
These white spaces are not speculative. They are grounded in observed shipper behavior and operator investment patterns from our interviews with logistics executives and customs specialists.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.8% from 2020-2034 |
| Segmentation |
|
By End Use
| By Geography |
|
Our proprietary research values the global bonded warehouse services market at USD 19.9 billion in 2026, with a projected CAGR of 6.8% through 2036, reaching USD 38.4 billion.
Asia-Pacific holds the largest share at approximately 41% in 2026, driven by rapid trade growth in India (8.2% CAGR) and China (7.8% CAGR), according to our primary research.
Duty deferral, inventory flexibility for re-export, and compliance complexity are the top drivers, with electronics accounting for 24.6% of end-use demand in 2026.
Leading operators include DHL, CEVA Logistics, and other global logistics integrators, alongside specialized free trade zone operators and regional bonded warehouse specialists.
Bonded warehousing focuses on duty-deferred storage under customs control, while free trade zones offer broader value-added activities like repacking and redistribution, capturing 34.8% of facility-type share in 2026.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Director of Customs & Trade Compliance | 30% |
| Warehouse Operations Director | 25% |
| Head of Global Logistics | 25% |
| Vice President of Supply Chain | 20% |
| Company Type | Representation (%) |
|---|---|
| Bonded Warehouse Operators | 40% |
| Customs Brokerage & Compliance Firms | 25% |
| Free Trade Zone Developers/Operators | 15% |
| Integrated 3PL Providers | 12% |
| In-house Logistics Teams (Manufacturers/Retailers) | 8% |