1What is the current size of the Egypt cold chain logistics market?
Our proprietary research estimates the Egypt cold chain logistics market at USD 1.02 Billion in 2024, with a projected value of USD 2.32 Billion by 2032, representing a 12.80% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Egypt Cold Chain Logistics Market
 by Service Type (Refrigerated Storage, Refrigerated Transportation, Value-Added Services), by Temperature Type (Chilled, Frozen, Ambient, Deep-Frozen/Ultra-Low), by Application (Fruits & Vegetables, Meat & Poultry, Fish & Seafood, Dairy & Frozen Desserts, Bakery & Confectionery, Ready-To-Eat Meals, Drugs & Pharmaceuticals, Others), by Greater Cairo, by Alexandria & Nile Delta, by Suez Canal Economic Zone, by Upper Egypt, by Other Coastal & Frontier Hubs Forecast 2026-2034
Research Associate


 Related Reports

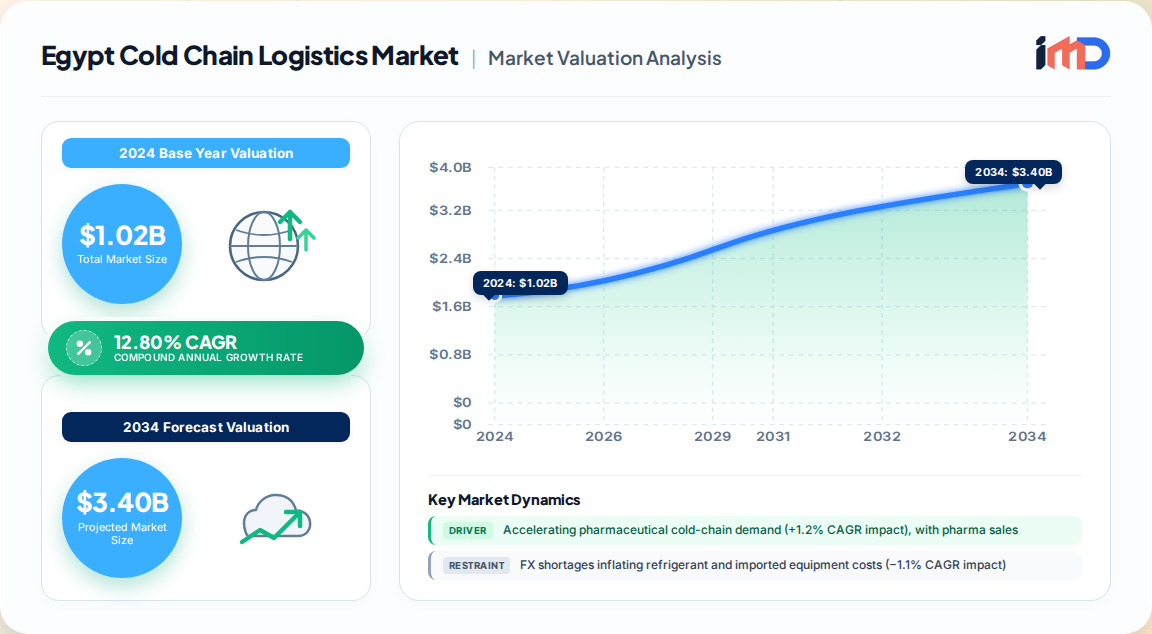
Egypt's cold chain logistics market represents one of the most strategically positioned temperature-controlled logistics ecosystems in the Middle East and Africa. Our proprietary primary research estimates the market at USD 1.02 Billion in 2024, with a projected trajectory toward USD 2.32 Billion by 2032, expanding at a 12.80% CAGR. This growth materially outpaces the modeled historical CAGR of 11.90% recorded between 2020 and 2025, signaling an acceleration driven by export-grade food logistics, pharmaceutical compliance requirements, and the formalization of fragmented storage into contract-based third-party platforms.
Market value growth is outpacing physical throughput. While modeled throughput rose from 2.03 million tonnes in 2020 to 3.00 million tonnes in 2025, value expansion has been steeper because shippers increasingly pay for monitored storage, multi-zone handling, validated pharmaceutical lanes, and integrated storage-transport contracts. Approximately one-third of forward value growth is expected to derive from service enrichment and pricing rather than tonnage alone.
| Market Metric | Value |
|---|---|
| Base Year Market Size (2024) | USD 1.02 Billion |
| Forecast Market Size (2032) | USD 2.32 Billion |
| Forecast CAGR (2025–2032) | 12.80% |
| Historical CAGR (2020–2025) | 11.90% |
| Modeled Throughput (2025) | 3.00 Million Tonnes |
| Refrigerated Storage Share (2025) | 40.45% |
| Frozen Temperature Band Share (2025) | 56.35% |
| Dominant Region | Greater Cairo (38%) |
Operational capacity remains concentrated around Greater Cairo, Alexandria, 10th of Ramadan City, and the Suez corridor, where industrial production and import-export flows converge. Alexandria and Dekheila port developments reported throughput above 800,000 TEUs with 41% growth at the referenced terminal, while Damietta Port's Tahya Misr 1 terminal is designed for 3.5 million TEUs annually — gateways that materially improve the economics of reefer consolidation and port-linked cold storage.
Red Sea disruptions that lowered Suez Canal revenues by 60% in 2024 also temper overall momentum, introducing routing uncertainty for temperature-sensitive cargo.
By service type, refrigerated storage led with 40.45% of market share in 2025, and remains the largest service pool — favoring operators with multi-temperature assets near ports and food-processing clusters. Value-added services are projected to register the fastest growth at a 4.12% CAGR through 2031, reflecting customer willingness to pay for monitoring, compliance documentation, and integrated handling.
By temperature type, the frozen band (−18°C to 0°C) accounted for 56.35% of market size in 2025, anchoring utilization across food and processed-food categories. Chilled applications (0°C to 5°C) are forecast to expand at a 4.88% CAGR, gradually rebalancing the mix as fresh produce, dairy, and pharmaceutical volumes scale.
By application, meat and poultry held 27.45% of market share in 2025, while ready-to-eat meals are expected to post the quickest growth at a 4.11% CAGR between 2026 and 2031, driven by urban convenience demand and e-grocery expansion.
| Segment | 2025 Share / CAGR | Outlook |
|---|---|---|
| Refrigerated Storage | 40.45% share | Largest service pool; port-adjacent assets favored |
| Value-Added Services | 4.12% CAGR | Fastest-growing service category |
| Frozen Band | 56.35% share | Anchors utilization; processed-food driven |
| Chilled Band | 4.88% CAGR | Fastest-growing temperature band |
| Meat & Poultry | 27.45% share | Largest application category |
| Ready-to-Eat Meals | 4.11% CAGR | Quickest-growing application |
Egypt's cold chain value chain spans pre-cooling at farm gates, controlled storage, reefer transport, port and airport handling, and last-mile delivery. Export intensity creates repeat demand for pre-cooling, inspection-ready handling, and temperature-protected inland movement. Egypt recorded 9.5 million tonnes of agricultural exports in 2025, up by more than 800,000 tonnes year-on-year, reinforcing the export-grade logistics requirement.
On the import side, Egypt's reliance on imported refrigeration equipment and refrigerants exposes the value chain to currency and freight volatility. The National Single Window (Nafeza) has materially shortened dwell times for temperature-sensitive cargo, but Red Sea disruptions have introduced routing uncertainty that disproportionately affects reefer container availability and insurance costs.
Cairo International Airport has emerged as a critical pharmaceutical gateway, with CACC Cargolinx securing IATA CEIV Pharma certification for its 10,000 m² terminal, setting a benchmark for GDP-compliant facilities. DHL Group's EUR 2 Billion (USD 2.08 Billion) global healthcare logistics plan earmarks new GDP hubs and temperature-controlled fleets that will boost local capacity.
For investors, underwriting should shift toward locations with anchor shippers, power resilience, and port connectivity. A planned cold-storage project in 6th of October City with 25,000 pallet positions illustrates the type of capacity addition likely to expand addressable outsourced revenue.
Greater Cairo commands an estimated 38% of market activity, reflecting its role as the consumption and pharmaceutical manufacturing hub. Alexandria and the Nile Delta account for approximately 27%, supported by agricultural export corridors and port infrastructure. The Suez Canal Economic Zone captures about 21%, buoyed by free-zone incentives and trans-shipment positioning. Upper Egypt represents 9%, characterized by limited Grade-A capacity but significant agricultural potential, while other coastal and frontier hubs account for the remaining 5%.
The competitive landscape is moderately fragmented, with domestic operators and global logistics players competing across service tiers. Logistica, Logistics for Storage Services (S.A.E), Custom Storage Company (CSC), SulleX, EPx Logistics, Arab Company for Food Industries and Cooling (ACFIC), and Multi Fruit Egypt are among the leading domestic operators. Global players including DHL Supply Chain and PIL Logistics are expanding capacity through targeted investments.
| Region | Estimated Share | Key Characteristics |
|---|---|---|
| Greater Cairo | 38% | Consumption hub; pharma manufacturing; largest 3PL base |
| Alexandria & Nile Delta | 27% | Agricultural export corridors; port connectivity |
| Suez Canal Economic Zone | 21% | Free-zone incentives; trans-shipment; silo investment |
| Upper Egypt | 9% | Underserved Grade-A capacity; agricultural potential |
| Other Coastal & Frontier Hubs | 5% | Emerging; infrastructure-constrained |
Three white-space clusters warrant priority attention from operators and investors:
Automation and robotics are identified by industry experts as a leading opportunity to enhance efficiency and reduce spoilage, while e-grocery fulfillment — with online grocery sales increasing by as much as 45% annually — requires micro-fulfillment cold rooms and insulated multi-temperature delivery vehicles.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.80% from 2020-2034 |
| Segmentation |
|
By Application
| By Geography |
|
Our proprietary research estimates the Egypt cold chain logistics market at USD 1.02 Billion in 2024, with a projected value of USD 2.32 Billion by 2032, representing a 12.80% CAGR.
Refrigerated storage led with 40.45% of market share in 2025, while value-added services are projected to register the fastest growth at a 4.12% CAGR through 2031.
Key drivers include pharmaceutical cold-chain demand (+1.2% CAGR impact), processed-food exports reaching USD 6.1 Billion in 2024, and government investment in Suez Canal logistics corridors including a USD 153 Million grain silo program.
Greater Cairo commands an estimated 38% of market activity, followed by Alexandria and the Nile Delta at 27% and the Suez Canal Economic Zone at 21%, reflecting concentration around consumption, export corridors, and trans-shipment infrastructure.
Leading operators include Logistica, Logistics for Storage Services (S.A.E), Custom Storage Company (CSC), SulleX, EPx Logistics, Arab Company for Food Industries and Cooling (ACFIC), and Multi Fruit Egypt, alongside global players such as DHL Supply Chain and PIL Logistics.
The frozen band accounted for 56.35% of market size in 2025, but chilled applications are forecast to expand at a faster 4.88% CAGR through 2031, driven by fresh produce, dairy, and pharmaceutical volumes.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Executive Officer | 22% |
| Head of Supply Chain | 30% |
| Cold Chain Operations Director | 26% |
| Procurement Manager | 22% |
| Company Type | Representation (%) |
|---|---|
| Refrigerated Warehouse Operators | 30% |
| Reefer Fleet & Transport Providers | 22% |
| Port & Airport Cold-Handling Operators | 16% |
| Pharmaceutical & Food Shipper Organizations | 18% |
| IoT Monitoring & Cold Chain Technology Providers | 14% |