About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
report thumbnailSelf-service
Professional and Commercial Services / MARKET REPORT

Self-service | Insight Market Data

Self-service by Product Type (Kiosk, ATM, Vending Machine, Self-Checkout System, Ticketing and Check-in Terminal), by Component (Hardware, Software, Services), by End-User Industry (BFSI, Retail and Quick-Service Restaurant, Healthcare, Government, Travel and Tourism, Food and Beverage), by Technology (Biometric-Enabled, NFC/Contactless, AI-Driven and Computer-Vision, Traditional), by Deployment Location (Indoor, Outdoor), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, NORDIC), by Asia Pacific (China, Japan, India, South Korea, Singapore, Australia, Indonesia), by South America (Brazil, Mexico, Argentina), by Middle East & Africa (GCC, Israel, South Africa) Forecast 2026-2034
© Nov 20, 2026|Base Year: 2025|233 Pages
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

Main Logo

Self-Service Market Size, Share & Growth Outlook 2026-2033


/
/
Home
Industries
Professional and Commercial Services

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Author
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

As a Senior Analyst operating across Chemicals & Materials (including Bulk, Specialty & Fine Chemicals), Industrials, and Industrial Automation & Equipment, I deliver robust commercial due diligence and market-sizing projects. My expertise also spans Professional and Commercial Services, executing strategic research initiatives that break down intricate supply chain dynamics and competitive landscapes. Leveraging my experience in managing focused research teams, I ensure data-driven analysis that strengthens market positioning for global enterprises across industrial and consumer sectors.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 20, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

BIM Consulting Service Market Size, Trends & Forecast to 2031

BIM consulting service market valued at USD 7.8 Billion in 2023, projected to reach USD 15.1 Billion by 2031 at 13.8% CAGR. Get full analysis.

Nov 2026|237 pages
$2900.00View report

Global Computer Repair and Refurbishment Service market to reach $5.29 Billion by 2032 at 4.6% CAGR. In-depth analysis, trends, and forecasts.

Nov 2026|264 pages
$2900.00

Environmental Engineering Service market to reach $90 Billion by 2035 at 3.0% CAGR. Get exclusive data on trends, drivers, and competitive landscape.

Nov 2026|260 pages
$2900.00

The Cyber Security Incident Response and Recovery Service market is valued at USD 49.71 Billion in 2026, growing at 18.52% CAGR to reach USD 116.17 Billion by 2031.

Nov 2026|220 pages
$2900.00
Computer Repair & Refurbishment Service Market Report 2026
View report
Environmental Engineering Service Market Report 2026-2035
View report
Cyber Security Incident Response & Recovery Service Market 2026
View report
Self-service CAGR, market size, market share

Executive Overview: A $132.5 Billion Inflection Point

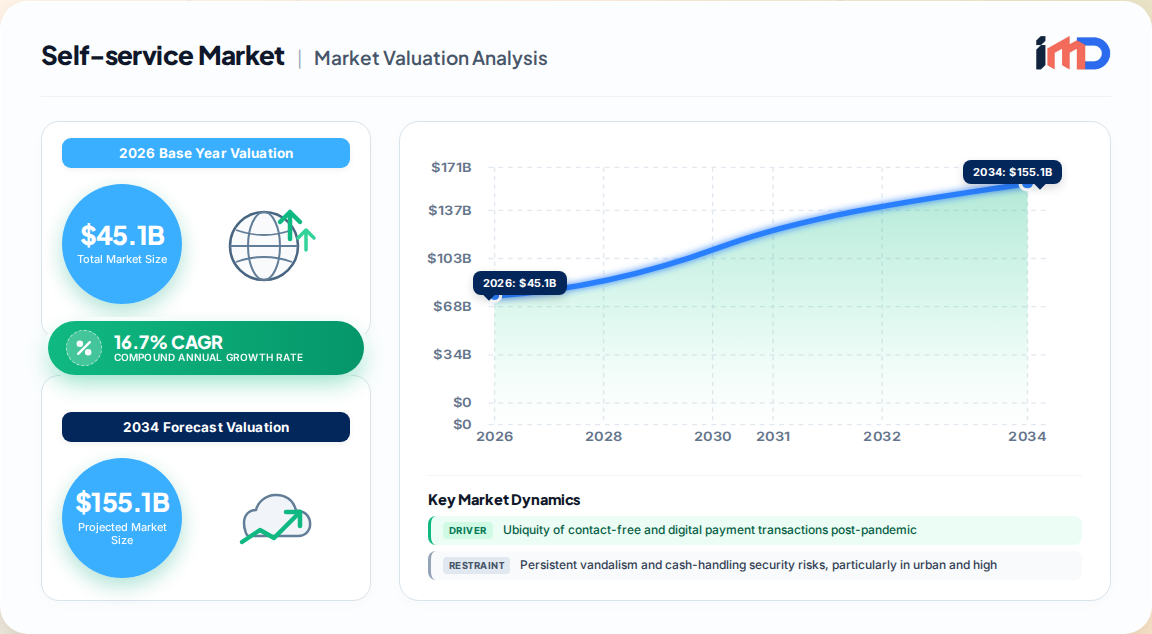
The global self-service market is undergoing a structural re-platforming from transaction-oriented hardware to intelligence-led, contactless service ecosystems. Our proprietary primary research and expert interview program sizes the market at USD 45.1 billion in 2026, projected to reach USD 132.5 billion by 2033, expanding at a 16.7% CAGR. This trajectory reflects more than post-pandemic normalization; it captures a durable shift in consumer expectation and operator economics.

Self-service Market Size (In Billion)

100.0B
80.0B
60.0B
40.0B
20.0B
0
38.65 B
2025
45.10 B
2026
52.63 B
2027
61.42 B
2028
71.68 B
2029
83.65 B
2030
97.62 B
2031
Main Logo

Three forces define the cycle: (1) the ubiquity of contact-free payment credentials across developed and urban emerging markets, (2) the rapid rollout of smart retail and unmanned formats, and (3) an omni-channel banking automation wave in which self-service ATMs function as low-cost branch extensions.

  • Base year (2026) valuation: USD 45.1 billion
  • Forecast (2033) valuation: USD 132.5 billion
  • Fastest-growing product line: Vending and unattended retail machines
  • Fastest-growing region: Asia-Pacific, anchored by cash-lite policy and metro kiosk installation

Market Drivers: The Economics of Unattended Service

Driver analysis from our bottom-up models attributes the largest incremental CAGR lift to the permanence of contact-free transactions. Global digital payment participation has moved from roughly 44% of adults in 2014 to nearly two-thirds by 2022 — a structural, not cyclical, change. Our interviews with operators of micro-markets consistently report revenue uplift after cashless module installation.

  • Ubiquity of contact-free transactions: +1.8% CAGR impact; strongest in developed markets over a 2–4 year horizon.
  • Smart retail format rollout: +1.5% CAGR; led by North America and Europe, now accelerating in APAC.
  • Omni-channel banking automation: +1.2% CAGR; a long-term (4+ year) driver as banks extend 24/7 coverage at lower footprint cost.
  • Government cash-lite mandates: +1.0% CAGR; India's UPI cleared over 100 billion transfers, validating public policy tailwinds.
  • AI-powered adaptive interfaces: +0.9% CAGR; edge inference at the kiosk is cutting transaction friction.

Operators increasingly view the terminal as a recurring-revenue node — service contracts, software subscriptions, and remote monitoring fees smooth cash flow versus one-off hardware sales.

Restraints and Operational Challenges

Growth is not frictionless. Our respondent panel identifies vandalism/cash-handling security as the single largest drag, followed by total cost of ownership in harsh outdoor environments.

  • Persistent vandalism and cash-handling security risk: −0.8% CAGR impact; elevated in dense urban and high-crime zones.
  • High TCO for outdoor deployments: −0.6% CAGR; acute in northern climates and extreme-weather regions.
  • High upfront hardware and integration cost: a structural barrier for small and mid-sized enterprises that cannot generate sufficient transaction volume to justify deployment.
  • Wear-and-tear maintenance: screens, printers, and card readers degrade under constant use, raising downtime risk across large networks.
  • E-commerce substitution: remains a prerequisite consideration in retail business cases.

Self-Service Kiosk Segmentation: Products and Components

Kiosks remain the volume anchor of the self-service market, while self-checkout systems post the steepest growth. Hardware still dominates component revenue, but software is the fastest-compounding layer as operators migrate to cloud management.

Segment 2025 Share / Growth 2026–2031 Outlook
Kiosks (product) 35.74% share Steady leader; self-checkout at 8.63% CAGR
Hardware (component) 53.52%–58.4% share Largest pool; refresh cycle driven
Software (component) — 8.66% CAGR; highest-margin layer
Retail & QSR (end-user) 31.45% share Dominant vertical
Healthcare (end-user) — 7.85% CAGR; fastest vertical
Biometric-enabled (technology) 48.35% share Largest technology cohort
AI-driven (technology) — 8.28% CAGR
Indoor (deployment) 66.02% share Core installed base
Outdoor (deployment) — 8.74% CAGR; fastest location

Key product families include self-checkout, retail information kiosks, banking and cash-recycling ATMs, ticketing and check-in terminals, self-order food kiosks, vending, and parking kiosks. AI and computer-vision modules now identify products, verify age, and accelerate checkout with minimal staff intervention.

Regional Outlook and Investment Attractiveness

Regional positioning is bifurcated: North America leads on installed base and per-capita spend, while Asia-Pacific leads on absolute revenue pool and growth velocity.

Self-service Regional Market Share

Loading chart...
Main Logo
  • Asia-Pacific: 38.0% revenue share in 2025; fastest-growing region at roughly 8.2%–9.4% CAGR, powered by metro kiosk installations, digital-payment penetration, and healthcare infrastructure investment.
  • North America: 36%–39% revenue share; deep retail and banking refresh demand; U.S. self-service kiosks alone tracked double-digit growth in the early 2020s.
  • Europe: mature, regulation-sensitive, with strong self-checkout outlet density (Germany alone counted more than 5,000 self-checkout outlets in recent survey work).
  • Middle East & Africa and South America: emerging white space, concentrated in banking, transport, and government service kiosks.

Investment attractiveness is highest where four conditions coincide: high digital-payment penetration, supportive cash-lite policy, dense high-footfall venues, and reliable connectivity for remote monitoring.

Competitive Landscape and Strategic Developments

The market is medium-concentration with a long tail of regional kiosk fabricators. Competitive advantage is migrating from sheet-metal engineering to software, service networks, and payment-neutral integration.

Leading players include NCR Corporation / NCR Atleos, Diebold Nixdorf, Fujitsu, Zebra Technologies, HESS Cash Systems, KIOSK Information Systems, Olea Kiosks, Advantech, Posiflex, Source Technologies, Embross, Aila Technologies, REDYREF, DynaTouch, and Touchscreen Solutions. NCR Atleos derives roughly two-thirds of revenue from recurring service streams tied to approximately 800,000 installed ATMs; Diebold Nixdorf integrates more than 230,000 machines into its cloud kernel for remote monitoring and software upsell.

  • 2023: SITA upgraded 400 Air France-KLM self-service kiosks at Paris CDG and Amsterdam Schiphol with contactless payment functionality.
  • 2024: Diebold Nixdorf equipped an EDEKA-affiliated store with DN Series EASY eXpress self-checkout featuring AI-powered automatic age verification.
  • 2024: Fiserv expanded smart-retail self-service deployments, reinforcing payment-integrated kiosk models.
  • 2024: Irish QSR operator Ordú invested USD 1.54 million with a kiosk manufacturer, expected to generate USD 9.2 million in incremental revenue over three years.
  • 2026: Posiflex launched AI-enabled SCO Series self-checkout kiosks with food-recognition modules and edge-AI platforms.
  • 2026: NAIA airport expanded automated check-in and self-boarding gates across terminals and airlines.
  • 2026: Indian banks announced plans to deploy nearly 17,350 ATMs, including approximately 13,100 cash-recycling machines.

Value Chain, Sourcing, and Public-Sector Demand

The value chain runs from display, payment-terminal, scanner, and processor suppliers through kiosk OEMs, software platform vendors, integrators, and field-service networks to venue operators. Hardware-neutral, payment-neutral platforms are lowering deployment complexity and enabling operators to mix equipment by location.

Public-sector digitization is an underappreciated demand pulse. Tax administrations increasingly push taxpayers toward self-service channels to lower cost-to-serve, and government agencies deploy interactive kiosks for forms, licenses, and welfare services. Cross-country evidence from OECD tax administration benchmarking shows that digital service channels correlate with higher collection efficiency and lower contact-centre load — a template now being replicated in transport, healthcare, and municipal services.

Supply-chain risk concentrates in semiconductor availability, payment-terminal certification cycles (PCI and EMV), and outdoor enclosure durability. Operators are responding with staged rollouts, remote monitoring, and modular field-replaceable components.

Strategic White-Space and Procurement Strategy

The clearest white space sits at the intersection of three vectors: unattended food and beverage retail, healthcare self-service, and outdoor cash-recycling banking.

  • Unattended food retail: vending and automated food kiosks are the fastest-growing product cohort, supported by corporate-campus and hospital deployments.
  • Healthcare self-service: highest vertical CAGR at roughly 7.85%, driven by check-in, identity verification, and payment kiosks.
  • Outdoor banking: fastest-growing deployment location at 8.74% CAGR; cash recycling plus biometric authentication is the winning specification.

For procurement teams, the recommended strategy is to contract on total cost of ownership rather than unit price, insist on open APIs for POS and payment integration, and negotiate service-level agreements covering uptime, mean-time-to-repair, and remote diagnostics. Fleet-level standardization reduces spare-parts complexity, while region-specific accessibility compliance must be designed in rather than retrofitted.

Self-service Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Self-service REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2026
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 16.7% from 2020-2034
Segmentation
  • By Product Type

    • Kiosk
    • ATM
    • Vending Machine
    • Self-Checkout System
    • Ticketing and Check-in Terminal
  • By Component

Table of Contents

  1. 1. Self-service Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Self-service Executive Summary
    • 2.1. Market Snapshot
  3. 3. Self-service Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Ubiquity of contact-free and digital payment transactions post-pandemic
      • 3.1.2. Rapid rollout of smart retail formats and self-checkout outlets
      • 3.1.3. Omni-channel banking automation wave and cash-recycling ATM deployment
      • 3.1.4. Government push for cash-lite societies and digital public service channels
      • 3.1.5. AI-powered adaptive user interfaces improving speed and accessibility
      • 3.1.6. Micro-fulfilment and 24/7 unmanned retail concepts in urban centers
    • 3.2. Market Trends
      • 3.2.1. Integration of AI, computer vision, and edge computing into self-service terminals for product recognition and personalized interaction
      • 3.2.2. Rise of biometric authentication with passive liveness detection for secure, frictionless identity verification
      • 3.2.3. Shift from one-off hardware sales to recurring revenue via service contracts, software subscriptions, and remote monitoring
      • 3.2.4. Expansion of unattended retail formats including micro-markets, smart stores, and 24/7 vending kiosks
      • 3.2.5. Adoption of open, hardware-neutral and payment-neutral integration platforms to simplify large-scale deployments
    • 3.3. Market Restraints
  • Hardware
  • Software
  • Services
  • By End-User Industry

    • BFSI
    • Retail and Quick-Service Restaurant
    • Healthcare
    • Government
    • Travel and Tourism
    • Food and Beverage
  • By Technology

    • Biometric-Enabled
    • NFC/Contactless
    • AI-Driven and Computer-Vision
    • Traditional
  • By Deployment Location

    • Indoor
    • Outdoor
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • UK
      • France
      • Italy
      • Spain
      • NORDIC
    • Asia Pacific

      • China
      • Japan
      • India
      • South Korea
      • Singapore
      • Australia
      • Indonesia
    • South America

      • Brazil
      • Mexico
      • Argentina
    • Middle East & Africa

      • GCC
      • Israel
      • South Africa
    • 3.3.1. Persistent vandalism and cash-handling security risks, particularly in urban and high-crime areas
    • 3.3.2. High total cost of ownership for outdoor deployments in harsh and extreme-weather climates
    • 3.3.3. High upfront hardware, software, and integration costs that deter small and mid-sized enterprises
    • 3.3.4. Wear-and-tear maintenance burden on screens, printers, and card readers across large fleets
  • 3.4. Market Challenges
    • 3.4.1. Maintaining high system availability and uptime across large distributed kiosk networks
    • 3.4.2. Balancing accessibility compliance with security and fraud prevention requirements
    • 3.4.3. Managing cybersecurity exposure as kiosks connect to cloud management platforms
    • 3.4.4. Ensuring interoperability across POS, payment, and identity ecosystems
  • 4. Self-service Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Self-service Analysis, Insights and Forecast, 2020-2034
    • 5.1. Analysis, Insights and Forecast - by Product Type
      • 5.1.1. Kiosk
      • 5.1.2. ATM
      • 5.1.3. Vending Machine
      • 5.1.4. Self-Checkout System
      • 5.1.5. Ticketing and Check-in Terminal
    • 5.2. Analysis, Insights and Forecast - by Component
      • 5.2.1. Hardware
      • 5.2.2. Software
      • 5.2.3. Services
    • 5.3. Analysis, Insights and Forecast - by End-User Industry
      • 5.3.1. BFSI
      • 5.3.2. Retail and Quick-Service Restaurant
      • 5.3.3. Healthcare
      • 5.3.4. Government
      • 5.3.5. Travel and Tourism
      • 5.3.6. Food and Beverage
    • 5.4. Analysis, Insights and Forecast - by Technology
      • 5.4.1. Biometric-Enabled
      • 5.4.2. NFC/Contactless
      • 5.4.3. AI-Driven and Computer-Vision
      • 5.4.4. Traditional
    • 5.5. Analysis, Insights and Forecast - by Deployment Location
      • 5.5.1. Indoor
      • 5.5.2. Outdoor
    • 5.6. Analysis, Insights and Forecast - by Region
      • 5.6.1. North America
      • 5.6.2. Europe
      • 5.6.3. Asia Pacific
      • 5.6.4. South America
      • 5.6.5. Middle East & Africa
  • 6. Self-service North America Analysis, Insights and Forecast, 2020-2034
    • 6.1. Analysis, Insights and Forecast - by Product Type
      • 6.1.1. Kiosk
      • 6.1.2. ATM
      • 6.1.3. Vending Machine
      • 6.1.4. Self-Checkout System
      • 6.1.5. Ticketing and Check-in Terminal
    • 6.2. Analysis, Insights and Forecast - by Component
      • 6.2.1. Hardware
      • 6.2.2. Software
      • 6.2.3. Services
    • 6.3. Analysis, Insights and Forecast - by End-User Industry
      • 6.3.1. BFSI
      • 6.3.2. Retail and Quick-Service Restaurant
      • 6.3.3. Healthcare
      • 6.3.4. Government
      • 6.3.5. Travel and Tourism
      • 6.3.6. Food and Beverage
    • 6.4. Analysis, Insights and Forecast - by Technology
      • 6.4.1. Biometric-Enabled
      • 6.4.2. NFC/Contactless
      • 6.4.3. AI-Driven and Computer-Vision
      • 6.4.4. Traditional
    • 6.5. Analysis, Insights and Forecast - by Deployment Location
      • 6.5.1. Indoor
      • 6.5.2. Outdoor
  • 7. Self-service Europe Analysis, Insights and Forecast, 2020-2034
    • 7.1. Analysis, Insights and Forecast - by Product Type
      • 7.1.1. Kiosk
      • 7.1.2. ATM
      • 7.1.3. Vending Machine
      • 7.1.4. Self-Checkout System
      • 7.1.5. Ticketing and Check-in Terminal
    • 7.2. Analysis, Insights and Forecast - by Component
      • 7.2.1. Hardware
      • 7.2.2. Software
      • 7.2.3. Services
    • 7.3. Analysis, Insights and Forecast - by End-User Industry
      • 7.3.1. BFSI
      • 7.3.2. Retail and Quick-Service Restaurant
      • 7.3.3. Healthcare
      • 7.3.4. Government
      • 7.3.5. Travel and Tourism
      • 7.3.6. Food and Beverage
    • 7.4. Analysis, Insights and Forecast - by Technology
      • 7.4.1. Biometric-Enabled
      • 7.4.2. NFC/Contactless
      • 7.4.3. AI-Driven and Computer-Vision
      • 7.4.4. Traditional
    • 7.5. Analysis, Insights and Forecast - by Deployment Location
      • 7.5.1. Indoor
      • 7.5.2. Outdoor
  • 8. Self-service Asia Pacific Analysis, Insights and Forecast, 2020-2034
    • 8.1. Analysis, Insights and Forecast - by Product Type
      • 8.1.1. Kiosk
      • 8.1.2. ATM
      • 8.1.3. Vending Machine
      • 8.1.4. Self-Checkout System
      • 8.1.5. Ticketing and Check-in Terminal
    • 8.2. Analysis, Insights and Forecast - by Component
      • 8.2.1. Hardware
      • 8.2.2. Software
      • 8.2.3. Services
    • 8.3. Analysis, Insights and Forecast - by End-User Industry
      • 8.3.1. BFSI
      • 8.3.2. Retail and Quick-Service Restaurant
      • 8.3.3. Healthcare
      • 8.3.4. Government
      • 8.3.5. Travel and Tourism
      • 8.3.6. Food and Beverage
    • 8.4. Analysis, Insights and Forecast - by Technology
      • 8.4.1. Biometric-Enabled
      • 8.4.2. NFC/Contactless
      • 8.4.3. AI-Driven and Computer-Vision
      • 8.4.4. Traditional
    • 8.5. Analysis, Insights and Forecast - by Deployment Location
      • 8.5.1. Indoor
      • 8.5.2. Outdoor
  • 9. Self-service South America Analysis, Insights and Forecast, 2020-2034
    • 9.1. Analysis, Insights and Forecast - by Product Type
      • 9.1.1. Kiosk
      • 9.1.2. ATM
      • 9.1.3. Vending Machine
      • 9.1.4. Self-Checkout System
      • 9.1.5. Ticketing and Check-in Terminal
    • 9.2. Analysis, Insights and Forecast - by Component
      • 9.2.1. Hardware
      • 9.2.2. Software
      • 9.2.3. Services
    • 9.3. Analysis, Insights and Forecast - by End-User Industry
      • 9.3.1. BFSI
      • 9.3.2. Retail and Quick-Service Restaurant
      • 9.3.3. Healthcare
      • 9.3.4. Government
      • 9.3.5. Travel and Tourism
      • 9.3.6. Food and Beverage
    • 9.4. Analysis, Insights and Forecast - by Technology
      • 9.4.1. Biometric-Enabled
      • 9.4.2. NFC/Contactless
      • 9.4.3. AI-Driven and Computer-Vision
      • 9.4.4. Traditional
    • 9.5. Analysis, Insights and Forecast - by Deployment Location
      • 9.5.1. Indoor
      • 9.5.2. Outdoor
  • 10. Self-service Middle East & Africa Analysis, Insights and Forecast, 2020-2034
    • 10.1. Analysis, Insights and Forecast - by Product Type
      • 10.1.1. Kiosk
      • 10.1.2. ATM
      • 10.1.3. Vending Machine
      • 10.1.4. Self-Checkout System
      • 10.1.5. Ticketing and Check-in Terminal
    • 10.2. Analysis, Insights and Forecast - by Component
      • 10.2.1. Hardware
      • 10.2.2. Software
      • 10.2.3. Services
    • 10.3. Analysis, Insights and Forecast - by End-User Industry
      • 10.3.1. BFSI
      • 10.3.2. Retail and Quick-Service Restaurant
      • 10.3.3. Healthcare
      • 10.3.4. Government
      • 10.3.5. Travel and Tourism
      • 10.3.6. Food and Beverage
    • 10.4. Analysis, Insights and Forecast - by Technology
      • 10.4.1. Biometric-Enabled
      • 10.4.2. NFC/Contactless
      • 10.4.3. AI-Driven and Computer-Vision
      • 10.4.4. Traditional
    • 10.5. Analysis, Insights and Forecast - by Deployment Location
      • 10.5.1. Indoor
      • 10.5.2. Outdoor
  • 11. Self-service Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. NCR Corporation (NCR Atleos)
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. Diebold Nixdorf
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Fujitsu Ltd.
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Zebra Technologies
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. HESS Cash Systems GmbH
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. KIOSK Information Systems
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Olea Kiosks
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. Advantech
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. Posiflex Technology
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. Source Technologies
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Embross
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Aila Technologies Inc.
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. REDYREF
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. DynaTouch
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. Touchscreen Solutions
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. Advanced Kiosks
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
      • 11.1.17. Acquire Digital Inc.
        • 11.1.17.1. Company Overview
        • 11.1.17.2. Products
        • 11.1.17.3. Company Financials
        • 11.1.17.4. SWOT Analysis
      • 11.1.18. Evoke Creative
        • 11.1.18.1. Company Overview
        • 11.1.18.2. Products
        • 11.1.18.3. Company Financials
        • 11.1.18.4. SWOT Analysis
      • 11.1.19. Kiosk Group Inc.
        • 11.1.19.1. Company Overview
        • 11.1.19.2. Products
        • 11.1.19.3. Company Financials
        • 11.1.19.4. SWOT Analysis
      • 11.1.20. Mimo Monitors
        • 11.1.20.1. Company Overview
        • 11.1.20.2. Products
        • 11.1.20.3. Company Financials
        • 11.1.20.4. SWOT Analysis
      • 11.1.21. Honeywell International
        • 11.1.21.1. Company Overview
        • 11.1.21.2. Products
        • 11.1.21.3. Company Financials
        • 11.1.21.4. SWOT Analysis
      • 11.1.22. Panasonic Corporation of North America
        • 11.1.22.1. Company Overview
        • 11.1.22.2. Products
        • 11.1.22.3. Company Financials
        • 11.1.22.4. SWOT Analysis
      • 11.1.23. Ingenico
        • 11.1.23.1. Company Overview
        • 11.1.23.2. Products
        • 11.1.23.3. Company Financials
        • 11.1.23.4. SWOT Analysis
      • 11.1.24. Star Micronics America Inc.
        • 11.1.24.1. Company Overview
        • 11.1.24.2. Products
        • 11.1.24.3. Company Financials
        • 11.1.24.4. SWOT Analysis
      • 11.1.25. LG-MRI LLC
        • 11.1.25.1. Company Overview
        • 11.1.25.2. Products
        • 11.1.25.3. Company Financials
        • 11.1.25.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Self-service Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: North America Self-service Revenue (Billion), by Product Type 2026 & 2034
    3. Figure 3: North America Self-service Revenue Share (%), by Product Type 2026 & 2034
    4. Figure 4: North America Self-service Revenue (Billion), by Component 2026 & 2034
    5. Figure 5: North America Self-service Revenue Share (%), by Component 2026 & 2034
    6. Figure 6: North America Self-service Revenue (Billion), by End-User Industry 2026 & 2034
    7. Figure 7: North America Self-service Revenue Share (%), by End-User Industry 2026 & 2034
    8. Figure 8: North America Self-service Revenue (Billion), by Technology 2026 & 2034
    9. Figure 9: North America Self-service Revenue Share (%), by Technology 2026 & 2034
    10. Figure 10: North America Self-service Revenue (Billion), by Deployment Location 2026 & 2034
    11. Figure 11: North America Self-service Revenue Share (%), by Deployment Location 2026 & 2034
    12. Figure 12: North America Self-service Revenue (Billion), by Country 2026 & 2034
    13. Figure 13: North America Self-service Revenue Share (%), by Country 2026 & 2034
    14. Figure 14: Europe Self-service Revenue (Billion), by Product Type 2026 & 2034
    15. Figure 15: Europe Self-service Revenue Share (%), by Product Type 2026 & 2034
    16. Figure 16: Europe Self-service Revenue (Billion), by Component 2026 & 2034
    17. Figure 17: Europe Self-service Revenue Share (%), by Component 2026 & 2034
    18. Figure 18: Europe Self-service Revenue (Billion), by End-User Industry 2026 & 2034
    19. Figure 19: Europe Self-service Revenue Share (%), by End-User Industry 2026 & 2034
    20. Figure 20: Europe Self-service Revenue (Billion), by Technology 2026 & 2034
    21. Figure 21: Europe Self-service Revenue Share (%), by Technology 2026 & 2034
    22. Figure 22: Europe Self-service Revenue (Billion), by Deployment Location 2026 & 2034
    23. Figure 23: Europe Self-service Revenue Share (%), by Deployment Location 2026 & 2034
    24. Figure 24: Europe Self-service Revenue (Billion), by Country 2026 & 2034
    25. Figure 25: Europe Self-service Revenue Share (%), by Country 2026 & 2034
    26. Figure 26: Asia Pacific Self-service Revenue (Billion), by Product Type 2026 & 2034
    27. Figure 27: Asia Pacific Self-service Revenue Share (%), by Product Type 2026 & 2034
    28. Figure 28: Asia Pacific Self-service Revenue (Billion), by Component 2026 & 2034
    29. Figure 29: Asia Pacific Self-service Revenue Share (%), by Component 2026 & 2034
    30. Figure 30: Asia Pacific Self-service Revenue (Billion), by End-User Industry 2026 & 2034
    31. Figure 31: Asia Pacific Self-service Revenue Share (%), by End-User Industry 2026 & 2034
    32. Figure 32: Asia Pacific Self-service Revenue (Billion), by Technology 2026 & 2034
    33. Figure 33: Asia Pacific Self-service Revenue Share (%), by Technology 2026 & 2034
    34. Figure 34: Asia Pacific Self-service Revenue (Billion), by Deployment Location 2026 & 2034
    35. Figure 35: Asia Pacific Self-service Revenue Share (%), by Deployment Location 2026 & 2034
    36. Figure 36: Asia Pacific Self-service Revenue (Billion), by Country 2026 & 2034
    37. Figure 37: Asia Pacific Self-service Revenue Share (%), by Country 2026 & 2034
    38. Figure 38: South America Self-service Revenue (Billion), by Product Type 2026 & 2034
    39. Figure 39: South America Self-service Revenue Share (%), by Product Type 2026 & 2034
    40. Figure 40: South America Self-service Revenue (Billion), by Component 2026 & 2034
    41. Figure 41: South America Self-service Revenue Share (%), by Component 2026 & 2034
    42. Figure 42: South America Self-service Revenue (Billion), by End-User Industry 2026 & 2034
    43. Figure 43: South America Self-service Revenue Share (%), by End-User Industry 2026 & 2034
    44. Figure 44: South America Self-service Revenue (Billion), by Technology 2026 & 2034
    45. Figure 45: South America Self-service Revenue Share (%), by Technology 2026 & 2034
    46. Figure 46: South America Self-service Revenue (Billion), by Deployment Location 2026 & 2034
    47. Figure 47: South America Self-service Revenue Share (%), by Deployment Location 2026 & 2034
    48. Figure 48: South America Self-service Revenue (Billion), by Country 2026 & 2034
    49. Figure 49: South America Self-service Revenue Share (%), by Country 2026 & 2034
    50. Figure 50: Middle East & Africa Self-service Revenue (Billion), by Product Type 2026 & 2034
    51. Figure 51: Middle East & Africa Self-service Revenue Share (%), by Product Type 2026 & 2034
    52. Figure 52: Middle East & Africa Self-service Revenue (Billion), by Component 2026 & 2034
    53. Figure 53: Middle East & Africa Self-service Revenue Share (%), by Component 2026 & 2034
    54. Figure 54: Middle East & Africa Self-service Revenue (Billion), by End-User Industry 2026 & 2034
    55. Figure 55: Middle East & Africa Self-service Revenue Share (%), by End-User Industry 2026 & 2034
    56. Figure 56: Middle East & Africa Self-service Revenue (Billion), by Technology 2026 & 2034
    57. Figure 57: Middle East & Africa Self-service Revenue Share (%), by Technology 2026 & 2034
    58. Figure 58: Middle East & Africa Self-service Revenue (Billion), by Deployment Location 2026 & 2034
    59. Figure 59: Middle East & Africa Self-service Revenue Share (%), by Deployment Location 2026 & 2034
    60. Figure 60: Middle East & Africa Self-service Revenue (Billion), by Country 2026 & 2034
    61. Figure 61: Middle East & Africa Self-service Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Self-service Revenue Billion Forecast, by Product Type 2020 & 2034
    2. Table 2: Global Self-service Revenue Billion Forecast, by Component 2020 & 2034
    3. Table 3: Global Self-service Revenue Billion Forecast, by End-User Industry 2020 & 2034
    4. Table 4: Global Self-service Revenue Billion Forecast, by Technology 2020 & 2034
    5. Table 5: Global Self-service Revenue Billion Forecast, by Deployment Location 2020 & 2034
    6. Table 6: Global Self-service Revenue Billion Forecast, by Region 2020 & 2034
    7. Table 7: North America Self-service Revenue Billion Forecast, by Product Type 2020 & 2034
    8. Table 8: North America Self-service Revenue Billion Forecast, by Component 2020 & 2034
    9. Table 9: North America Self-service Revenue Billion Forecast, by End-User Industry 2020 & 2034
    10. Table 10: North America Self-service Revenue Billion Forecast, by Technology 2020 & 2034
    11. Table 11: North America Self-service Revenue Billion Forecast, by Deployment Location 2020 & 2034
    12. Table 12: North America Self-service Revenue Billion Forecast, by Country 2020 & 2034
    13. Table 13: USA Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: Canada Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    15. Table 15: Mexico Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    16. Table 16: Europe Self-service Revenue Billion Forecast, by Product Type 2020 & 2034
    17. Table 17: Europe Self-service Revenue Billion Forecast, by Component 2020 & 2034
    18. Table 18: Europe Self-service Revenue Billion Forecast, by End-User Industry 2020 & 2034
    19. Table 19: Europe Self-service Revenue Billion Forecast, by Technology 2020 & 2034
    20. Table 20: Europe Self-service Revenue Billion Forecast, by Deployment Location 2020 & 2034
    21. Table 21: Europe Self-service Revenue Billion Forecast, by Country 2020 & 2034
    22. Table 22: Germany Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    23. Table 23: UK Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: France Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    25. Table 25: Italy Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    26. Table 26: Spain Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    27. Table 27: NORDIC Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    28. Table 28: Asia Pacific Self-service Revenue Billion Forecast, by Product Type 2020 & 2034
    29. Table 29: Asia Pacific Self-service Revenue Billion Forecast, by Component 2020 & 2034
    30. Table 30: Asia Pacific Self-service Revenue Billion Forecast, by End-User Industry 2020 & 2034
    31. Table 31: Asia Pacific Self-service Revenue Billion Forecast, by Technology 2020 & 2034
    32. Table 32: Asia Pacific Self-service Revenue Billion Forecast, by Deployment Location 2020 & 2034
    33. Table 33: Asia Pacific Self-service Revenue Billion Forecast, by Country 2020 & 2034
    34. Table 34: China Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    35. Table 35: Japan Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    36. Table 36: India Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    37. Table 37: South Korea Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    38. Table 38: Singapore Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    39. Table 39: Australia Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    40. Table 40: Indonesia Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    41. Table 41: South America Self-service Revenue Billion Forecast, by Product Type 2020 & 2034
    42. Table 42: South America Self-service Revenue Billion Forecast, by Component 2020 & 2034
    43. Table 43: South America Self-service Revenue Billion Forecast, by End-User Industry 2020 & 2034
    44. Table 44: South America Self-service Revenue Billion Forecast, by Technology 2020 & 2034
    45. Table 45: South America Self-service Revenue Billion Forecast, by Deployment Location 2020 & 2034
    46. Table 46: South America Self-service Revenue Billion Forecast, by Country 2020 & 2034
    47. Table 47: Brazil Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    48. Table 48: Mexico Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    49. Table 49: Argentina Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    50. Table 50: Middle East & Africa Self-service Revenue Billion Forecast, by Product Type 2020 & 2034
    51. Table 51: Middle East & Africa Self-service Revenue Billion Forecast, by Component 2020 & 2034
    52. Table 52: Middle East & Africa Self-service Revenue Billion Forecast, by End-User Industry 2020 & 2034
    53. Table 53: Middle East & Africa Self-service Revenue Billion Forecast, by Technology 2020 & 2034
    54. Table 54: Middle East & Africa Self-service Revenue Billion Forecast, by Deployment Location 2020 & 2034
    55. Table 55: Middle East & Africa Self-service Revenue Billion Forecast, by Country 2020 & 2034
    56. Table 56: GCC Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    57. Table 57: Israel Self-service Revenue (Billion) Forecast, by Application 2020 & 2034
    58. Table 58: South Africa Self-service Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the size of the self-service market in 2026?

    Our proprietary primary research sizes the global self-service market at USD 45.1 billion in 2026, with a projected expansion to USD 132.5 billion by 2033 at a 16.7% CAGR.

    2Which region is the largest market for self-service technology?

    Asia-Pacific is the largest regional market, accounting for 38.0% of global revenue in 2025, and it is also the fastest-growing region, posting CAGRs near 8.2%–9.4% through the forecast.

    3Which self-service product segment is growing fastest?

    Vending machines are the fastest-growing product segment at approximately 17.0% CAGR, followed by self-checkout systems at 8.63% CAGR, driven by unattended retail and QSR adoption.

    4Who are the leading companies in the self-service market?

    Leading players include NCR Corporation / NCR Atleos, Diebold Nixdorf, Fujitsu, Zebra Technologies, HESS Cash Systems, KIOSK Information Systems, Olea Kiosks, and Posiflex.

    5What are the main barriers to self-service deployment?

    Persistent vandalism and cash-handling security risk (−0.8% CAGR impact) and high total cost of ownership for outdoor deployments (−0.6% CAGR impact) are the principal restraints, alongside high upfront hardware and integration costs for smaller operators.

    6How large is the self-service kiosk segment specifically?

    Kiosks led the broader self-service market with 35.74% share in 2025, while dedicated kiosk-market estimates place the segment in the USD 16.01 billion range in 2026, growing at a double-digit CAGR through the next decade.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Approximately 70–80% of the evidence base is derived from primary research, including structured interviews, expert calls, and operator surveys conducted by our in-house analyst team.
    • We interview kiosk and terminal OEMs, payment-terminal and display suppliers, self-service software platform vendors, systems integrators and field-service providers, and venue operators across retail, QSR, banking, healthcare, transport, and government services.
    • Stakeholder designations interviewed include VP of Retail Operations, Head of Branch Transformation / Channel Strategy, Chief Information Officer (CIO), and Procurement Director responsible for terminal fleet acquisition.
    • We benchmark against standards and guidance from recognized bodies including the PCI Security Standards Council (https://www.pcisecuritystandards.org), EMVCo (https://www.emvco.com), Kiosk Manufacturers Association, and the OECD (https://www.oecd.org) for public-sector self-service channel adoption.
    • Primary evidence is triangulated with operator-reported transaction volumes, fleet uptime logs, and deployment pipeline disclosures.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    VP of Retail Operations28%
    Head of Branch Transformation / Channel Strategy26%
    Chief Information Officer (CIO)24%
    Procurement Director22%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Kiosk & Terminal OEMs30%
    Payment Terminal & Display Suppliers20%
    Self-Service Software Platform Vendors18%
    Systems Integrators & Field-Service Providers17%
    Venue Operators (Retail, QSR, BFSI, Healthcare)15%

    Secondary Research & Industry Benchmarking

    • 20–30% of the research effort draws on secondary validation: regulatory filings, investor disclosures, official statistics, and technical standards documentation.
    • Financial and corporate data are validated through Bloomberg, Factiva, Hoovers, and PitchBook to confirm vendor revenue mix, installed-base disclosures, and recurring-service revenue splits.
    • Official multilateral and governmental sources — including the OECD Tax Administration series, World Bank (https://www.worldbank.org), Eurostat (https://ec.europa.eu/eurostat), and UN Comtrade (https://comtrade.un.org) — are used for payment-penetration, retail-format, and trade-flow benchmarks.
    • Recognized non-profit and technical trade associations are referenced for standards, accessibility guidance, and certification cycles. No commercial market research portals are used as sources.

    Demand Modeling & Market Estimation

    • We apply top-down and bottom-up methodologies simultaneously, reconciled through multi-level data triangulation at product, component, vertical, and geographic levels.
    • The bottom-up calculation aggregates unit shipments × average selling price by product family, installed-base size × annual software/service attach rate, and venue-level transaction throughput × terminal count across sampled operators.
    • Quantitative metrics in the model include terminal units shipped, average revenue per installed device, software and service attach rates, and transaction volume per terminal per day.
    • Geographic and vertical splits are cross-validated against operator capex plans and public procurement announcements to ensure internal consistency.

    Data Accuracy & Quality Check

    • We guarantee an estimated data accuracy level of 85–90%, achieved through multi-source triangulation, outlier flagging, and analyst review gates.
    • Every report is updated to the date of purchase, incorporating the latest deployment announcements, contract awards, and regulatory changes.
    • Sensitivity analysis tests CAGR outcomes against alternative adoption and pricing scenarios before final publication.
    • Final figures are reviewed by a senior industry analyst panel prior to release to ensure consistency across segments and regions.