Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Computer Repair & Refurbishment Service Market Report 2026 | Insight Market Data
Professional and Commercial Services / MARKET REPORT
Computer Repair and Refurbishment Service | Insight Market Data
Computer Repair and Refurbishment Service by Type (Desktop Computer, Laptop, Others), by Service Scope (Break-Fix Repair, Software Remediation, Others), by Delivery Model (Walk-In Retail, Depot Repair, Others), by Application (Enterprise, Educational Institution, Individual, Government, Others), by North America (United States, Canada), by Europe (United Kingdom, Germany, France, Netherlands), by Asia-Pacific (China, India, Japan, South Korea, ASEAN), by South America (Brazil, Mexico), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034
Self-service market valued at USD 45.1B in 2026, growing at 16.7% CAGR to reach USD 132.5B by 2033. Analysis of kiosks, ATMs, and self-checkout.
Nov 2026|233 pages
$2900.00
BIM consulting service market valued at USD 7.8 Billion in 2023, projected to reach USD 15.1 Billion by 2031 at 13.8% CAGR. Get full analysis.
Nov 2026|237 pages
$2900.00
Environmental Engineering Service market to reach $90 Billion by 2035 at 3.0% CAGR. Get exclusive data on trends, drivers, and competitive landscape.
Nov 2026|260 pages
$2900.00
The Cyber Security Incident Response and Recovery Service market is valued at USD 49.71 Billion in 2026, growing at 18.52% CAGR to reach USD 116.17 Billion by 2031.
Executive Overview: The $5.3 Billion Service Economy
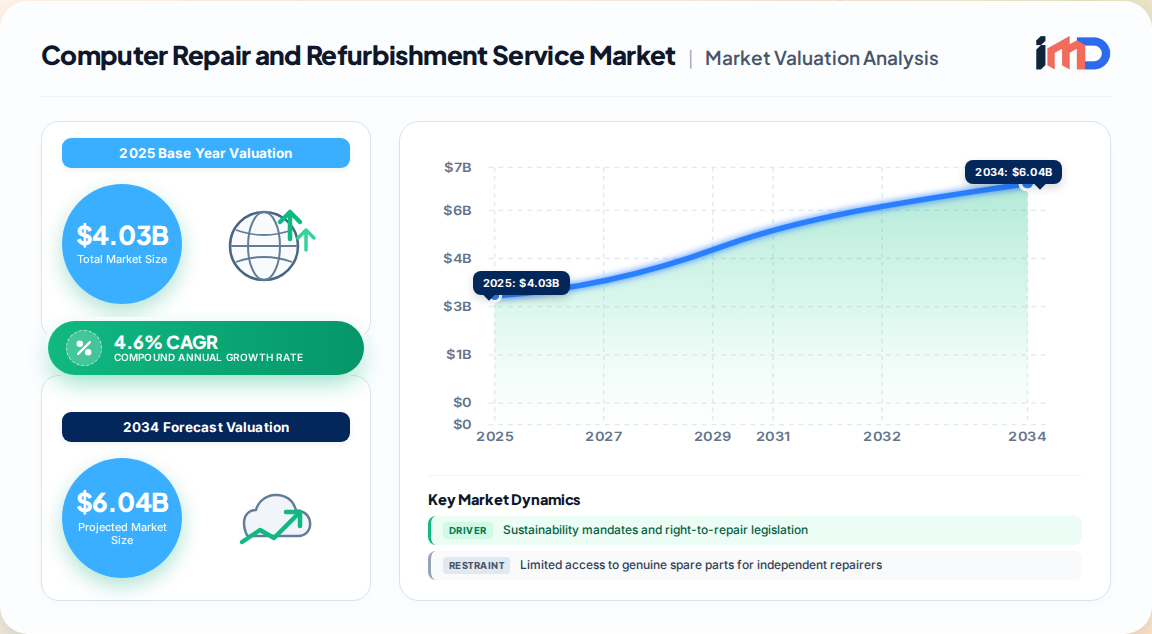
The global Computer Repair and Refurbishment Service market is undergoing a structural transformation from a fragmented, reactive aftersales activity into a strategically managed, technology-enabled service ecosystem. Our proprietary primary research estimates the global market will reach $5.29 Billion by 2032, expanding at a 4.6% CAGR from a 2025 base of approximately $3.85 Billion. This growth is not merely a function of device failure; it is driven by a confluence of macroeconomic, regulatory, and technological forces that are reshaping how enterprises and consumers manage IT asset lifecycles.
Computer Repair and Refurbishment Service Market Size (In Billion)
7.5B
6.0B
4.5B
3.0B
1.5B
0
4.030 B
2025
4.215 B
2026
4.409 B
2027
4.612 B
2028
4.824 B
2029
5.046 B
2030
5.278 B
2031
While the broader consumer electronics repair and maintenance sector is projected to grow at a faster 6.8% CAGR to reach $39.2 Billion by 2032, the computer-specific segment exhibits distinct dynamics. The United States alone represents a $19.8 Billion repair services industry (2023), characterized by high average spending and a mature refurbishment infrastructure. However, the global market's growth trajectory is increasingly influenced by the Asia-Pacific region, which dominates volume and is expected to record the fastest expansion through 2032.
This report provides a first-party, data-driven examination of the market's value chain, competitive landscape, and strategic opportunities. Key findings reveal that refurbishment and reconditioning is the fastest-growing service segment, propelled by the global expansion of certified pre-owned electronics programs. Furthermore, the rise of AI-assisted diagnostics and doorstep repair models is enabling organized service providers to scale operations and compete effectively against informal repair networks.
Market Drivers, Restraints, and Strategic Challenges
The market's expansion is fueled by several powerful tailwinds, yet it also faces significant headwinds that require strategic navigation.
Primary Growth Drivers:
Sustainability and Circular Economy Mandates: Governments and corporations are aggressively pursuing e-waste reduction targets. The European Union's right-to-repair legislation and similar initiatives in the U.S. are compelling OEMs to improve spare parts availability and documentation access, directly benefiting independent and authorized repair networks alike.
Extended Device Replacement Cycles: Inflation-sensitive consumers and budget-conscious enterprises are delaying hardware upgrades. In the U.S., 72% of users delay laptop repairs due to cost concerns, yet the average consumer still spends $250 annually on device repairs, indicating a strong willingness to repair rather than replace when accessible.
Refurbished Electronics Ecosystem Expansion: The global acceptance of refurbished smartphones, laptops, and gaming systems is creating robust demand for testing, grading, data sanitization, and certified repair services. This is particularly pronounced in North America and Europe, where certified pre-owned programs are gaining mainstream traction.
Enterprise Device Lifecycle Management: Hybrid work adoption has increased reliance on laptops and mobile devices. Enterprises are increasingly outsourcing repair and maintenance through managed service contracts to minimize downtime and extend fleet lifespan. 89% of U.S. corporate clients demand SLAs for repairs, highlighting the shift toward service-level-driven procurement.
Key Restraints and Challenges:
Limited Access to Genuine Spare Parts: Independent repair providers continue to face challenges sourcing authentic components for premium devices. OEM-controlled repair ecosystems and software-linked component verification systems can limit repair flexibility, particularly for Apple and Samsung devices.
High Complexity of Modern Electronics: Advanced chipsets, sealed hardware designs, and compact architectures (e.g., foldable displays) increase repair difficulty. This necessitates continuous investment in micro-soldering tools, AI-assisted diagnostics, and technician training, raising barriers to entry.
Skilled Technician Shortage: The demand for component-level repair and advanced diagnostics is outpacing the supply of trained professionals. In the U.S., the average hourly wage for repair techs was $24.50 in 2023, with 42% of jobs requiring certification, indicating a need for structured apprenticeship programs.
Data Privacy and Security Concerns: Consumers and enterprises remain cautious about exposing sensitive data during servicing. Providers must invest in secure diagnostics, data protection protocols, and certified data sanitization processes to build trust.
Value Chain and Service Delivery Model Analysis
The value chain for computer repair and refurbishment services is evolving from linear, transactional models to integrated, circular ecosystems. Our analysis identifies four primary stages:
Device Intake and Diagnostics: This stage involves walk-in retail, on-site enterprise service, depot repair, and integrated IT asset recovery (reverse logistics). AI-assisted diagnostic platforms are increasingly deployed to reduce troubleshooting time and improve accuracy.
Repair and Refurbishment Operations: Activities range from break-fix repair (hardware replacement, board-level repair) and software remediation to standardized grading, secure data sanitization, and cosmetic restoration. Hardware repair currently dominates, contributing 55%–60% of total service revenue, but refurbishment and reconditioning is the fastest-growing segment.
Certification and Quality Assurance: Refurbished devices undergo rigorous testing, grading, and certification to meet resale or redeployment standards. This stage is critical for building consumer trust in the secondary market.
Redeployment and Remarketing: Devices are either returned to the enterprise fleet, sold through certified pre-owned channels, or responsibly recycled. This stage is increasingly managed through digital platforms that track device lifecycle and warranty status.
Delivery Model Shifts: The market is witnessing a clear shift toward doorstep and subscription-based repair models, particularly in urban centers. 54% of consumers now use online booking for repairs, and 70% of Australian consumers prefer same-day service. This is driving the growth of on-demand mobile repair providers and pickup-and-drop services offered by retail and e-commerce networks.
Regional Outlook and Investment Attractiveness
The global market exhibits significant regional variation in terms of repair culture, regulatory support, and service infrastructure maturity.
Computer Repair and Refurbishment Service Regional Market Share
Loading chart...
Region
Market Share (2025)
Key Characteristics
Growth Outlook (2026-2032)
North America
28%
High-value repair market, premium device ownership, insurance-linked services, strong refurbishment demand. U.S. market is highly fragmented with 48,500 businesses employing 112,400 technicians.
Moderate growth driven by right-to-repair legislation and enterprise lifecycle management.
Europe
24%
Policy-driven growth due to sustainability initiatives and circular economy targets. 66% of German consumers value certified technicians, and 51% of UK users use insurance for gadget repairs.
Strong growth potential, particularly in Western Europe, supported by EU regulations.
Asia-Pacific
38%
Largest volume market globally. Massive smartphone and PC user base, extensive independent repair ecosystem. China is a major hub for spare parts and refurbishment. India is emerging as a fast-growing organized repair market.
Fastest growth, projected to outpace other regions due to rising electronics consumption and app-based repair platforms.
South America
5%
Price-sensitive market. 82% of low-income consumers in Brazil choose the cheapest option. Informal repair providers dominate, but organized chains are increasing.
Gradual expansion, hindered by counterfeit components and uneven access to certified infrastructure.
Middle East & Africa
5%
Underpenetrated but growing. Gulf countries show demand for premium servicing; African markets rely heavily on independent technicians and secondary electronics markets.
Long-term growth potential driven by rising smartphone penetration and portable repair models.
Investment Opportunity Assessment:
North America and Europe offer the most attractive opportunities for investment in certified refurbishment operations, AI-driven diagnostics platforms, and enterprise device lifecycle management services. The regulatory environment is favorable, and consumer willingness to pay for quality and convenience is high.
Asia-Pacific presents a high-volume opportunity for scalable repair chain models and digital service aggregation platforms, particularly in India and Southeast Asia. The challenge lies in navigating price sensitivity and informal competition.
Latin America and Middle East & Africa are strategic for low-cost component-level repair and refurbished device distribution, though infrastructure and regulatory challenges remain.
Competitive Landscape and Strategic White-Space Analysis
The market is highly fragmented, but the organized segment is gaining share. Competition is shifting from low-cost repair availability to diagnostics quality, data security, turnaround time, and service coverage.
Key Players and Strategies:
OEM-Authorized Networks (Apple, Dell, HP, Lenovo, Samsung): Leverage genuine parts, warranty compliance, and software-linked diagnostics. Apple and Samsung dominate premium device repair, while Dell and HP hold strong positions in enterprise and educational laptop maintenance.
Third-Party Repair Chains (uBreakiFix by Asurion, Best Buy): Benefit from retail density, insurance partnerships, and multi-brand servicing. These players are expanding through franchise models and same-day repair offerings.
Refurbishment Specialists (Recompute, Reboot Systems, GigaRefurb, Blair Tech): Capitalize on the growing secondary market for electronics. Their competitive edge lies in standardized grading, data sanitization, and certification processes.
Repair Enablement Platforms (iFixit): Occupy a unique position by providing tools, parts, and repair guides to independent technicians and DIY consumers, shaping the right-to-repair movement.
Strategic White-Space Opportunities:
Subscription-Based Maintenance Plans for SMBs: While large enterprises have access to managed service contracts, small and medium-sized businesses (SMBs) remain underserved. A subscription model bundling preventive maintenance, priority repair, and device lifecycle management could capture a significant share of the 18% of revenue currently generated by preventive maintenance contracts in the U.S.
AI-Powered Diagnostic Platforms as a Service: Independent repair shops lack the resources to develop sophisticated diagnostic tools. Offering an AI-assisted diagnostic platform on a subscription basis could democratize access and improve repair accuracy across the fragmented segment.
Certified Refurbishment for Niche Categories: While smartphones and laptops dominate, there is growing demand for refurbished gaming consoles, wearables, and IoT devices. Early movers in these categories can establish certification standards and capture premium pricing.
Doorstep Repair for Enterprise Fleets: While doorstep repair is growing for consumers, there is untapped potential in offering on-site repair for enterprise devices, particularly for hybrid-work employees who may not have access to centralized IT support.
Import/Export and Supplier Dynamics
The computer repair and refurbishment service market is fundamentally a service-based industry, but it is deeply intertwined with the global trade of parts, components, and refurbished devices. While service delivery is typically localized, the supply chain for spare parts is highly globalized.
Trade Patterns:
Spare Parts Sourcing: The market relies heavily on the import/export of electronic components (e.g., screens, batteries, motherboards, connectors). China is the dominant global supplier of spare parts, with significant flows to North America, Europe, and Southeast Asia. According to UN Comtrade data (HS Code 84-85 for machinery and electronics), global trade in computer parts and accessories exceeded $1.2 Trillion in 2023, with a substantial portion destined for repair and refurbishment operations.
Refurbished Device Trade: The global trade of refurbished computers and laptops is a growing segment. Developed markets (U.S., EU) are net exporters of used devices, while emerging markets (India, Southeast Asia, Latin America) are net importers. This flow is facilitated by recognized standards for data sanitization and quality grading.
Supply Chain Risks: The dependency on concentrated manufacturing hubs (e.g., China, Taiwan) for critical components creates supply chain vulnerabilities. Parts sourcing costs rose 8% in 2023, and geopolitical tensions or trade restrictions could disrupt availability. Repair providers are increasingly seeking to diversify sourcing through regional distributors and authorized parts channels.
Supplier Dynamics:
The supplier landscape is composed of:
OEM-Authorized Parts Distributors: Provide genuine components but often at higher costs and with restrictions on usage.
Independent Parts Wholesalers: Offer compatible and aftermarket components at lower prices, but quality and authenticity can vary.
Device Harvesters (Parts Pulling): Recover functional components from end-of-life devices for reuse in repairs. This is a critical source for independent repair shops but raises quality assurance challenges.
Strategic Implication: Repair providers that can establish reliable, cost-effective, and transparent supplier networks will gain a significant competitive advantage. Building direct relationships with component manufacturers and investing in parts quality testing are key mitigation strategies.
Recent Developments and Future Outlook
The last two years have seen several pivotal developments that are shaping the market's future trajectory:
Expansion of Self-Service Repair Programs: Apple expanded its self-service repair program to additional regions, providing consumers and independent technicians with access to genuine parts, tools, and manuals. This is a direct response to right-to-repair pressure and is gradually reshaping the competitive balance.
AI-Assisted Diagnostics Adoption: Leading repair chains are deploying AI-powered diagnostic software for motherboard troubleshooting, battery health monitoring, and predictive maintenance. This technology is reducing turnaround times and improving technician productivity, particularly for complex repairs.
Growth of Doorstep Repair Models: Urban consumers increasingly prefer app-based booking and same-day service. Providers like uBreakiFix and various regional platforms are expanding their mobile repair fleets to meet this demand.
Certified Pre-Owned (CPO) Program Expansion: Major electronics retailers and e-commerce platforms are expanding their CPO programs, driving demand for refurbishment services such as testing, grading, and data sanitization.
Future Outlook:
By 2032, the market will likely be characterized by:
Consolidation in the Organized Segment: Larger, digitally enabled service chains will gain share from fragmented independent operators, particularly in North America and Europe.
Standardization of Refurbishment Quality: Industry-wide standards for grading and data sanitization will become more prevalent, building consumer trust and facilitating cross-border trade in refurbished devices.
Integration of Repair into Broader Lifecycle Services: Repair services will be increasingly bundled with device management, asset recovery, and ITAD (IT asset disposition) services, creating end-to-end lifecycle management solutions.
Sustainability as a Core Value Proposition: Repair and refurbishment will be marketed as key components of the circular economy, with providers emphasizing their role in reducing e-waste and extending product lifecycles.
This market is transitioning from an informal support industry into a more organized, technology-driven, and sustainability-linked service ecosystem. Companies that combine repair expertise, logistics efficiency, genuine component sourcing, and digital customer experience are expected to achieve long-term competitive advantage during the forecast period.
Computer Repair and Refurbishment Service Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Computer Repair and Refurbishment Service REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.6% from 2020-2034
Segmentation
By Type
Desktop Computer
Laptop
Others
By Service Scope
Break-Fix Repair
Table of Contents
1. Computer Repair and Refurbishment Service Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Computer Repair and Refurbishment Service Executive Summary
2.1. Market Snapshot
3. Computer Repair and Refurbishment Service Dynamics
3.1. Market Drivers
3.1.1. Sustainability mandates and right-to-repair legislation
3.1.2. Extended device replacement cycles due to inflation
3.1.3. Growth of the refurbished electronics ecosystem
3.1.4. Enterprise demand for device lifecycle management and SLAs
3.1.5. Rising adoption of premium consumer electronics
3.2. Market Trends
3.2.1. Growth of doorstep and subscription-based repair models
3.2.2. Rise of AI-assisted diagnostics and automated repair workflows
3.2.3. Expansion of certified pre-owned (CPO) refurbishment programs
3.2.4. Shift toward component-level repair (micro-soldering) over board replacement
3.2.5. Increasing integration of repair services with IT asset lifecycle management
3.3. Market Restraints
3.3.1. Limited access to genuine spare parts for independent repairers
3.3.2. High complexity of modern electronics (e.g., sealed designs, proprietary chips)
3.3.3. Skilled technician shortage and rising training costs
Software Remediation
Others
By Delivery Model
Walk-In Retail
Depot Repair
Others
By Application
Enterprise
Educational Institution
Individual
Government
Others
By Geography
North America
United States
Canada
Europe
United Kingdom
Germany
France
Netherlands
Asia-Pacific
China
India
Japan
South Korea
ASEAN
South America
Brazil
Mexico
Middle East & Africa
UAE
South Africa
3.3.4. Data privacy and security concerns during device servicing
3.3.5. Price sensitivity and dominance of informal repair providers in emerging markets
3.4. Market Challenges
3.4.1. Difficulty sourcing authentic components for premium brands
3.4.2. Managing logistics and turnaround time for depot repairs
3.4.3. Ensuring data sanitization compliance amidst evolving regulations
3.4.4. Competing with low-cost informal technicians in price-sensitive regions
4. Computer Repair and Refurbishment Service Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Computer Repair and Refurbishment Service Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Type
5.1.1. Desktop Computer
5.1.2. Laptop
5.1.3. Others
5.2. Analysis, Insights and Forecast - by Service Scope
5.2.1. Break-Fix Repair
5.2.2. Software Remediation
5.2.3. Others
5.3. Analysis, Insights and Forecast - by Delivery Model
5.3.1. Walk-In Retail
5.3.2. Depot Repair
5.3.3. Others
5.4. Analysis, Insights and Forecast - by Application
5.4.1. Enterprise
5.4.2. Educational Institution
5.4.3. Individual
5.4.4. Government
5.4.5. Others
5.5. Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia-Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. Computer Repair and Refurbishment Service North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Type
6.1.1. Desktop Computer
6.1.2. Laptop
6.1.3. Others
6.2. Analysis, Insights and Forecast - by Service Scope
6.2.1. Break-Fix Repair
6.2.2. Software Remediation
6.2.3. Others
6.3. Analysis, Insights and Forecast - by Delivery Model
6.3.1. Walk-In Retail
6.3.2. Depot Repair
6.3.3. Others
6.4. Analysis, Insights and Forecast - by Application
6.4.1. Enterprise
6.4.2. Educational Institution
6.4.3. Individual
6.4.4. Government
6.4.5. Others
7. Computer Repair and Refurbishment Service Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Type
7.1.1. Desktop Computer
7.1.2. Laptop
7.1.3. Others
7.2. Analysis, Insights and Forecast - by Service Scope
7.2.1. Break-Fix Repair
7.2.2. Software Remediation
7.2.3. Others
7.3. Analysis, Insights and Forecast - by Delivery Model
7.3.1. Walk-In Retail
7.3.2. Depot Repair
7.3.3. Others
7.4. Analysis, Insights and Forecast - by Application
7.4.1. Enterprise
7.4.2. Educational Institution
7.4.3. Individual
7.4.4. Government
7.4.5. Others
8. Computer Repair and Refurbishment Service Asia-Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Type
8.1.1. Desktop Computer
8.1.2. Laptop
8.1.3. Others
8.2. Analysis, Insights and Forecast - by Service Scope
8.2.1. Break-Fix Repair
8.2.2. Software Remediation
8.2.3. Others
8.3. Analysis, Insights and Forecast - by Delivery Model
8.3.1. Walk-In Retail
8.3.2. Depot Repair
8.3.3. Others
8.4. Analysis, Insights and Forecast - by Application
8.4.1. Enterprise
8.4.2. Educational Institution
8.4.3. Individual
8.4.4. Government
8.4.5. Others
9. Computer Repair and Refurbishment Service South America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Type
9.1.1. Desktop Computer
9.1.2. Laptop
9.1.3. Others
9.2. Analysis, Insights and Forecast - by Service Scope
9.2.1. Break-Fix Repair
9.2.2. Software Remediation
9.2.3. Others
9.3. Analysis, Insights and Forecast - by Delivery Model
9.3.1. Walk-In Retail
9.3.2. Depot Repair
9.3.3. Others
9.4. Analysis, Insights and Forecast - by Application
9.4.1. Enterprise
9.4.2. Educational Institution
9.4.3. Individual
9.4.4. Government
9.4.5. Others
10. Computer Repair and Refurbishment Service Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Type
10.1.1. Desktop Computer
10.1.2. Laptop
10.1.3. Others
10.2. Analysis, Insights and Forecast - by Service Scope
10.2.1. Break-Fix Repair
10.2.2. Software Remediation
10.2.3. Others
10.3. Analysis, Insights and Forecast - by Delivery Model
10.3.1. Walk-In Retail
10.3.2. Depot Repair
10.3.3. Others
10.4. Analysis, Insights and Forecast - by Application
10.4.1. Enterprise
10.4.2. Educational Institution
10.4.3. Individual
10.4.4. Government
10.4.5. Others
11. Computer Repair and Refurbishment Service Competitive Analysis
11.1. Company Profiles
11.1.1. Lenovo
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Apple
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Dell
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Acer
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. HP
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Asus
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Microsoft
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Advanced Skyline Technology Ltd (AST)
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Blair Tech
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Recompute
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Reboot Systems
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Refurbix
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. ReNew IT
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. GigaRefurb
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. OCM Business Systems
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Gazelle
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. TechSoup
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Best Buy
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. uBreakiFix by Asurion
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. iFixit
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Samsung Electronics
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Computer Repair and Refurbishment Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Computer Repair and Refurbishment Service Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Computer Repair and Refurbishment Service Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Computer Repair and Refurbishment Service Revenue (Billion), by Service Scope 2026 & 2034
Figure 5: North America Computer Repair and Refurbishment Service Revenue Share (%), by Service Scope 2026 & 2034
Figure 6: North America Computer Repair and Refurbishment Service Revenue (Billion), by Delivery Model 2026 & 2034
Figure 7: North America Computer Repair and Refurbishment Service Revenue Share (%), by Delivery Model 2026 & 2034
Figure 8: North America Computer Repair and Refurbishment Service Revenue (Billion), by Application 2026 & 2034
Figure 9: North America Computer Repair and Refurbishment Service Revenue Share (%), by Application 2026 & 2034
Figure 10: North America Computer Repair and Refurbishment Service Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Computer Repair and Refurbishment Service Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Computer Repair and Refurbishment Service Revenue (Billion), by Type 2026 & 2034
Figure 13: Europe Computer Repair and Refurbishment Service Revenue Share (%), by Type 2026 & 2034
Figure 14: Europe Computer Repair and Refurbishment Service Revenue (Billion), by Service Scope 2026 & 2034
Figure 15: Europe Computer Repair and Refurbishment Service Revenue Share (%), by Service Scope 2026 & 2034
Figure 16: Europe Computer Repair and Refurbishment Service Revenue (Billion), by Delivery Model 2026 & 2034
Figure 17: Europe Computer Repair and Refurbishment Service Revenue Share (%), by Delivery Model 2026 & 2034
Figure 18: Europe Computer Repair and Refurbishment Service Revenue (Billion), by Application 2026 & 2034
Figure 19: Europe Computer Repair and Refurbishment Service Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe Computer Repair and Refurbishment Service Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Computer Repair and Refurbishment Service Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia-Pacific Computer Repair and Refurbishment Service Revenue (Billion), by Type 2026 & 2034
Figure 23: Asia-Pacific Computer Repair and Refurbishment Service Revenue Share (%), by Type 2026 & 2034
Figure 24: Asia-Pacific Computer Repair and Refurbishment Service Revenue (Billion), by Service Scope 2026 & 2034
Figure 25: Asia-Pacific Computer Repair and Refurbishment Service Revenue Share (%), by Service Scope 2026 & 2034
Figure 26: Asia-Pacific Computer Repair and Refurbishment Service Revenue (Billion), by Delivery Model 2026 & 2034
Figure 27: Asia-Pacific Computer Repair and Refurbishment Service Revenue Share (%), by Delivery Model 2026 & 2034
Figure 28: Asia-Pacific Computer Repair and Refurbishment Service Revenue (Billion), by Application 2026 & 2034
Figure 29: Asia-Pacific Computer Repair and Refurbishment Service Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia-Pacific Computer Repair and Refurbishment Service Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia-Pacific Computer Repair and Refurbishment Service Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Computer Repair and Refurbishment Service Revenue (Billion), by Type 2026 & 2034
Figure 33: South America Computer Repair and Refurbishment Service Revenue Share (%), by Type 2026 & 2034
Figure 34: South America Computer Repair and Refurbishment Service Revenue (Billion), by Service Scope 2026 & 2034
Figure 35: South America Computer Repair and Refurbishment Service Revenue Share (%), by Service Scope 2026 & 2034
Figure 36: South America Computer Repair and Refurbishment Service Revenue (Billion), by Delivery Model 2026 & 2034
Figure 37: South America Computer Repair and Refurbishment Service Revenue Share (%), by Delivery Model 2026 & 2034
Figure 38: South America Computer Repair and Refurbishment Service Revenue (Billion), by Application 2026 & 2034
Figure 39: South America Computer Repair and Refurbishment Service Revenue Share (%), by Application 2026 & 2034
Figure 40: South America Computer Repair and Refurbishment Service Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Computer Repair and Refurbishment Service Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Computer Repair and Refurbishment Service Revenue (Billion), by Type 2026 & 2034
Figure 43: Middle East & Africa Computer Repair and Refurbishment Service Revenue Share (%), by Type 2026 & 2034
Figure 44: Middle East & Africa Computer Repair and Refurbishment Service Revenue (Billion), by Service Scope 2026 & 2034
Figure 45: Middle East & Africa Computer Repair and Refurbishment Service Revenue Share (%), by Service Scope 2026 & 2034
Figure 46: Middle East & Africa Computer Repair and Refurbishment Service Revenue (Billion), by Delivery Model 2026 & 2034
Figure 47: Middle East & Africa Computer Repair and Refurbishment Service Revenue Share (%), by Delivery Model 2026 & 2034
Figure 48: Middle East & Africa Computer Repair and Refurbishment Service Revenue (Billion), by Application 2026 & 2034
Figure 49: Middle East & Africa Computer Repair and Refurbishment Service Revenue Share (%), by Application 2026 & 2034
Figure 50: Middle East & Africa Computer Repair and Refurbishment Service Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Computer Repair and Refurbishment Service Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Computer Repair and Refurbishment Service Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Global Computer Repair and Refurbishment Service Revenue Billion Forecast, by Service Scope 2020 & 2034
Table 3: Global Computer Repair and Refurbishment Service Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 4: Global Computer Repair and Refurbishment Service Revenue Billion Forecast, by Application 2020 & 2034
Table 5: Global Computer Repair and Refurbishment Service Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Type 2020 & 2034
Table 7: North America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Service Scope 2020 & 2034
Table 8: North America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 9: North America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Application 2020 & 2034
Table 10: North America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Country 2020 & 2034
Table 11: United States Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Europe Computer Repair and Refurbishment Service Revenue Billion Forecast, by Type 2020 & 2034
Table 14: Europe Computer Repair and Refurbishment Service Revenue Billion Forecast, by Service Scope 2020 & 2034
Table 15: Europe Computer Repair and Refurbishment Service Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 16: Europe Computer Repair and Refurbishment Service Revenue Billion Forecast, by Application 2020 & 2034
Table 17: Europe Computer Repair and Refurbishment Service Revenue Billion Forecast, by Country 2020 & 2034
Table 18: United Kingdom Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: Germany Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: France Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Netherlands Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Asia-Pacific Computer Repair and Refurbishment Service Revenue Billion Forecast, by Type 2020 & 2034
Table 23: Asia-Pacific Computer Repair and Refurbishment Service Revenue Billion Forecast, by Service Scope 2020 & 2034
Table 24: Asia-Pacific Computer Repair and Refurbishment Service Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 25: Asia-Pacific Computer Repair and Refurbishment Service Revenue Billion Forecast, by Application 2020 & 2034
Table 26: Asia-Pacific Computer Repair and Refurbishment Service Revenue Billion Forecast, by Country 2020 & 2034
Table 27: China Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: India Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Japan Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: South Korea Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: ASEAN Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: South America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Type 2020 & 2034
Table 33: South America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Service Scope 2020 & 2034
Table 34: South America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 35: South America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Application 2020 & 2034
Table 36: South America Computer Repair and Refurbishment Service Revenue Billion Forecast, by Country 2020 & 2034
Table 37: Brazil Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Mexico Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: Middle East & Africa Computer Repair and Refurbishment Service Revenue Billion Forecast, by Type 2020 & 2034
Table 40: Middle East & Africa Computer Repair and Refurbishment Service Revenue Billion Forecast, by Service Scope 2020 & 2034
Table 41: Middle East & Africa Computer Repair and Refurbishment Service Revenue Billion Forecast, by Delivery Model 2020 & 2034
Table 42: Middle East & Africa Computer Repair and Refurbishment Service Revenue Billion Forecast, by Application 2020 & 2034
Table 43: Middle East & Africa Computer Repair and Refurbishment Service Revenue Billion Forecast, by Country 2020 & 2034
Table 44: UAE Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: South Africa Computer Repair and Refurbishment Service Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the global market size for computer repair and refurbishment services in 2026?
Our primary research estimates the global Computer Repair and Refurbishment Service market will reach approximately $4.03 Billion in 2026, with the market projected to grow to $5.29 Billion by 2032 at a 4.6% CAGR.
2Which region dominates the computer repair and refurbishment service market?
Asia-Pacific represents the largest volume market, accounting for approximately 38% of global market share in 2025. The region benefits from a massive electronics user base, extensive independent repair infrastructure, and strong growth in smartphone and laptop adoption.
3What are the key drivers of the computer repair and refurbishment market?
Key drivers include sustainability mandates and right-to-repair legislation, extended device replacement cycles, growth of the refurbished electronics ecosystem, and enterprise device lifecycle management needs. For instance, 72% of U.S. users delay laptop repairs due to cost, yet the average consumer spends $250 annually on device repairs.
4Who are the major players in the computer repair and refurbishment service market?
Major players include OEM-authorized networks like Apple, Dell, HP, and Lenovo; third-party repair chains such as uBreakiFix by Asurion and Best Buy; and refurbishment specialists like Recompute, Reboot Systems, and GigaRefurb. These companies are profiled based on revenue, service portfolio, and geographic presence.
5What is the outlook for refurbishment services in this market?
Refurbishment and reconditioning is the fastest-growing service segment, projected to expand at a robust pace through 2032. This growth is driven by the global expansion of certified pre-owned electronics programs and increasing consumer acceptance of refurbished devices, particularly in North America and Europe.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our study utilized a blended research approach, with 70–80% primary research forming the foundation of our analysis. We conducted extensive interviews across the value chain to capture granular insights.
We interviewed 4–5 specific company types, including OEM-authorized service centers (e.g., Apple, Dell, HP), independent repair shops, third-party service chains (e.g., uBreakiFix), refurbishment specialists, and ITAD/asset recovery firms.
We engaged with 3–4 stakeholder job titles, including Service Operations Directors, IT Asset Managers, Procurement Heads, and Sustainability Officers, to understand service procurement and lifecycle management strategies.
Data was validated via multi-level triangulation, cross-referencing interview findings with supply-side and demand-side indicators.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Service Operations Directors
30%
IT Asset Managers
25%
Procurement Heads
25%
Sustainability Officers
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
OEM-Authorized Service Centers
25%
Independent Repair Shops
35%
Refurbishment Specialists
20%
Third-Party Service Chains
15%
ITAD & Asset Recovery Firms
5%
Secondary Research & Industry Benchmarking
The remaining 20–30% of research involved secondary data collection and verification from authoritative sources.
We benchmarked our findings against official trade statistics from UN Comtrade (HS codes 84-85) to analyze parts and refurbished device flows. We also referenced data from the OECD and national statistical offices (e.g., U.S. Census Bureau, Eurostat).
Industry benchmarks were sourced from recognized non-profit trade associations, including the Consumer Technology Association (CTA) and the Electronic Frontiers Foundation (EFF) for right-to-repair context.
We utilized standard financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook to assess company financials and M&A activity.
Demand Modeling & Market Estimation
We employed simultaneous top-down and bottom-up methodologies to size the global market and validate regional segmentations.
Bottom-up estimation was built by aggregating revenue from thousands of service providers, validated against 4 specific quantitative metrics: average revenue per repair ticket (e.g., $85 in the U.S.), number of active repair businesses (e.g., 48,500 in the U.S.), average annual revenue per business (e.g., $410,000), and service frequency per device (e.g., 2.3 visits per customer yearly).
Top-down sizing was derived from the total installed base of computers (desktops, laptops, workstations) and average annual repair and refurbishment spending per device, cross-checked against industry revenue data.
Regional and segment-level forecasts were developed using econometric models that incorporate drivers such as GDP growth, electronics ownership rates, and regulatory changes.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%. All data points are verified by industry analysts and cross-validated through multiple sources.
Every report is updated to the date of purchase, ensuring the latest market developments and financial data are reflected.
We apply a rigorous quality check process, including outlier detection, trend validation, and consistency checks across the value chain. Where gaps exist, we clearly state assumptions and provide a range rather than a single point estimate.
Our methodology adheres to the highest standards of market research ethics, with zero reliance on competitor reports or third-party commercial research portals.