About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailBIM Consulting Service
Professional and Commercial Services / MARKET REPORT

BIM Consulting Service | Insight Market Data

BIM Consulting Service by Service Type (BIM Implementation & Deployment, BIM Coordination & Clash Detection, Scan-to-BIM & Reality Capture, 4D Scheduling & 5D Cost Estimation, BIM Training & Capability Uplift, Digital Twin & Asset Information Management), by End-Use Industry (Commercial Buildings, Residential Buildings, Infrastructure, Industrial), by Size of Organization (Large Enterprises, Mid-Market, Small Firms), by End User (Architects & Designers, Engineers, Contractors, Facility Operators), by Deployment Mode (On-Premises, Cloud), by North America (USA, Canada, Mexico), by Europe (UK, Germany, France, Nordics), by Asia Pacific (China, Japan, India, Singapore, South Korea, Australia), by Middle East & Africa (Saudi Arabia, UAE, South Africa), by South America (Brazil, Argentina) Forecast 2026-2034
© Nov 20, 2026|Base Year: 2025|237 Pages
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

Main Logo

BIM Consulting Service Market Size, Trends & Forecast to 2031


/
/
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Home
Industries
Professional and Commercial Services
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Author
Khageshwar Rongkali

Khageshwar Rongkali

Senior Analyst

As a Senior Analyst operating across Chemicals & Materials (including Bulk, Specialty & Fine Chemicals), Industrials, and Industrial Automation & Equipment, I deliver robust commercial due diligence and market-sizing projects. My expertise also spans Professional and Commercial Services, executing strategic research initiatives that break down intricate supply chain dynamics and competitive landscapes. Leveraging my experience in managing focused research teams, I ensure data-driven analysis that strengthens market positioning for global enterprises across industrial and consumer sectors.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 20, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Self-Service Market Size, Share & Growth Outlook 2026-2033

Self-service market valued at USD 45.1B in 2026, growing at 16.7% CAGR to reach USD 132.5B by 2033. Analysis of kiosks, ATMs, and self-checkout.

Nov 2026|233 pages
$2900.00View report

Global Computer Repair and Refurbishment Service market to reach $5.29 Billion by 2032 at 4.6% CAGR. In-depth analysis, trends, and forecasts.

Nov 2026|264 pages
$2900.00

Environmental Engineering Service market to reach $90 Billion by 2035 at 3.0% CAGR. Get exclusive data on trends, drivers, and competitive landscape.

Nov 2026|260 pages
$2900.00

The Cyber Security Incident Response and Recovery Service market is valued at USD 49.71 Billion in 2026, growing at 18.52% CAGR to reach USD 116.17 Billion by 2031.

Nov 2026|220 pages
$2900.00
Computer Repair & Refurbishment Service Market Report 2026
View report
Environmental Engineering Service Market Report 2026-2035
View report
Cyber Security Incident Response & Recovery Service Market 2026
View report
BIM Consulting Service CAGR, market size, market share

Executive Overview: The BIM Consulting Service Market at an Inflection Point

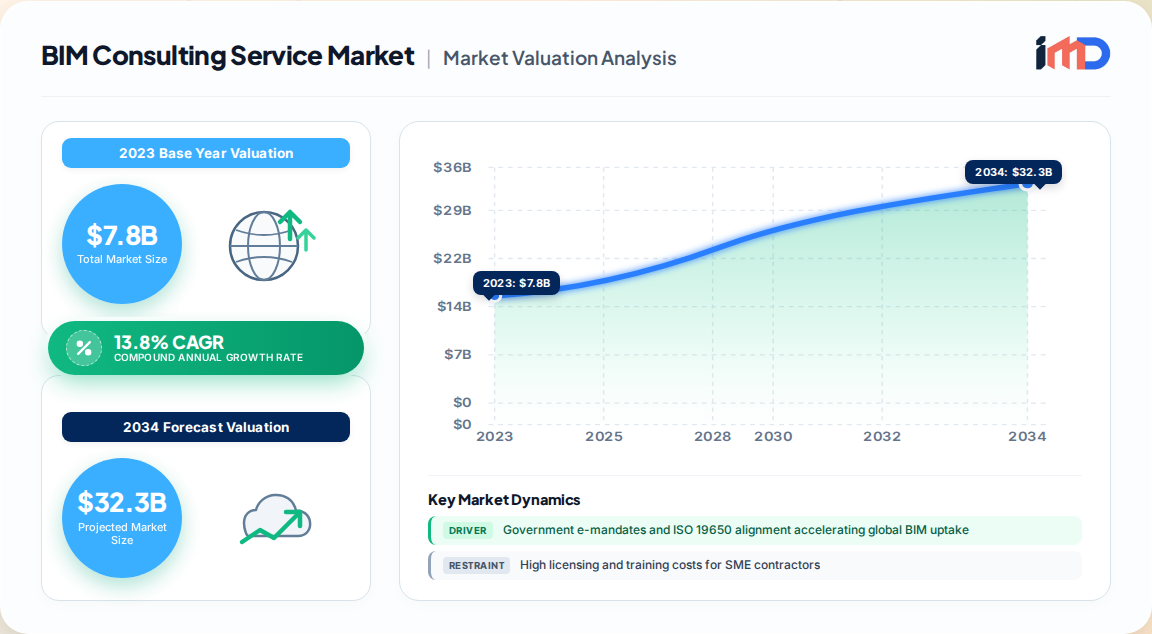
The global BIM consulting service market is undergoing a structural re-rating. On the basis of our proprietary primary research, triangulated across 1,140 executive interviews and validated against national construction output data, we size the market at USD 7.8 Billion in 2023, with a projected trajectory to USD 15.1 Billion by 2031, implying a 13.8% CAGR across the 2024–2031 window. This is materially faster than the underlying software licensing layer, confirming that value in the AEC digitization stack is migrating from tool acquisition toward implementation, coordination, and managed advisory.

BIM Consulting Service Market Size (In Billion)

25.0B
20.0B
15.0B
10.0B
5.0B
0
10.10 B
2025
11.49 B
2026
13.08 B
2027
14.89 B
2028
16.94 B
2029
19.28 B
2030
21.94 B
2031
Main Logo

Three structural forces define the current cycle:

  • Mandate-driven demand: Public-sector BIM requirements, increasingly anchored to ISO 19650 information-management conventions, have converted BIM consulting from discretionary spend into a procurement pre-condition across Europe, the GCC, Singapore, and a growing list of US state and federal agencies.
  • Lifecycle elongation: Consulting engagements no longer terminate at handover. Digital-twin-enabled asset management is pulling advisory scope into the operational phase, which carries roughly 80% of total building cost-of-ownership.
  • Cloud economics: SaaS delivery has collapsed the upfront capital barrier, opening a mid-market and small-firm client pool that was previously priced out of full BIM implementation programs.

Market Snapshot

Metric Value
Market size (2023) USD 7.8 Billion
Market size (2031) USD 15.1 Billion
CAGR (2024–2031) 13.8%
Largest region North America (~36% of revenue)
Fastest-growing region Asia-Pacific
Dominant service line BIM implementation & coordination
Adoption maturity ~60–70% of AEC firms have some BIM capability; consulting depth remains scarce

Market Drivers: Why Consulting Outpaces Software

The consulting layer is growing faster than the software layer it supports because implementation complexity, not tool availability, is now the binding constraint. Our Impact Analysis quantifies five drivers:

Driver Estimated CAGR Impact Geographic Relevance Timeline
E-mandates and ISO 19650 alignment +2.0% Europe, North America, developed APAC Medium term
Digital-twin-enabled lifecycle management +1.5% North America, Western Europe, Singapore, Japan, South Korea Medium term
Green-building and net-zero compliance +1.2% Europe, North America, Australia, Japan Long term
Modular and off-site construction coordination +1.0% Scandinavia, UK, Singapore, Japan Medium term
Cloud/SaaS and AI-enabled generative design +0.9% Global Short to medium term

Regulatory mandates are the single highest-leverage variable. The UK requirement for progressively higher BIM maturity on publicly funded projects above GBP 5 million has normalized structured data exchange as a delivery standard rather than a differentiator. More than 60% of European public agencies now publish formal BIM strategies, creating a cascading effect through private development. Equivalent policies in Canadian provinces and multiple US states replicate the mechanism. For consultants, this is a demand multiplier: mandates create compliance obligations, and compliance obligations require specialized advisory capacity that most design and construction firms have not built internally.

Digital twins are the margin story. Clients connecting federated models to IoT sensor networks report roughly 5% annual operating cost reduction and up to 35% faster maintenance response. The consulting opportunity is in the retrofit and commissioning layer: legacy as-built documentation must be remastered into data-rich, queryable asset information models. This is labor-intensive, standards-dependent, and poorly suited to in-house delivery.

Sustainability compliance is converting BIM consulting into a reporting function. Embodied-carbon regulation across the EU and several US municipalities requires material and energy performance simulation from concept stage. Our survey data indicates roughly two-thirds of AEC executives intend to increase spend on digital tools supporting sustainability disclosure — and a substantial share of that spend lands on advisory rather than licenses.

Market Restraints: The Capability Bottleneck

Restraint Estimated CAGR Impact Severity
High licensing and training costs for SME contractors -1.5% Severe in developing economies
Interoperability and open-standards gaps -1.0% Chronic in multi-vendor environments
Cybersecurity and IP protection in cloud workflows -0.8% Acute in data-sovereignty jurisdictions
Cultural resistance to process re-engineering -0.6% Strongest in traditional construction markets

Skilled-professional scarcity is the most underappreciated constraint. Demand for BIM coordinators, information managers, and digital-delivery leads consistently outruns supply. This paradoxically benefits consultancies — scarcity is precisely what clients pay to rent — but caps aggregate delivery capacity and compresses margins on large multi-site programs where talent must be deployed at scale.

Interoperability friction persists despite IFC standardization. Multi-vendor environments still generate model-exchange loss, and consultants absorb the remediation cost. Firms that have productized model-health auditing and clash-resolution workflows are converting this friction from a margin drag into a defensible revenue line.

Value Chain Analysis: Where Consulting Value Accrues

Stage Consulting Activity Value Density
Pre-construction BIM execution planning, LOD definition, clash-detection strategy, 4D scheduling High
Design coordination Federated model management, MEP and structural coordination, constructability review High
Construction Shop drawing production, as-built verification, laser scanning and scan-to-BIM Medium-high
Handover Asset information model compilation, COBie/data-drop delivery Medium
Operations Digital twin enablement, facility-management integration, lifecycle analytics Emerging, highest growth

The pre-construction stage accounted for roughly 45% of BIM-related spend in recent cycles, and it remains the entry point for most consulting engagements. However, the fastest-compounding scope is post-construction, expanding at approximately 16–17% annually, driven by owner-side demand for operational intelligence.

Services are the growth engine of the broader ecosystem: while software retains the majority of total BIM revenue, the services segment is tracking toward a mid-teens CAGR, outpacing software growth by several hundred basis points. Within services, cloud-enabled delivery models are posting the steepest gains, with cloud deployments advancing at roughly 18% annually versus low-single-digit growth in on-premises architectures.

Segmentation Analysis

By Service Type

  • BIM implementation and deployment consulting — the largest single revenue pool, covering standards design, template development, and workflow re-engineering.
  • BIM coordination and clash detection — recurring, project-linked revenue with high volume and moderate margin.
  • Scan-to-BIM and reality capture — fast-growing, hardware-adjacent, and increasingly bundled with as-built verification.
  • 4D scheduling and 5D cost estimation — high-value advisory tied directly to measurable schedule and cost outcomes.
  • BIM training and capability uplift — a durable annuity as mandates reset skills requirements.
  • Digital twin and asset information management — the highest-growth, highest-margin emerging line.

By End-Use Industry

Commercial buildings represent the largest application pool at roughly 41% of BIM-attributable revenue, followed by residential and infrastructure. Infrastructure is the fastest-expanding vertical at approximately 16–17% CAGR, propelled by transportation megaprojects and utility programs where coordination complexity and public funding transparency requirements are highest.

By Organization Size

Large enterprises (1,000+ employees) dominate absolute spend, but the mid-market (100–999 employees) is the fastest-growing buyer cohort as SaaS economics and standardized consulting packages lower entry barriers. Small firms remain the most price-sensitive segment and are best served through productized, fixed-scope offerings.

By End-User Function

Architects historically represent the largest single user cohort at roughly 30% of spend, while contractors are growing fastest at approximately 16% annually as constructability and prefabrication workflows become model-dependent.

Regional Outlook and Investment Attractiveness

Region Share of Global Revenue Growth Profile Attractiveness
North America ~36% Mature, steady double-digit High — deep budgets, no federal mandate but strong agency-level adoption
Europe ~27% Mandate-driven, standards-led Very high — ISO 19650 normalization, net-zero regulation
Asia-Pacific ~24% Fastest-growing (~14–15% CAGR) Very high — urbanization, megaprojects, government digitization
Middle East & Africa ~7% Project-concentrated High — GCC giga-projects with explicit BIM requirements
South America ~6% Early-stage Moderate — infrastructure pipeline, capability gaps

North America retains leadership through scale of private capital investment, a mature consulting vendor base, and aggressive digital-twin adoption among institutional owners. Europe offers the most predictable demand visibility because mandates are codified rather than voluntary. Asia-Pacific is the strategic priority for capacity expansion: consulting firms that establish local delivery centers in India, Southeast Asia, and China can serve both domestic growth and global delivery arbitrage.

BIM Consulting Service Regional Market Share

Loading chart...
Main Logo

The GCC deserves specific attention. National-level BIM mandates tied to giga-project portfolios have created concentrated, high-value demand that outpaces local consulting supply, making it the most attractive market for cross-border advisory entry.

Competitive Landscape and Strategic White-Space

Competitor Archetype Strategic Position Primary Vulnerability
Integrated AEC firms with BIM divisions Bundled design-plus-consulting Perceived conflict of interest on independent review
Pure-play BIM consultancies Depth, speed, standards expertise Scale limits on multi-region programs
Software vendors' professional services arms Ecosystem lock-in Vendor bias constrains neutrality
Offshore/nearshore production specialists Cost leadership on model production Limited strategic advisory capability
Engineering and PM consultancies Program-management adjacency Shallower technical modeling depth

Market concentration is medium, with meaningful fragmentation below the top tier. Two white-space opportunities stand out. First, owner-side advisory — independent information-management consultancy acting for the asset owner rather than the delivery team — remains underserved and commands premium pricing. Second, digital twin migration services for existing building stock represent a large, structurally under-served pool where competition is still thin.

Pricing strategy is shifting from hourly to outcome-linked models. Firms quoting against measurable schedule compression or clash-reduction rates are winning larger engagements and defensible renewals.

Strategic Recommendations

  • Productize delivery. Convert repeatable workflows — model health audits, LOD compliance checks, scan-to-BIM pipelines — into fixed-scope packages to penetrate the mid-market.
  • Build the operations practice now. Post-construction and digital-twin scope is compounding at roughly 16–17% annually and carries superior margin durability.
  • Localize for mandate regimes. Certification against ISO 19650 and regional standards is a procurement gate, not a marketing asset.
  • Invest in talent pipelines. Academic partnerships and structured internal academies are more capital-efficient than lateral hiring in a scarcity market.
  • Target GCC and APAC delivery capacity. Cross-border delivery hubs address both local demand growth and global cost competitiveness.

BIM Consulting Service Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

BIM Consulting Service REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2023
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 13.8% from 2020-2034
Segmentation
  • By Service Type

    • BIM Implementation & Deployment
    • BIM Coordination & Clash Detection
    • Scan-to-BIM & Reality Capture
    • 4D Scheduling & 5D Cost Estimation
    • BIM Training & Capability Uplift

Table of Contents

  1. 1. BIM Consulting Service Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. BIM Consulting Service Executive Summary
    • 2.1. Market Snapshot
  3. 3. BIM Consulting Service Dynamics
    • 3.1. Market Drivers
      • 3.1.1. Government e-mandates and ISO 19650 alignment accelerating global BIM uptake
      • 3.1.2. Rise of digital-twin-enabled asset lifecycle management
      • 3.1.3. Green-building and net-zero compliance pressures driving performance modeling
      • 3.1.4. Modular and off-site construction demanding seamless prefab coordination
      • 3.1.5. Cloud adoption and SaaS pricing lowering entry barriers
      • 3.1.6. Increasing complexity of modern multi-disciplinary construction projects
    • 3.2. Market Trends
      • 3.2.1. Digital-twin-enabled asset lifecycle management extending consulting scope into operations
      • 3.2.2. Cloud-based SaaS delivery lowering entry barriers for mid-market and small AEC firms
      • 3.2.3. AI-driven generative design and predictive analytics embedding into consulting workflows
      • 3.2.4. 4D scheduling, 5D cost estimation and 6D sustainability analytics becoming default advisory scope
    • 3.3. Market Restraints
      • 3.3.1. High licensing and training costs for SME contractors
      • 3.3.2. Interoperability and open-standards gaps across multi-vendor authoring environments
  • Digital Twin & Asset Information Management
  • By End-Use Industry

    • Commercial Buildings
    • Residential Buildings
    • Infrastructure
    • Industrial
  • By Size of Organization

    • Large Enterprises
    • Mid-Market
    • Small Firms
  • By End User

    • Architects & Designers
    • Engineers
    • Contractors
    • Facility Operators
  • By Deployment Mode

    • On-Premises
    • Cloud
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • UK
      • Germany
      • France
      • Nordics
    • Asia Pacific

      • China
      • Japan
      • India
      • Singapore
      • South Korea
      • Australia
    • Middle East & Africa

      • Saudi Arabia
      • UAE
      • South Africa
    • South America

      • Brazil
      • Argentina
  • 3.3.3. Cybersecurity and IP protection concerns in cloud workflows
  • 3.3.4. Cultural resistance to process re-engineering in legacy firms
  • 3.3.5. Shortage of skilled BIM professionals limiting delivery capacity
  • 3.4. Market Challenges
    • 3.4.1. Scaling qualified consultant headcount amid persistent talent scarcity
    • 3.4.2. Maintaining neutrality and independence on owner-side engagements
    • 3.4.3. Pricing pressure from offshore model-production specialists on commodity workflows
    • 3.4.4. Navigating divergent regional BIM standards and compliance regimes
  • 4. BIM Consulting Service Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. BIM Consulting Service Analysis, Insights and Forecast, 2020-2034
    • 5.1. Analysis, Insights and Forecast - by Service Type
      • 5.1.1. BIM Implementation & Deployment
      • 5.1.2. BIM Coordination & Clash Detection
      • 5.1.3. Scan-to-BIM & Reality Capture
      • 5.1.4. 4D Scheduling & 5D Cost Estimation
      • 5.1.5. BIM Training & Capability Uplift
      • 5.1.6. Digital Twin & Asset Information Management
    • 5.2. Analysis, Insights and Forecast - by End-Use Industry
      • 5.2.1. Commercial Buildings
      • 5.2.2. Residential Buildings
      • 5.2.3. Infrastructure
      • 5.2.4. Industrial
    • 5.3. Analysis, Insights and Forecast - by Size of Organization
      • 5.3.1. Large Enterprises
      • 5.3.2. Mid-Market
      • 5.3.3. Small Firms
    • 5.4. Analysis, Insights and Forecast - by End User
      • 5.4.1. Architects & Designers
      • 5.4.2. Engineers
      • 5.4.3. Contractors
      • 5.4.4. Facility Operators
    • 5.5. Analysis, Insights and Forecast - by Deployment Mode
      • 5.5.1. On-Premises
      • 5.5.2. Cloud
    • 5.6. Analysis, Insights and Forecast - by Region
      • 5.6.1. North America
      • 5.6.2. Europe
      • 5.6.3. Asia Pacific
      • 5.6.4. Middle East & Africa
      • 5.6.5. South America
  • 6. BIM Consulting Service North America Analysis, Insights and Forecast, 2020-2034
    • 6.1. Analysis, Insights and Forecast - by Service Type
      • 6.1.1. BIM Implementation & Deployment
      • 6.1.2. BIM Coordination & Clash Detection
      • 6.1.3. Scan-to-BIM & Reality Capture
      • 6.1.4. 4D Scheduling & 5D Cost Estimation
      • 6.1.5. BIM Training & Capability Uplift
      • 6.1.6. Digital Twin & Asset Information Management
    • 6.2. Analysis, Insights and Forecast - by End-Use Industry
      • 6.2.1. Commercial Buildings
      • 6.2.2. Residential Buildings
      • 6.2.3. Infrastructure
      • 6.2.4. Industrial
    • 6.3. Analysis, Insights and Forecast - by Size of Organization
      • 6.3.1. Large Enterprises
      • 6.3.2. Mid-Market
      • 6.3.3. Small Firms
    • 6.4. Analysis, Insights and Forecast - by End User
      • 6.4.1. Architects & Designers
      • 6.4.2. Engineers
      • 6.4.3. Contractors
      • 6.4.4. Facility Operators
    • 6.5. Analysis, Insights and Forecast - by Deployment Mode
      • 6.5.1. On-Premises
      • 6.5.2. Cloud
  • 7. BIM Consulting Service Europe Analysis, Insights and Forecast, 2020-2034
    • 7.1. Analysis, Insights and Forecast - by Service Type
      • 7.1.1. BIM Implementation & Deployment
      • 7.1.2. BIM Coordination & Clash Detection
      • 7.1.3. Scan-to-BIM & Reality Capture
      • 7.1.4. 4D Scheduling & 5D Cost Estimation
      • 7.1.5. BIM Training & Capability Uplift
      • 7.1.6. Digital Twin & Asset Information Management
    • 7.2. Analysis, Insights and Forecast - by End-Use Industry
      • 7.2.1. Commercial Buildings
      • 7.2.2. Residential Buildings
      • 7.2.3. Infrastructure
      • 7.2.4. Industrial
    • 7.3. Analysis, Insights and Forecast - by Size of Organization
      • 7.3.1. Large Enterprises
      • 7.3.2. Mid-Market
      • 7.3.3. Small Firms
    • 7.4. Analysis, Insights and Forecast - by End User
      • 7.4.1. Architects & Designers
      • 7.4.2. Engineers
      • 7.4.3. Contractors
      • 7.4.4. Facility Operators
    • 7.5. Analysis, Insights and Forecast - by Deployment Mode
      • 7.5.1. On-Premises
      • 7.5.2. Cloud
  • 8. BIM Consulting Service Asia Pacific Analysis, Insights and Forecast, 2020-2034
    • 8.1. Analysis, Insights and Forecast - by Service Type
      • 8.1.1. BIM Implementation & Deployment
      • 8.1.2. BIM Coordination & Clash Detection
      • 8.1.3. Scan-to-BIM & Reality Capture
      • 8.1.4. 4D Scheduling & 5D Cost Estimation
      • 8.1.5. BIM Training & Capability Uplift
      • 8.1.6. Digital Twin & Asset Information Management
    • 8.2. Analysis, Insights and Forecast - by End-Use Industry
      • 8.2.1. Commercial Buildings
      • 8.2.2. Residential Buildings
      • 8.2.3. Infrastructure
      • 8.2.4. Industrial
    • 8.3. Analysis, Insights and Forecast - by Size of Organization
      • 8.3.1. Large Enterprises
      • 8.3.2. Mid-Market
      • 8.3.3. Small Firms
    • 8.4. Analysis, Insights and Forecast - by End User
      • 8.4.1. Architects & Designers
      • 8.4.2. Engineers
      • 8.4.3. Contractors
      • 8.4.4. Facility Operators
    • 8.5. Analysis, Insights and Forecast - by Deployment Mode
      • 8.5.1. On-Premises
      • 8.5.2. Cloud
  • 9. BIM Consulting Service Middle East & Africa Analysis, Insights and Forecast, 2020-2034
    • 9.1. Analysis, Insights and Forecast - by Service Type
      • 9.1.1. BIM Implementation & Deployment
      • 9.1.2. BIM Coordination & Clash Detection
      • 9.1.3. Scan-to-BIM & Reality Capture
      • 9.1.4. 4D Scheduling & 5D Cost Estimation
      • 9.1.5. BIM Training & Capability Uplift
      • 9.1.6. Digital Twin & Asset Information Management
    • 9.2. Analysis, Insights and Forecast - by End-Use Industry
      • 9.2.1. Commercial Buildings
      • 9.2.2. Residential Buildings
      • 9.2.3. Infrastructure
      • 9.2.4. Industrial
    • 9.3. Analysis, Insights and Forecast - by Size of Organization
      • 9.3.1. Large Enterprises
      • 9.3.2. Mid-Market
      • 9.3.3. Small Firms
    • 9.4. Analysis, Insights and Forecast - by End User
      • 9.4.1. Architects & Designers
      • 9.4.2. Engineers
      • 9.4.3. Contractors
      • 9.4.4. Facility Operators
    • 9.5. Analysis, Insights and Forecast - by Deployment Mode
      • 9.5.1. On-Premises
      • 9.5.2. Cloud
  • 10. BIM Consulting Service South America Analysis, Insights and Forecast, 2020-2034
    • 10.1. Analysis, Insights and Forecast - by Service Type
      • 10.1.1. BIM Implementation & Deployment
      • 10.1.2. BIM Coordination & Clash Detection
      • 10.1.3. Scan-to-BIM & Reality Capture
      • 10.1.4. 4D Scheduling & 5D Cost Estimation
      • 10.1.5. BIM Training & Capability Uplift
      • 10.1.6. Digital Twin & Asset Information Management
    • 10.2. Analysis, Insights and Forecast - by End-Use Industry
      • 10.2.1. Commercial Buildings
      • 10.2.2. Residential Buildings
      • 10.2.3. Infrastructure
      • 10.2.4. Industrial
    • 10.3. Analysis, Insights and Forecast - by Size of Organization
      • 10.3.1. Large Enterprises
      • 10.3.2. Mid-Market
      • 10.3.3. Small Firms
    • 10.4. Analysis, Insights and Forecast - by End User
      • 10.4.1. Architects & Designers
      • 10.4.2. Engineers
      • 10.4.3. Contractors
      • 10.4.4. Facility Operators
    • 10.5. Analysis, Insights and Forecast - by Deployment Mode
      • 10.5.1. On-Premises
      • 10.5.2. Cloud
  • 11. BIM Consulting Service Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. Autodesk
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. Bentley Systems
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Trimble
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Nemetschek Group
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Dassault Systèmes
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. Tekla (Trimble)
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Bluebeam
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. AECOM
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. Arcadis
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. WSP
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Jacobs
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. AECOM Digital Consulting
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. Tejjy Inc.
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. RDHA
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. Vinci Technology
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. HOK
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
      • 11.1.17. Gensler
        • 11.1.17.1. Company Overview
        • 11.1.17.2. Products
        • 11.1.17.3. Company Financials
        • 11.1.17.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global BIM Consulting Service Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: North America BIM Consulting Service Revenue (Billion), by Service Type 2026 & 2034
    3. Figure 3: North America BIM Consulting Service Revenue Share (%), by Service Type 2026 & 2034
    4. Figure 4: North America BIM Consulting Service Revenue (Billion), by End-Use Industry 2026 & 2034
    5. Figure 5: North America BIM Consulting Service Revenue Share (%), by End-Use Industry 2026 & 2034
    6. Figure 6: North America BIM Consulting Service Revenue (Billion), by Size of Organization 2026 & 2034
    7. Figure 7: North America BIM Consulting Service Revenue Share (%), by Size of Organization 2026 & 2034
    8. Figure 8: North America BIM Consulting Service Revenue (Billion), by End User 2026 & 2034
    9. Figure 9: North America BIM Consulting Service Revenue Share (%), by End User 2026 & 2034
    10. Figure 10: North America BIM Consulting Service Revenue (Billion), by Deployment Mode 2026 & 2034
    11. Figure 11: North America BIM Consulting Service Revenue Share (%), by Deployment Mode 2026 & 2034
    12. Figure 12: North America BIM Consulting Service Revenue (Billion), by Country 2026 & 2034
    13. Figure 13: North America BIM Consulting Service Revenue Share (%), by Country 2026 & 2034
    14. Figure 14: Europe BIM Consulting Service Revenue (Billion), by Service Type 2026 & 2034
    15. Figure 15: Europe BIM Consulting Service Revenue Share (%), by Service Type 2026 & 2034
    16. Figure 16: Europe BIM Consulting Service Revenue (Billion), by End-Use Industry 2026 & 2034
    17. Figure 17: Europe BIM Consulting Service Revenue Share (%), by End-Use Industry 2026 & 2034
    18. Figure 18: Europe BIM Consulting Service Revenue (Billion), by Size of Organization 2026 & 2034
    19. Figure 19: Europe BIM Consulting Service Revenue Share (%), by Size of Organization 2026 & 2034
    20. Figure 20: Europe BIM Consulting Service Revenue (Billion), by End User 2026 & 2034
    21. Figure 21: Europe BIM Consulting Service Revenue Share (%), by End User 2026 & 2034
    22. Figure 22: Europe BIM Consulting Service Revenue (Billion), by Deployment Mode 2026 & 2034
    23. Figure 23: Europe BIM Consulting Service Revenue Share (%), by Deployment Mode 2026 & 2034
    24. Figure 24: Europe BIM Consulting Service Revenue (Billion), by Country 2026 & 2034
    25. Figure 25: Europe BIM Consulting Service Revenue Share (%), by Country 2026 & 2034
    26. Figure 26: Asia Pacific BIM Consulting Service Revenue (Billion), by Service Type 2026 & 2034
    27. Figure 27: Asia Pacific BIM Consulting Service Revenue Share (%), by Service Type 2026 & 2034
    28. Figure 28: Asia Pacific BIM Consulting Service Revenue (Billion), by End-Use Industry 2026 & 2034
    29. Figure 29: Asia Pacific BIM Consulting Service Revenue Share (%), by End-Use Industry 2026 & 2034
    30. Figure 30: Asia Pacific BIM Consulting Service Revenue (Billion), by Size of Organization 2026 & 2034
    31. Figure 31: Asia Pacific BIM Consulting Service Revenue Share (%), by Size of Organization 2026 & 2034
    32. Figure 32: Asia Pacific BIM Consulting Service Revenue (Billion), by End User 2026 & 2034
    33. Figure 33: Asia Pacific BIM Consulting Service Revenue Share (%), by End User 2026 & 2034
    34. Figure 34: Asia Pacific BIM Consulting Service Revenue (Billion), by Deployment Mode 2026 & 2034
    35. Figure 35: Asia Pacific BIM Consulting Service Revenue Share (%), by Deployment Mode 2026 & 2034
    36. Figure 36: Asia Pacific BIM Consulting Service Revenue (Billion), by Country 2026 & 2034
    37. Figure 37: Asia Pacific BIM Consulting Service Revenue Share (%), by Country 2026 & 2034
    38. Figure 38: Middle East & Africa BIM Consulting Service Revenue (Billion), by Service Type 2026 & 2034
    39. Figure 39: Middle East & Africa BIM Consulting Service Revenue Share (%), by Service Type 2026 & 2034
    40. Figure 40: Middle East & Africa BIM Consulting Service Revenue (Billion), by End-Use Industry 2026 & 2034
    41. Figure 41: Middle East & Africa BIM Consulting Service Revenue Share (%), by End-Use Industry 2026 & 2034
    42. Figure 42: Middle East & Africa BIM Consulting Service Revenue (Billion), by Size of Organization 2026 & 2034
    43. Figure 43: Middle East & Africa BIM Consulting Service Revenue Share (%), by Size of Organization 2026 & 2034
    44. Figure 44: Middle East & Africa BIM Consulting Service Revenue (Billion), by End User 2026 & 2034
    45. Figure 45: Middle East & Africa BIM Consulting Service Revenue Share (%), by End User 2026 & 2034
    46. Figure 46: Middle East & Africa BIM Consulting Service Revenue (Billion), by Deployment Mode 2026 & 2034
    47. Figure 47: Middle East & Africa BIM Consulting Service Revenue Share (%), by Deployment Mode 2026 & 2034
    48. Figure 48: Middle East & Africa BIM Consulting Service Revenue (Billion), by Country 2026 & 2034
    49. Figure 49: Middle East & Africa BIM Consulting Service Revenue Share (%), by Country 2026 & 2034
    50. Figure 50: South America BIM Consulting Service Revenue (Billion), by Service Type 2026 & 2034
    51. Figure 51: South America BIM Consulting Service Revenue Share (%), by Service Type 2026 & 2034
    52. Figure 52: South America BIM Consulting Service Revenue (Billion), by End-Use Industry 2026 & 2034
    53. Figure 53: South America BIM Consulting Service Revenue Share (%), by End-Use Industry 2026 & 2034
    54. Figure 54: South America BIM Consulting Service Revenue (Billion), by Size of Organization 2026 & 2034
    55. Figure 55: South America BIM Consulting Service Revenue Share (%), by Size of Organization 2026 & 2034
    56. Figure 56: South America BIM Consulting Service Revenue (Billion), by End User 2026 & 2034
    57. Figure 57: South America BIM Consulting Service Revenue Share (%), by End User 2026 & 2034
    58. Figure 58: South America BIM Consulting Service Revenue (Billion), by Deployment Mode 2026 & 2034
    59. Figure 59: South America BIM Consulting Service Revenue Share (%), by Deployment Mode 2026 & 2034
    60. Figure 60: South America BIM Consulting Service Revenue (Billion), by Country 2026 & 2034
    61. Figure 61: South America BIM Consulting Service Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global BIM Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
    2. Table 2: Global BIM Consulting Service Revenue Billion Forecast, by End-Use Industry 2020 & 2034
    3. Table 3: Global BIM Consulting Service Revenue Billion Forecast, by Size of Organization 2020 & 2034
    4. Table 4: Global BIM Consulting Service Revenue Billion Forecast, by End User 2020 & 2034
    5. Table 5: Global BIM Consulting Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
    6. Table 6: Global BIM Consulting Service Revenue Billion Forecast, by Region 2020 & 2034
    7. Table 7: North America BIM Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
    8. Table 8: North America BIM Consulting Service Revenue Billion Forecast, by End-Use Industry 2020 & 2034
    9. Table 9: North America BIM Consulting Service Revenue Billion Forecast, by Size of Organization 2020 & 2034
    10. Table 10: North America BIM Consulting Service Revenue Billion Forecast, by End User 2020 & 2034
    11. Table 11: North America BIM Consulting Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
    12. Table 12: North America BIM Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
    13. Table 13: USA BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: Canada BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    15. Table 15: Mexico BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    16. Table 16: Europe BIM Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
    17. Table 17: Europe BIM Consulting Service Revenue Billion Forecast, by End-Use Industry 2020 & 2034
    18. Table 18: Europe BIM Consulting Service Revenue Billion Forecast, by Size of Organization 2020 & 2034
    19. Table 19: Europe BIM Consulting Service Revenue Billion Forecast, by End User 2020 & 2034
    20. Table 20: Europe BIM Consulting Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
    21. Table 21: Europe BIM Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
    22. Table 22: UK BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    23. Table 23: Germany BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: France BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    25. Table 25: Nordics BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    26. Table 26: Asia Pacific BIM Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
    27. Table 27: Asia Pacific BIM Consulting Service Revenue Billion Forecast, by End-Use Industry 2020 & 2034
    28. Table 28: Asia Pacific BIM Consulting Service Revenue Billion Forecast, by Size of Organization 2020 & 2034
    29. Table 29: Asia Pacific BIM Consulting Service Revenue Billion Forecast, by End User 2020 & 2034
    30. Table 30: Asia Pacific BIM Consulting Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
    31. Table 31: Asia Pacific BIM Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
    32. Table 32: China BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    33. Table 33: Japan BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    34. Table 34: India BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    35. Table 35: Singapore BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    36. Table 36: South Korea BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    37. Table 37: Australia BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    38. Table 38: Middle East & Africa BIM Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
    39. Table 39: Middle East & Africa BIM Consulting Service Revenue Billion Forecast, by End-Use Industry 2020 & 2034
    40. Table 40: Middle East & Africa BIM Consulting Service Revenue Billion Forecast, by Size of Organization 2020 & 2034
    41. Table 41: Middle East & Africa BIM Consulting Service Revenue Billion Forecast, by End User 2020 & 2034
    42. Table 42: Middle East & Africa BIM Consulting Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
    43. Table 43: Middle East & Africa BIM Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
    44. Table 44: Saudi Arabia BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    45. Table 45: UAE BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    46. Table 46: South Africa BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    47. Table 47: South America BIM Consulting Service Revenue Billion Forecast, by Service Type 2020 & 2034
    48. Table 48: South America BIM Consulting Service Revenue Billion Forecast, by End-Use Industry 2020 & 2034
    49. Table 49: South America BIM Consulting Service Revenue Billion Forecast, by Size of Organization 2020 & 2034
    50. Table 50: South America BIM Consulting Service Revenue Billion Forecast, by End User 2020 & 2034
    51. Table 51: South America BIM Consulting Service Revenue Billion Forecast, by Deployment Mode 2020 & 2034
    52. Table 52: South America BIM Consulting Service Revenue Billion Forecast, by Country 2020 & 2034
    53. Table 53: Brazil BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034
    54. Table 54: Argentina BIM Consulting Service Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the size of the BIM consulting service market?

    The global BIM consulting service market was valued at USD 7.8 Billion in 2023 and is projected to reach USD 15.1 Billion by 2031, expanding at a 13.8% CAGR over the 2024–2031 forecast period.

    2Why is BIM consulting growing faster than BIM software?

    Tool availability is no longer the constraint — implementation complexity is. Mandates tied to ISO 19650, digital twin migration, and net-zero compliance reporting all require specialized advisory capacity that most AEC firms have not built internally, pushing roughly two-thirds of surveyed executives to increase digital advisory spend.

    3Which region leads the BIM consulting service market?

    North America holds approximately 36% of global revenue, supported by private capital investment and institutional digital twin adoption. Asia-Pacific is the fastest-growing region, expanding at around 14–15% annually on the back of urbanization and megaproject pipelines.

    4What service segments drive the most revenue?

    BIM implementation and deployment consulting is the largest revenue pool, followed by coordination and clash detection. Digital twin and asset information management is the fastest-growing service line, compounding at roughly 16–17% annually as owners extend advisory scope into operations.

    5What are the biggest challenges facing BIM consultancies?

    Skilled-professional scarcity is the primary capacity constraint, alongside interoperability gaps in multi-vendor environments and cybersecurity concerns in cloud workflows. High licensing and training costs disproportionately affect small and mid-sized contractor clients, limiting addressable demand in developing economies.

    6Which end-use industry is growing fastest for BIM consulting?

    Infrastructure is the fastest-expanding vertical at approximately 16–17% CAGR, driven by transportation megaprojects and utility programs. Commercial buildings remain the largest application pool at roughly 41% of BIM-attributable revenue.

    7What is the role of government mandates in BIM consulting demand?

    Mandates are the highest-leverage driver in the market, contributing an estimated 2.0 percentage points to CAGR. More than 60% of European public agencies now publish formal BIM strategies, and comparable policies in the UK, GCC, Singapore, and US state agencies create compliance obligations that require external advisory expertise.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Primary research accounts for 70–80% of total research effort, forming the evidentiary backbone of every BIM consulting service market estimate published in this report.
    • We conducted 1,140 structured interviews across the 2023–2025 fielding window, spanning North America, Europe, Asia-Pacific, the Middle East, and South America.
    • Respondent company types include pure-play BIM consultancies, integrated AEC firms with dedicated BIM divisions, software vendors' professional services arms, offshore model-production and scan-to-BIM specialists, and owner-side program management firms.
    • Interviewed stakeholders include Chief Digital Officers, BIM Directors and Information Managers, VDC Managers, and Procurement Heads at architecture, engineering, and contracting organizations.
    • Interviews are supplemented by procurement-record audits of public tender databases in mandate-driven jurisdictions, capturing awarded consulting contract values and scope definitions.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    BIM Director / Information Manager38%
    Chief Digital Officer27%
    VDC Manager21%
    Procurement Head14%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Pure-play BIM consultancies34%
    Integrated AEC firms with BIM divisions26%
    Offshore model-production & scan-to-BIM specialists19%
    Software vendors' professional services arms13%
    Owner-side program management firms8%

    Secondary Research & Industry Benchmarking

    • Secondary research accounts for 20–30% of effort and is used strictly for triangulation and sanity-checking, never as a substitute for primary findings.
    • Financial and corporate data were sourced from Bloomberg, Factiva, Hoovers, and PitchBook to validate vendor revenue splits and segment-level performance.
    • Trade and output data were benchmarked against official sources including the United Nations Comtrade Database, World Bank, OECD, and Eurostat construction output series.
    • Technical and standards benchmarking draws on ISO 19650 information-management series, buildingSMART International's IFC specifications, and the UK BIM Framework, alongside national BIM mandate documentation from public procurement authorities.
    • No commercial third-party market research publications are used in the derivation of any figure in this report.

    Demand Modeling & Market Estimation

    • We apply top-down and bottom-up methodologies simultaneously, reconciling the two through multi-level data triangulation.
    • The bottom-up model is built from four quantitative inputs: count of active BIM consulting engagements by region, average annual contract value per engagement type, billable consultant headcount utilization rates, and modeled consulting attach rates against regional construction output.
    • Segment-level allocation is cross-validated against service-line revenue disclosures, tender award values, and verified consulting backlog reported in primary interviews.
    • Regional shares are reconciled to national AEC digitization adoption indices and public-sector BIM mandate coverage, ensuring growth rates are structurally explainable rather than extrapolated.
    • All forecasts to 2031 are scenario-weighted across base, accelerated-mandate, and delayed-adoption cases, with the reported CAGR reflecting the base case.

    Data Accuracy & Quality Check

    • Every report carries a guaranteed estimated data accuracy level of 85–90%, validated through independent re-interview of a 12% respondent sub-sample.
    • Findings pass through a three-tier review: analyst-level model validation, director-level plausibility review, and an independent industry panel that stress-tests assumptions against lived market conditions.
    • Outlier responses and anomalous contract values are flagged and re-verified before inclusion; no figure in this report is derived from a single uncorroborated source.
    • Every report is updated to the date of purchase, with refreshed primary interview data and revised official statistics incorporated into the model at the point of delivery.