1What is the market size of the self check-in airport counter market?
The global self check-in airport counter market was valued at USD 2.3 billion in 2024 and is projected to reach USD 5.8 billion by 2034, growing at a CAGR of 9.6%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Self Check-in Airport Counter Insightful Market
 by Component (Hardware, Software, Services), by Kiosk Type (Check-in Kiosks, Automated Passport Control Kiosks, Common-use Self-service Kiosks, Bag Drop Kiosks, Information Kiosks, Retail Kiosks), by Deployment Mode (On-premises, Cloud), by Application (Passenger Check-in, Baggage Tagging and Drop-off, Security and Immigration, Information Display, Retail and Ancillary Services), by End User (Airports, Airlines, Government Agencies, Retail Concessionaires), by North America (USA, Canada), by Europe (Germany, UK, France, Netherlands), by Asia Pacific (China, India, Japan, Singapore, South Korea), by Latin America (Brazil, Mexico), by Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa) Forecast 2026-2034
Research Associate


 Related Reports

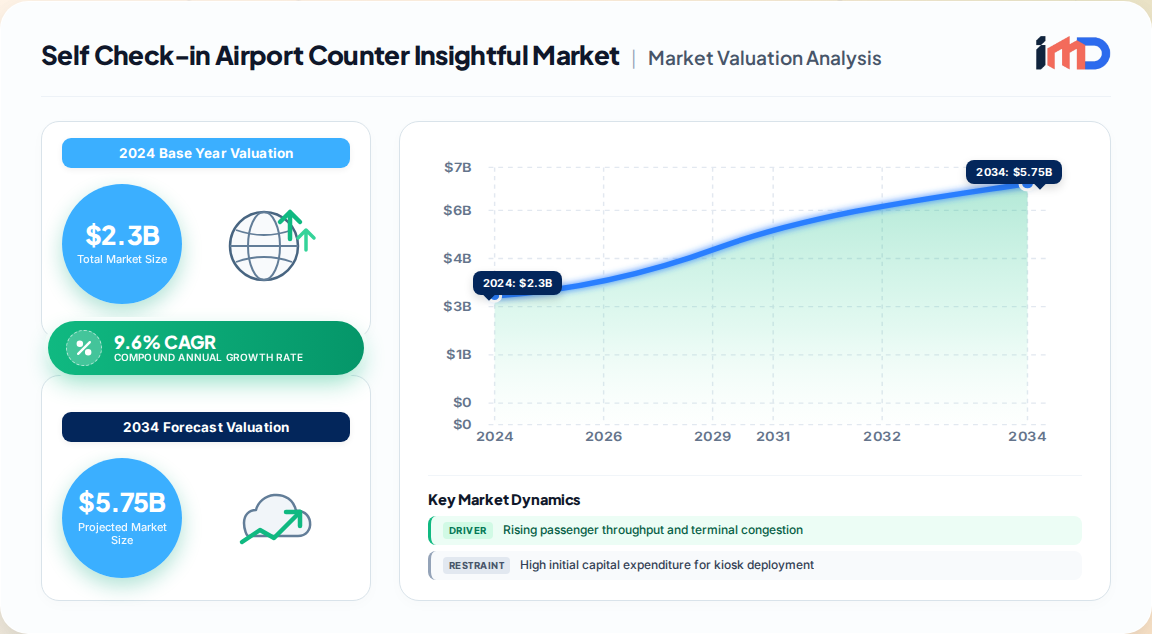
The global self check-in airport counter market is undergoing a structural transformation as airports and airlines race to accommodate surging passenger volumes without proportional increases in terminal footprint or staff. Our proprietary primary research estimates the market at USD 2.3 billion in 2024, projected to reach USD 5.8 billion by 2034, expanding at a CAGR of 9.6%. This growth is underpinned by the accelerating replacement of traditional check-in desks with self-service kiosks that integrate biometric authentication, baggage tagging, and multi-language interfaces. The self check-in counter segment alone represents the fastest-growing kiosk category, with a CAGR of 10.8%, as operators prioritize throughput and passenger autonomy.
Key market participants are shifting from hardware-centric offerings to integrated platforms that combine kiosks, software orchestration, and identity management. This evolution is redefining competitive dynamics, raising switching costs, and enabling common-use deployments across multiple airlines. The market is moderately consolidated, with technology providers and systems integrators competing on end-to-end passenger processing ecosystems rather than standalone units.
The self check-in airport counter market operates within a multifaceted supply chain spanning hardware manufacturing, software development, systems integration, and after-sales services. Hardware components—including touchscreens, biometric scanners, printers, and document readers—are sourced globally, with key manufacturing hubs in the U.S., Germany, and China. Software development focuses on user interfaces, integration APIs, and biometric algorithms, increasingly delivered via cloud-native architectures. Systems integrators and service providers handle installation, maintenance, and analytics support, often under multi-year service-level agreements.
A notable trend is the shift toward cloud-based deployment, projected to grow at an 11.36% CAGR through 2031, enabling remote customization, faster software updates, and API integration with airline reservation systems and immigration databases. This transition reduces on-site IT burden and supports scalability across multi-terminal airports.
The market is segmented by component, kiosk type, deployment mode, application, and end user.
| Segment | Sub-segment | 2024 Share / Growth |
|---|---|---|
| Component | Hardware | 60% share (2024); services growing at 13.29% CAGR |
| Kiosk Type | Check-in kiosks | Fastest-growing at 10.8% CAGR; standard kiosks held 33.54% share in 2025 |
| Deployment Mode | On-premises | 52.45% share (2025); cloud growing at 11.36% CAGR |
| Application | Passenger check-in | 39.85% share (2025); flight information growing at 12.62% CAGR |
| End User | Airports | 40.65% share (2025); airlines growing at 11.35% CAGR |
Hardware dominance reflects the capital-intensive nature of kiosk fleets, but software and services are gaining strategic importance as airports seek customizable, intelligent ecosystems. Check-in kiosks remain the largest type, while self-bag drop kiosks are the fastest-growing sub-segment, driven by demand for end-to-end self-service journeys.
North America and Asia-Pacific are the twin engines of growth, with North America holding the largest share and Asia-Pacific registering the fastest CAGR.
| Region | 2025 Share / Outlook |
|---|---|
| North America | 35.98% of global market in 2025; U.S. dominance supported by TSA biometric initiatives and airport modernization |
| Europe | Strong adoption driven by GDPR-compliant biometric kiosks and EU Aviation Strategy mandates |
| Asia-Pacific | Fastest-growing at 11.77% CAGR through 2031; China and India lead with greenfield airport projects and smart terminal investments |
| Latin America | Underpenetrated but gaining momentum, led by Brazil and Mexico |
| Middle East & Africa | Emerging hub for biometric-enabled kiosk corridors, particularly in UAE, Saudi Arabia, and Qatar |
Asia-Pacific's growth is fueled by massive infrastructure programs: China plans to build over 220 new airports by 2035, while India's UDAN initiative and Changi Terminal 5 project exemplify the region's leapfrogging potential. North America remains the volume benchmark, with over 85% of major U.S. airports having adopted self-service kiosks for check-in, immigration, and baggage drop.
The market is moderately consolidated, with leading players focusing on integrated hardware-software platforms, biometric capabilities, and cloud-based management. Competition is shifting from unit pricing to end-to-end passenger processing outcomes, including queue time reduction and ancillary revenue enablement.
Recent strategic developments include:
These developments underscore the industry's direction toward biometric, cloud-native, and common-use solutions that scale across airport networks and airline alliances.
Investment attractiveness varies by region, shaped by infrastructure maturity, regulatory frameworks, and passenger growth trajectories.
| Region | Attractiveness | Key Factors |
|---|---|---|
| North America | High (mature) | Replacement demand for biometric kiosks; TSA and CBP mandates; strong airline IT spending |
| Asia-Pacific | Very High (growth) | Greenfield airport projects; government smart-airport mandates; leapfrogging legacy systems |
| Europe | High | GDPR-compliant biometric solutions; EU digital identity initiatives; energy-efficient kiosk demand |
| Middle East | High (emerging) | Mega-hub investments in biometric corridors; visa-on-arrival kiosks; high passenger growth |
| Latin America | Moderate | LCC expansion driving cost-saving automation; limited funding and fragmented regulation |
Asia-Pacific offers the most compelling growth opportunity, with cumulative capital expenditure on airport infrastructure projected to exceed USD 1.3 trillion through 2030. North America remains attractive for replacement cycles and software upgrades, while Europe's focus on sustainability and data privacy creates demand for eco-designed, compliant kiosks.
Several underpenetrated segments present strategic opportunities for vendors and investors:
Procurement of self check-in airport counters is increasingly strategic, with buyers evaluating total cost of ownership, interoperability, and compliance.
Sourcing decisions increasingly weigh cybersecurity certifications, data residency compliance, and vendor financial stability, particularly for large-scale common-use deployments.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.6% from 2020-2034 |
| Segmentation |
|
By Deployment Mode
By Application
By End User
| By Geography |
|
The global self check-in airport counter market was valued at USD 2.3 billion in 2024 and is projected to reach USD 5.8 billion by 2034, growing at a CAGR of 9.6%.
North America holds the largest share, accounting for approximately 36% of the global market in 2025, driven by high passenger volumes and early adoption of biometric kiosks. Asia-Pacific is the fastest-growing region with an 11.77% CAGR.
Key drivers include rising passenger throughput and terminal congestion, airlines prioritizing queue time reduction, expansion of biometric and contactless processing, and passenger expectations for self-service after digital travel adoption.
Check-in kiosks are the fastest-growing type with a CAGR of 10.8%, driven by the need for efficient passenger processing and the integration of biometric authentication and multi-language capabilities.
High initial capital expenditure, cybersecurity and data privacy compliance, and integration complexity with legacy airport systems are the primary challenges. Compliance with regulations like GDPR and TSA cybersecurity requirements adds significant cost and complexity.
Leading companies include SITA, NCR Voyix Corporation, Fujitsu Ltd., Materna IPS GmbH, Embross Group, Elenium Automation Pty Ltd, KIOSK Information Systems, Olea Kiosks Inc., IER SAS, Amadeus IT Group SA, and Collins Aerospace.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Airport Operations Director | 30% |
| Airline IT Procurement Head | 25% |
| Terminal Planning Manager | 25% |
| Chief Information Officer | 20% |
| Company Type | Representation (%) |
|---|---|
| Kiosk Hardware Manufacturers | 35% |
| Airport IT System Integrators | 25% |
| Airline Departure Control System Providers | 20% |
| Biometric Technology Vendors | 12% |
| Airport Operators | 8% |