Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
RTA Furniture Industry by Application (Home Furniture, Office Furniture, Hospitality Furniture, Other), by Material (Wood, Metal, Plastic & Polymer, Glass, Other Materials), by Price Range (Economy, Mid-Range, Premium), by Distribution Channel (B2C/Retail, B2B/Project, Online Retail, Home Centers, Specialty Stores), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Poland, Turkey), by Asia Pacific (China, India, Japan, Vietnam, Indonesia), by South America (Colombia, Brazil), by Middle East & Africa (Morocco, South Africa) Forecast 2026-2034
The Magic Carpet Ski Lifts Market is valued at 312 Million in 2025 and is projected to reach 512 Million by 2032, growing at a CAGR of 7.3%.
Nov 2026|263 pages
$2900.00
Global lawn mower blade market to reach $4.6B by 2034 at 5.67% CAGR. Explore blade type, material, end-user and regional trends shaping demand.
Nov 2026|209 pages
$2900.00
Global second hand office furniture market to grow at 5.8% CAGR through 2031, driven by circular policies, corporate decommissioning, and online resale.
Nov 2026|254 pages
$2900.00
Indonesia furniture market to reach USD 15.2 Billion by 2034 at 5.82% CAGR. Explore trends, segmentation, trade dynamics, and competitive landscape.
Executive Overview: The RTA Furniture Industry Market
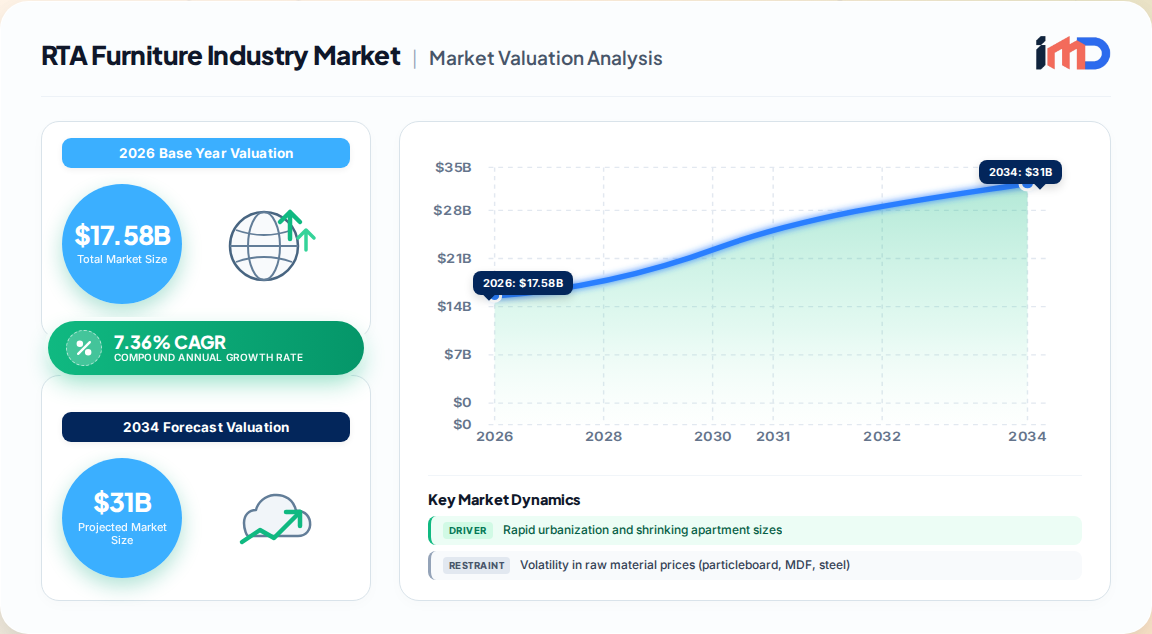
The global RTA (Ready-to-Assemble) furniture industry market is undergoing a structural transformation, evolving from a budget-driven commodity category into a design-led, omnichannel growth engine. Our proprietary primary research and expert interviews estimate the market at USD 17.58 billion in 2026, up from USD 16.48 billion in 2025, and project it to reach USD 25.24 billion by 2031, reflecting a CAGR of 7.36% over the forecast period.
RTA Furniture Industry Market Size (In Billion)
30.0B
20.0B
10.0B
0
16.38 B
2025
17.58 B
2026
18.87 B
2027
20.26 B
2028
21.75 B
2029
23.36 B
2030
25.07 B
2031
This growth is not merely a post-pandemic normalization; it is driven by fundamental shifts in urban living, sustainability regulation, and the digitization of furniture retail.
Market Concentration: The competitive landscape remains low to moderate, with no single player commanding a dominant global share. However, a clear tiering is emerging between vertically integrated giants, regional manufacturing specialists, and agile direct-to-consumer (DTC) brands.
Fastest-Growing Region:Asia-Pacific is accelerating at a 6.93% CAGR, driven by rapid urbanization and household formation.
Largest Revenue Pool:North America remains the most mature market, holding a 35% share in 2025, underpinned by a strong DIY culture and a highly developed e-commerce infrastructure.
Key Metric: Online retail is the fastest-growing distribution channel, forecast to expand at an 8.17% CAGR through 2031, fundamentally reshaping the value chain.
Key Market Drivers and Restraints
The RTA furniture industry market is propelled by a confluence of demographic, economic, and regulatory factors. Our analysis quantifies the impact of these drivers on the forecast CAGR.
Growth Drivers
DIY and Personalization Culture (+1.2% CAGR impact): Tool-free assembly systems and modular designs are lowering the barrier to entry for renters and urban dwellers. This is moving RTA furniture from a ''cheap alternative'' to a ''creative, flexible furnishing option.''
Space Constraints and Affordability (+1.5% CAGR impact): Shrinking apartment footprints in Tier-1 cities across Asia-Pacific, North America, and Europe are driving demand for multifunctional, space-saving furniture. The RTA model offers a 20-30% cost advantage over pre-assembled equivalents.
Sustainability and Eco-Friendly Materials (+0.9% CAGR impact): Consumer preference for FSC/PEFC-certified wood and recycled materials is a long-term tailwind. In the US, regulations on PFAS have forced over 75% of leading brands to overhaul supply chains for greater transparency, favoring RTA manufacturers with agile, traceable sourcing.
Residential Construction and Household Formation (+1.8% CAGR impact): Short-term demand is heavily correlated with new household formation, particularly in India, Vietnam, and Indonesia, as well as sunbelt metros in the US.
EU ESPR/Digital Product Passports (+0.6% CAGR impact): The EU''s Ecodesign for Sustainable Products Regulation (ESPR) is favoring repairable, traceable RTA products, creating a regulatory moat for compliant manufacturers exporting into the EU-27.
Key Restraints
Raw Material Price Volatility: Fluctuations in particleboard, MDF, and steel prices directly impact margins, particularly for economy-tier products.
Logistics and Packaging Costs: While flat-pack design reduces shipping volume, the need for robust packaging to withstand last-mile delivery remains a significant cost center. Amazon''s SIPP (Ships in Product Packaging) incentives are helping, but adoption is uneven.
Consumer Assembly Aversion: A persistent challenge is the perceived difficulty of assembly. Brands that fail to invest in intuitive instructions and tool-free connectors face higher return rates and negative reviews.
Value Chain and Supply Dynamics
The RTA furniture value chain is characterized by a high degree of vertical integration among leaders and a fragmented supplier base for smaller players. Our analysis identifies four critical stages: raw material supply, component manufacturing, flat-pack packaging and logistics, and omnichannel distribution.
Value Chain Stage
Key Activities
Major Cost Drivers
Geographic Concentration
Raw Material Supply
Sourcing of particleboard, MDF, steel, glass, and hardware
North America and Europe dominate; Asia-Pacific growing rapidly
Supplier Dynamics and Import/Export:
The RTA furniture industry is highly tradable, with significant flows from manufacturing hubs to consumer markets.
Export Powerhouses: China and Vietnam remain the largest exporters of RTA furniture, leveraging scale and cost advantages. However, rising labor costs and trade tensions are driving a gradual shift to nearshore locations.
Nearshoring to the Americas: Companies operating in free trade zones, such as RTA Design Zona Franca S.A.S. in Colombia, are gaining traction by offering duty-free access to the US and EU markets, combined with optimized flat-pack engineering that minimizes freight costs. This model allows for agile lead times and superior margins compared to Asian imports.
European Intra-Trade: Poland and Turkey are key suppliers to the EU market, benefiting from proximity and compliance with EU regulations.
US Domestic Manufacturing: Players like Sauder Woodworking maintain significant US-based production, catering to demand for ''Made in USA'' and faster replenishment cycles.
Segmentation Analysis: Application, Material, and Price Range
Our segmentation analysis reveals clear pockets of growth and profitability. The market is segmented by application, material, price range, and distribution channel.
By Application
Home Furniture: The dominant segment, holding 62.65% of the market in 2025. Growth is driven by demand for modular sofas, beds with storage, and home office furniture for hybrid work models.
Office and Commercial Furniture: Forecast to grow at a 7.35% CAGR, as businesses seek flexible, reconfigurable office layouts and cost-effective fit-outs for co-working spaces.
Hospitality Furniture: A niche but growing segment, particularly for student housing, rental apartments, and budget hotels, where durability and quick replacement are critical.
By Material
Wood-Based Panels (Particleboard, MDF): The largest segment, accounting for 47.62% of the market in 2025. Advances in engineered wood and laminates are improving durability and aesthetics, making wood the most versatile and cost-effective material.
Plastic and Polymer: Projected to grow at a 6.63% CAGR, driven by demand for weather-resistant, lightweight furniture for outdoor and bathroom applications.
Metal (Steel, Aluminum): Valued for strength and durability, particularly in office and commercial settings. Steel furniture is gaining share due to its resistance to moisture and pests.
Glass: A premium material used in tables and shelving, appealing to minimalist aesthetics.
By Price Range
Mid-Range: The largest segment, representing 45% of the market in 2025, projected to grow at a 6.71% CAGR. Consumers are increasingly willing to pay a premium for better design, durability, and sustainability features.
Economy: Price-sensitive consumers and first-time buyers dominate this segment, particularly in emerging markets.
Premium: A smaller but high-margin segment, driven by solid wood and designer collaborations.
Distribution Channel and Regional Outlook
The channel mix is shifting decisively toward digital, but physical retail remains crucial for tactile evaluation and big-ticket purchases.
Distribution Channel Dynamics
B2C/Retail: Held 58% of the market in 2025. This includes home centers (e.g., IKEA, Home Depot), specialty stores, and flagship stores.
Online Retail: The fastest-growing channel, forecast to expand at an 8.17% CAGR through 2031. Growth is fueled by AR visualization tools, DTC models, and improved last-mile logistics. Social commerce is also emerging, with 46% of consumers purchasing directly via social media.
B2B/Project: A significant channel for office, hospitality, and real estate developers, characterized by bulk orders and contract manufacturing.
Regional Outlook
North America (35% share in 2025): The largest and most mature market. The US is the epicenter, with a strong DIY culture and high e-commerce penetration. The home segment was valued at USD 12.46 billion in 2024. Challenges include raw material volatility and competition from assembled furniture. Opportunities lie in smart furniture and sustainable, non-toxic materials.
Europe (33.3% share in 2023): A design-forward market with stringent sustainability regulations. The EU ESPR and Digital Product Passports are shaping product development. Intra-European trade is strong, with Poland and Turkey as key suppliers.
Asia-Pacific (Fastest-growing at 6.93% CAGR): Urbanization and a burgeoning middle class are driving demand. China and India are the largest markets, with Vietnam and Indonesia emerging as manufacturing hubs. The region is expected to see higher absolute volume growth.
South America and Middle East & Africa: Smaller but promising markets, with growth driven by urbanization and real estate development. Free trade zones in Colombia and Morocco are emerging as strategic manufacturing and distribution hubs.
RTA Furniture Industry Regional Market Share
Loading chart...
Competitive Landscape and Strategic Developments
The RTA furniture industry market is characterized by a diverse set of players, from global giants to regional specialists. Our competitive analysis highlights key strategies and recent developments.
Key Players and Strategies
Company
Headquarters
Key Strategies
Inter IKEA Systems B.V.
Sweden
Vertically integrated, design-led, sustainability focus; expanding into smart furniture and circular economy.
Sauder Woodworking Co.
US
Strong US manufacturing footprint, focus on domestic sourcing and quick replenishment; broad portfolio across home and office.
Dorel Industries Inc. (Dorel Home)
Canada
Multi-brand portfolio, strong ine-commerce and mass retail channels; focus on value and design.
Steinhoff International (Pepco & Conforama)
South Africa/Europe
European retail presence, vertical integration in flat-pack lines; focus on value and accessibility.
Tvilum A/S
Denmark
Specializes in flat-pack furniture, strong in European retail and e-commerce; focus on design and affordability.
RTA Design Zona Franca S.A.S.
Colombia
Operates in a Free Trade Zone, offering duty-free exports and nearshore manufacturing for US and EU markets; focus on OEM/ODM and contract manufacturing.
Recent Developments
2026: RTA Design Zona Franca S.A.S. (Colombia) positions itself as a nearshore contract manufacturing hub for global brands, leveraging free trade zone benefits and optimized flat-pack engineering to serve US and EU markets.
2024-2026: IKEA and other majors continue to invest in tool-free assembly innovations and modular designs, with award programs validating connector systems that compress build times.
2025-2026: EU ESPR and Digital Product Passport regulations drive investment in traceable, repairable RTA products, with manufacturers in Turkey, Poland, and China adapting to maintain EU market access.
2025: Amazon''s SIPP packaging incentives improve RTA unit economics in North America and Europe, encouraging brands to adopt sustainable packaging.
Strategic White-Space and Investment Opportunities
Our analysis identifies several underpenetrated segments and strategic opportunities for investors and manufacturers.
Smart Furniture Integration: Integrating IoT-enabled features (e.g., lighting, charging ports, adjustable height) into RTA furniture can attract tech-savvy consumers and command premium pricing. The market for smart furniture is nascent but growing at double-digit rates.
Sustainable Materials and Circular Economy: Developing RTA furniture from recycled or bio-based materials, and offering take-back or repair programs, aligns with regulatory trends and consumer preferences. Brands using recycled materials achieve up to a 15% reduction in production waste.
B2B Contract Manufacturing: The hospitality and commercial sectors offer stable, high-volume demand. Nearshore manufacturers in free trade zones (e.g., Colombia, Morocco) are well-positioned to serve US and EU markets.
Omnichannel Retail in Emerging Markets: In Asia-Pacific and Latin America, investing in DTC e-commerce and experiential showrooms can capture a rapidly growing middle class. Social commerce is a particularly promising channel.
Import/Export & Supplier Dynamics
Global trade in RTA furniture is substantial, with flows shaped by cost, tariff, and logistics considerations.
Major Exporters: China, Vietnam, Poland, and Turkey are the largest exporters of RTA furniture, supplying both components and finished goods.
Nearshoring Trends: The US-China trade tensions and pandemic-era supply chain disruptions have accelerated nearshoring to Mexico, Colombia, and other Latin American countries. Colombia''s free trade zones, like the one used by RTA Design, offer duty-free access to the US and EU, making them attractive for export-oriented manufacturing.
Import Markets: North America and Europe are the largest import markets, absorbing significant volumes from Asia and Eastern Europe. E-commerce platforms and big-box retailers rely on a global supplier base to maintain cost competitiveness.
Supplier Risks: Key risks include raw material price volatility, shipping cost fluctuations, and geopolitical instability. Manufacturers are mitigating these by diversifying supplier bases, increasing automation, and adopting dual-sourcing strategies.
Market Forecast and Conclusion
The RTA furniture industry market is on a robust growth trajectory, with a projected CAGR of 7.36% from 2026 to 2031. The market is expected to reach USD 25.24 billion by 2031, driven by urbanization, sustainability regulations, and the continued digitization of retail.
North America will remain the largest revenue pool, but Asia-Pacific will be the growth engine.
Online retail will continue to outpace offline channels, forcing traditional retailers to invest in omnichannel capabilities.
Sustainability will be a key differentiator, with regulatory pressures in the EU setting a global standard.
Competitive intensity will increase, with nearshore manufacturers and DTC brands challenging incumbents. Companies that invest in design innovation, supply chain resilience, and sustainable materials will be best positioned to capture growth.
RTA Furniture Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
RTA Furniture Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 7.36% from 2020-2034
Segmentation
By Application
Home Furniture
Office Furniture
Hospitality Furniture
Other
By Material
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rapid urbanization and shrinking apartment sizes
3.1.2. DIY and personalization culture expanding RTA adoption
3.1.4. Residential construction and household formation
3.1.5. E-commerce penetration and AR visualization tools
3.2. Market Trends
3.2.1. Tool-free assembly and modular designs enhancing user experience
3.2.2. Omnichannel retail blending showrooms with digital fulfillment
3.2.3. Sustainability and circular economy driving material innovation
3.2.4. Smart furniture integration with IoT and charging features
3.2.5. Nearshoring to free trade zones for cost and tariff advantages
3.3. Market Restrains
3.3.1. Volatility in raw material prices (particleboard, MDF, steel)
3.3.2. Logistics and last-mile delivery costs impacting margins
3.3.3. Consumer aversion to complex assembly processes
3.3.4. Competition from pre-assembled and traditional furniture
Wood
Metal
Plastic & Polymer
Glass
Other Materials
By Price Range
Economy
Mid-Range
Premium
By Distribution Channel
B2C/Retail
B2B/Project
Online Retail
Home Centers
Specialty Stores
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Poland
Turkey
Asia Pacific
China
India
Japan
Vietnam
Indonesia
South America
Colombia
Brazil
Middle East & Africa
Morocco
South Africa
3.4. Market Restraints
3.4.1. Volatility in raw material prices (particleboard, MDF, steel)
3.4.2. Logistics and last-mile delivery costs impacting margins
3.4.3. Consumer aversion to complex assembly processes
3.4.4. Competition from pre-assembled and traditional furniture
3.5. Market Challenges
3.5.1. Balancing cost-efficiency with durability and design
3.5.2. Adapting to diverse regional regulations (PFAS, ESPR)
3.5.3. Managing supply chain disruptions and tariff uncertainties
3.5.4. Educating consumers on assembly and product care
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Home Furniture
5.1.2. Office Furniture
5.1.3. Hospitality Furniture
5.1.4. Other
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Wood
5.2.2. Metal
5.2.3. Plastic & Polymer
5.2.4. Glass
5.2.5. Other Materials
5.3. Market Analysis, Insights and Forecast - by Price Range
5.3.1. Economy
5.3.2. Mid-Range
5.3.3. Premium
5.4. Market Analysis, Insights and Forecast - by Distribution Channel
5.4.1. B2C/Retail
5.4.2. B2B/Project
5.4.3. Online Retail
5.4.4. Home Centers
5.4.5. Specialty Stores
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Home Furniture
6.1.2. Office Furniture
6.1.3. Hospitality Furniture
6.1.4. Other
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Wood
6.2.2. Metal
6.2.3. Plastic & Polymer
6.2.4. Glass
6.2.5. Other Materials
6.3. Market Analysis, Insights and Forecast - by Price Range
6.3.1. Economy
6.3.2. Mid-Range
6.3.3. Premium
6.4. Market Analysis, Insights and Forecast - by Distribution Channel
6.4.1. B2C/Retail
6.4.2. B2B/Project
6.4.3. Online Retail
6.4.4. Home Centers
6.4.5. Specialty Stores
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Home Furniture
7.1.2. Office Furniture
7.1.3. Hospitality Furniture
7.1.4. Other
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Wood
7.2.2. Metal
7.2.3. Plastic & Polymer
7.2.4. Glass
7.2.5. Other Materials
7.3. Market Analysis, Insights and Forecast - by Price Range
7.3.1. Economy
7.3.2. Mid-Range
7.3.3. Premium
7.4. Market Analysis, Insights and Forecast - by Distribution Channel
7.4.1. B2C/Retail
7.4.2. B2B/Project
7.4.3. Online Retail
7.4.4. Home Centers
7.4.5. Specialty Stores
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Home Furniture
8.1.2. Office Furniture
8.1.3. Hospitality Furniture
8.1.4. Other
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Wood
8.2.2. Metal
8.2.3. Plastic & Polymer
8.2.4. Glass
8.2.5. Other Materials
8.3. Market Analysis, Insights and Forecast - by Price Range
8.3.1. Economy
8.3.2. Mid-Range
8.3.3. Premium
8.4. Market Analysis, Insights and Forecast - by Distribution Channel
8.4.1. B2C/Retail
8.4.2. B2B/Project
8.4.3. Online Retail
8.4.4. Home Centers
8.4.5. Specialty Stores
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Home Furniture
9.1.2. Office Furniture
9.1.3. Hospitality Furniture
9.1.4. Other
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Wood
9.2.2. Metal
9.2.3. Plastic & Polymer
9.2.4. Glass
9.2.5. Other Materials
9.3. Market Analysis, Insights and Forecast - by Price Range
9.3.1. Economy
9.3.2. Mid-Range
9.3.3. Premium
9.4. Market Analysis, Insights and Forecast - by Distribution Channel
9.4.1. B2C/Retail
9.4.2. B2B/Project
9.4.3. Online Retail
9.4.4. Home Centers
9.4.5. Specialty Stores
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Home Furniture
10.1.2. Office Furniture
10.1.3. Hospitality Furniture
10.1.4. Other
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Wood
10.2.2. Metal
10.2.3. Plastic & Polymer
10.2.4. Glass
10.2.5. Other Materials
10.3. Market Analysis, Insights and Forecast - by Price Range
10.3.1. Economy
10.3.2. Mid-Range
10.3.3. Premium
10.4. Market Analysis, Insights and Forecast - by Distribution Channel
10.4.1. B2C/Retail
10.4.2. B2B/Project
10.4.3. Online Retail
10.4.4. Home Centers
10.4.5. Specialty Stores
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Inter IKEA Systems B.V.
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Sauder Woodworking Co.
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Dorel Industries Inc. (Dorel Home)
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Steinhoff International (Pepco & Conforama)
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Tvilum A/S
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. RTA Design Zona Franca S.A.S.
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global RTA Furniture Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America RTA Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 3: North America RTA Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 4: North America RTA Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 5: North America RTA Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 6: North America RTA Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 7: North America RTA Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 8: North America RTA Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 9: North America RTA Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 10: North America RTA Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 11: North America RTA Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe RTA Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 13: Europe RTA Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 14: Europe RTA Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 15: Europe RTA Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 16: Europe RTA Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 17: Europe RTA Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 18: Europe RTA Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 19: Europe RTA Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 20: Europe RTA Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe RTA Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific RTA Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 23: Asia Pacific RTA Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 24: Asia Pacific RTA Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 25: Asia Pacific RTA Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 26: Asia Pacific RTA Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 27: Asia Pacific RTA Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 28: Asia Pacific RTA Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 29: Asia Pacific RTA Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 30: Asia Pacific RTA Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific RTA Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 32: South America RTA Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 33: South America RTA Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 34: South America RTA Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 35: South America RTA Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 36: South America RTA Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 37: South America RTA Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 38: South America RTA Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 39: South America RTA Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 40: South America RTA Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: South America RTA Furniture Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa RTA Furniture Industry Revenue (Billion), by Application 2026 & 2034
Figure 43: Middle East & Africa RTA Furniture Industry Revenue Share (%), by Application 2026 & 2034
Figure 44: Middle East & Africa RTA Furniture Industry Revenue (Billion), by Material 2026 & 2034
Figure 45: Middle East & Africa RTA Furniture Industry Revenue Share (%), by Material 2026 & 2034
Figure 46: Middle East & Africa RTA Furniture Industry Revenue (Billion), by Price Range 2026 & 2034
Figure 47: Middle East & Africa RTA Furniture Industry Revenue Share (%), by Price Range 2026 & 2034
Figure 48: Middle East & Africa RTA Furniture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 49: Middle East & Africa RTA Furniture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 50: Middle East & Africa RTA Furniture Industry Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa RTA Furniture Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global RTA Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 2: Global RTA Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Global RTA Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 4: Global RTA Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 5: Global RTA Furniture Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America RTA Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 7: North America RTA Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 8: North America RTA Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 9: North America RTA Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 10: North America RTA Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe RTA Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 15: Europe RTA Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 16: Europe RTA Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 17: Europe RTA Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 18: Europe RTA Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Poland RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Turkey RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Asia Pacific RTA Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 25: Asia Pacific RTA Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 26: Asia Pacific RTA Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 27: Asia Pacific RTA Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 28: Asia Pacific RTA Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 29: China RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: India RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Japan RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: Vietnam RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: Indonesia RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: South America RTA Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 35: South America RTA Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 36: South America RTA Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 37: South America RTA Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 38: South America RTA Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 39: Colombia RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Brazil RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Middle East & Africa RTA Furniture Industry Revenue Billion Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa RTA Furniture Industry Revenue Billion Forecast, by Material 2020 & 2034
Table 43: Middle East & Africa RTA Furniture Industry Revenue Billion Forecast, by Price Range 2020 & 2034
Table 44: Middle East & Africa RTA Furniture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 45: Middle East & Africa RTA Furniture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 46: Morocco RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 47: South Africa RTA Furniture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the RTA furniture industry market?
The global RTA furniture industry market is valued at USD 17.58 billion in 2026, according to our proprietary research. It is projected to reach USD 25.24 billion by 2031, growing at a CAGR of 7.36%.
2Which region dominates the RTA furniture market?
North America is the largest market, holding a 35% share in 2025, driven by a strong DIY culture and high e-commerce penetration. However, Asia-Pacific is the fastest-growing region with a 6.93% CAGR.
3What are the key drivers of the RTA furniture market?
Key drivers include rapid urbanization and space constraints (+1.5% CAGR impact), DIY and personalization culture (+1.2%), sustainability trends (+0.9%), and residential construction (+1.8%). EU regulations like ESPR also favor RTA products (+0.6%).
4Who are the major players in the RTA furniture industry?
Major players include Inter IKEA Systems B.V., Sauder Woodworking Co., Dorel Industries Inc., Steinhoff International, Tvilum A/S, and emerging nearshore manufacturers like RTA Design Zona Franca S.A.S.
5What is the fastest-growing distribution channel for RTA furniture?
Online retail is the fastest-growing channel, forecast to expand at an 8.17% CAGR through 2031, driven by AR visualization, DTC models, and improved logistics. It is outpacing traditional home centers and specialty stores.
6How is sustainability impacting the RTA furniture market?
Sustainability is a major long-term driver (+0.9% CAGR impact). EU regulations like ESPR and Digital Product Passports require traceability and repairability, while consumer demand for FSC/PEFC-certified wood and recycled materials is growing.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted 150+ in-depth interviews with senior executives across the RTA furniture value chain, including CEOs, VPs of Product Development, and Procurement Directors.
70–80% of our research effort was dedicated to primary research, ensuring firsthand validation of market dynamics and competitive strategies.
Interviews were structured to capture granular data on production volumes, pricing trends, channel mix, and sustainability initiatives.
Participants were selected via stratified sampling to ensure representation across company sizes and regions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
CEO / Managing Director
25%
VP of Product Development
30%
Procurement Director
25%
Supply Chain Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Flat-Pack Furniture OEMs
30%
Contract Manufacturers (OEM/ODM)
25%
DTC & E-commerce Brands
20%
Retail Chains & Big-Box Retailers
15%
Raw Material & Component Suppliers
10%
Secondary Research & Industry Benchmarking
20–30% of our research involved rigorous secondary analysis of official trade statistics from UN Comtrade, Eurostat, US ITC, and OECD.
We benchmarked industry performance against recognized trade associations, including the Business and Institutional Furniture Manufacturers Association (BIFMA), the European Furniture Industries Confederation (EFIC), and the American Home Furnishings Alliance (AHFA).
Financial databases such as Bloomberg, Factiva, Hoovers, and PitchBook were used to validate company-level data and investment trends.
All sources are official .gov, .org, or recognized non-profit institutions; no commercial market research reports were used.
Demand Modeling & Market Estimation
We employed a dual top-down and bottom-up methodology, triangulating data from multiple levels.
Bottom-up: Built market size from the ground up by aggregating revenue from 4–5 specific company types: flat-pack furniture OEMs, contract manufacturers, DTC brands, retail chains, and e-commerce platforms.
Quantitative metrics used in the bottom-up calculation include: average selling price (ASP) per unit, unit volume shipments, square footage of retail space, and e-commerce conversion rates.
Top-down: Validated the bottom-up estimates against macroeconomic indicators, such as residential construction spending and household formation rates, sourced from the World Bank and US Census Bureau.
Multi-level data triangulation ensured consistency across segments and regions.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through rigorous validation and cross-referencing.
Every report is updated to the date of purchase, incorporating the latest available data and insights.
Data quality checks included outlier detection, consistency checks across segments, and expert review of all forecasts.
Final estimates were stress-tested against historical trends and industry benchmarks to ensure reliability.