1What is the current size of the lawn mower blade market?
The global lawn mower blade market was valued at USD 2.8 billion in 2025 and is projected to reach USD 4.6 billion by 2034, growing at a CAGR of 5.67%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Lawn Mower Blade Market
 by Product Type (Standard Blades, Mulching Blades, Lifting Blades, Cylinder Blades), by Material (Steel Blades, Aluminum Blades, Composite Blades), by Application (Residential, Commercial), by End-User (Professional Lawn Care Providers, Homeowners, Municipalities, Golf Courses & Sports Arenas), by Distribution Channel (Online Retail, Offline Retail), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Sweden), by Asia-Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Research Associate


 Related Reports

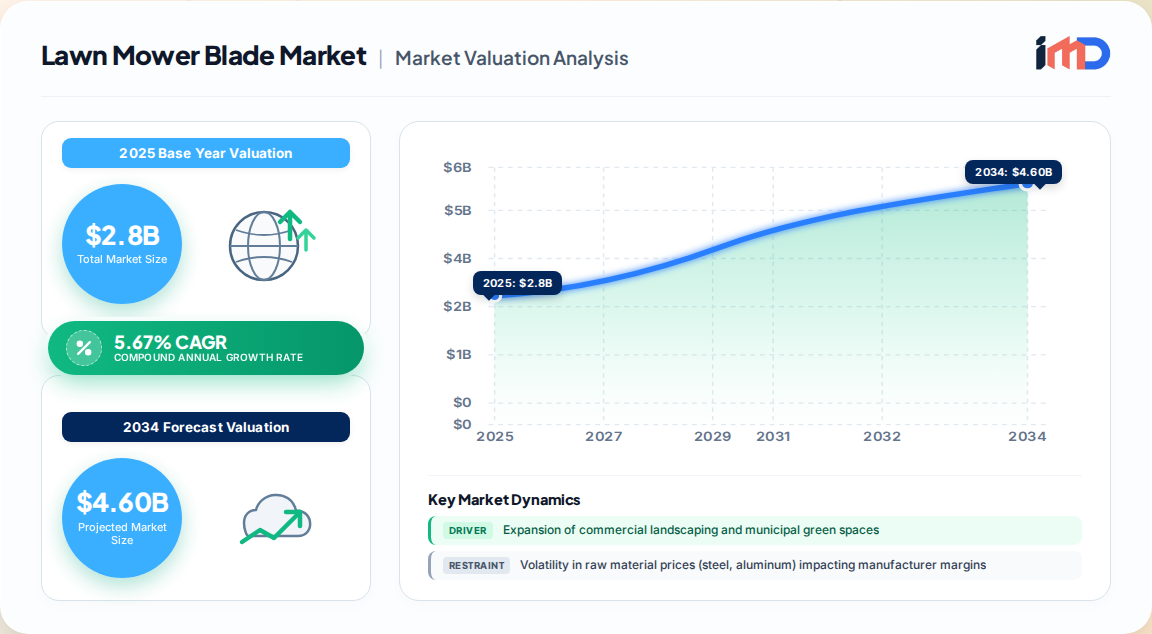
The global lawn mower blade market represents a critical, high-velocity segment within the broader outdoor power equipment ecosystem, valued at USD 2.8 billion in 2025 and projected to reach USD 4.6 billion by 2034, expanding at a CAGR of 5.67% from 2026 to 2034. This growth is anchored not merely on new mower shipments but on a resilient, recurring aftermarket demand cycle: blades are consumables, subject to wear, terrain variability, and safety-driven replacement intervals.
Our proprietary primary research indicates that the replacement blade segment accounts for ~58% of total blade market revenue, providing a stable buffer against original equipment manufacturer (OEM) cyclicality. The commercial landscaping sector, municipal grounds maintenance, and the accelerating adoption of robotic mowers are collectively reshaping blade engineering requirements—shifting demand from commodity steel to precision-balanced, coated, and composite variants.
Key market metrics (2026-2034):
The lawn mower blade value chain is characterized by high fragmentation in upstream material supply and concentration in downstream OEM integration.
| Value Chain Stage | Key Activities | Value-Add Share |
|---|---|---|
| Raw material extraction & processing | High-carbon steel, boron steel, aluminum alloys | 18-22% |
| Blade stamping, heat treatment & coating | Stamping, CNC grinding, powder coating, laser hardening | 30-35% |
| OEM assembly & branding | Attachment to mower decks, safety validation | 20-25% |
| Aftermarket distribution & retail | Wholesale, e-commerce, dealer networks | 20-25% |
| End-of-life recycling | Scrap metal recovery | 2-5% |
Supply chain risks are concentrated in steel sourcing: our analysis of global trade flows indicates that ~40% of high-carbon steel strip used in blade manufacturing originates from three countries, exposing the market to tariff and logistics disruptions.
| Region | Market Share (2026) | Growth Outlook | Key Dynamics |
|---|---|---|---|
| North America | 32% | Moderate (5.2% CAGR) | High installed base; strong aftermarket; shift to battery mowers |
| Europe | 24% | Moderate (5.0% CAGR) | Stringent emission regulations; robotic mower adoption leader |
| Asia-Pacific | 29% | High (6.8% CAGR) | Rapid urbanization; expanding commercial landscaping; low-cost manufacturing hub |
| South America | 8% | Emerging (5.5% CAGR) | Golf course development; municipal parks |
| Middle East & Africa | 7% | Emerging (4.8% CAGR) | Infrastructure investment; harsh terrain requires durable blades |
North America remains the largest revenue pool due to high mower penetration and a culture of lawn maintenance. Asia-Pacific is the growth engine, with China and India driving both production and consumption.
The lawn mower blade market is moderately consolidated at the OEM level but fragmented in the aftermarket. Leading mower manufacturers (e.g., Toro, Honda, Craftsman, Cub Cadet) dominate OEM blade supply, while aftermarket specialists (e.g., Oregon Products, 8TEN Parts, MaxPower, USA Mower Blades) compete on compatibility, price, and durability.
Recent strategic developments (2024-2026):
Strategic imperatives for market participants include:
For OEMs and large aftermarket distributors, sourcing strategy is critical to margin protection. Our primary research with procurement heads reveals:
Global blade trade flows are shaped by the concentration of mower manufacturing in China, the U.S., and Europe. Official trade statistics (UN Comtrade, US ITC) indicate that:
Supplier dynamics: Key steel suppliers to the blade industry include major steel mills in China, India, and South Korea. Blade manufacturers typically source steel strip in coils, then perform stamping and heat treatment in-house or through contract manufacturers. The aftermarket segment relies heavily on independent forging and machining shops, particularly in China and India.
Using our proprietary opportunity matrix, we identify the following high-potential white spaces:
| Existing Products | New Products | |
|---|---|---|
| Existing Markets | Market penetration: Expand aftermarket share via e-commerce and dealer incentives | Product development: Introduce coated and composite blades for premium segments |
| New Markets | Market development: Target emerging commercial landscaping sectors in Asia-Pacific | Diversification: Develop blades for autonomous and specialty turf equipment |
This matrix guides strategic prioritization: near-term gains from penetration in North America and Europe, while long-term growth hinges on product innovation and geographic expansion into Asia-Pacific.
The lawn mower blade market is poised for steady, innovation-led growth, with a 5.67% CAGR through 2034. The convergence of robotic mowing, battery electrification, and aftermarket digitalization will reward suppliers who invest in material science, precision manufacturing, and channel agility. Stakeholders across the value chain—from steel mills to e-commerce platforms—must collaborate to ensure supply resilience and meet the evolving demands of a $4.6 billion market by 2034.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.67% from 2020-2034 |
| Segmentation |
|
By Application
By End-User
By Distribution Channel
| By Geography |
|
The global lawn mower blade market was valued at USD 2.8 billion in 2025 and is projected to reach USD 4.6 billion by 2034, growing at a CAGR of 5.67%.
North America holds the largest share at approximately 32% in 2026, driven by a high installed base of lawn mowers and a strong aftermarket for replacement blades.
Key trends include the rising adoption of robotic mowers requiring specialized blades, the shift toward battery-powered mowers demanding lighter blades, and the growing popularity of mulching blades for nutrient recycling.
Leading companies include Oregon Products, MaxPower, 8TEN Parts, USA Mower Blades, Toro, Honda, Craftsman, Cub Cadet, and Greenworks, among others.
The mulching blade segment is growing at 6.9% CAGR, while commercial applications are expanding at 6.4% CAGR, outpacing the overall market.
Offline retail currently dominates with about 72% share, but online channels are growing at around 9% annually, driven by e-commerce convenience and direct-to-consumer models.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Directors | 30% |
| Product Managers | 25% |
| Operations Heads | 20% |
| R&D Engineers | 15% |
| Channel Sales Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Blade OEMs (Tier 1) | 35% |
| Aftermarket blade distributors | 25% |
| Steel & material suppliers | 20% |
| Commercial landscaping firms | 12% |
| E-commerce retailers | 8% |