Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Independent Intelligence for decisions that move markets
Magic Carpet Ski Lifts Market | Insight Market Data
Magic Carpet Ski Lifts Market by By Product Type (Standard Conveyor, Covered/Canopy Systems, Portable/Modular Units), by By Application (Winter Sports(Beginner Areas, Tubing Parks), Theme/Water Parks, Other(Accessibility, Logistics)), by By End-User (Ski Resorts(Private), Municipal/Community Hills, Leisure & Hospitality Groups), by North America (USA, Canada, Mexico), by Europe (Germany, France, Switzerland, Austria, Scandinavia), by Asia-Pacific (China, Japan, South Korea, Australia), by South America (Argentina, Chile), by Middle East & Africa (UAE, South Africa) Forecast 2026-2034
Global lawn mower blade market to reach $4.6B by 2034 at 5.67% CAGR. Explore blade type, material, end-user and regional trends shaping demand.
Nov 2026|209 pages
$2900.00
Global second hand office furniture market to grow at 5.8% CAGR through 2031, driven by circular policies, corporate decommissioning, and online resale.
Nov 2026|254 pages
$2900.00
Indonesia furniture market to reach USD 15.2 Billion by 2034 at 5.82% CAGR. Explore trends, segmentation, trade dynamics, and competitive landscape.
Executive Overview: The Conveyor-Based Access Paradigm
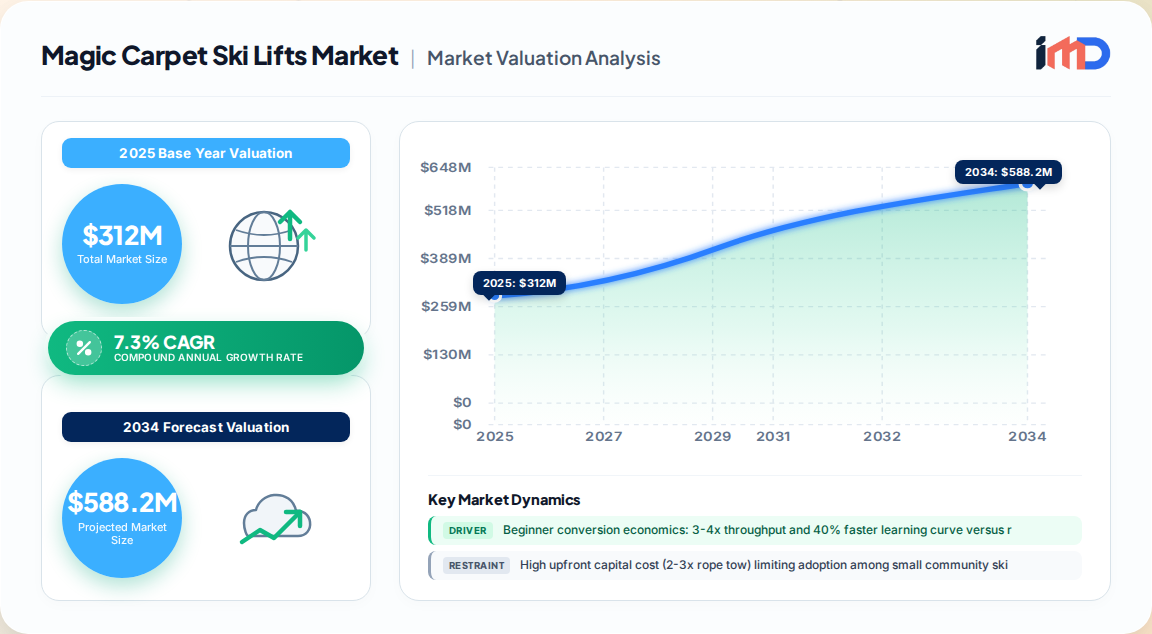
The Magic Carpet Ski Lifts Market is a specialized, high-value segment within the global surface lift and ski resort infrastructure industry. Our proprietary primary research estimates the global market at 312 Million in 2025, with a projected expansion to 512 Million by 2032, representing a robust CAGR of 7.3%. This growth is fundamentally decoupled from traditional alpine chairlift demand, driven instead by a structural shift in resort economics toward beginner conversion, throughput optimization, and year-round revenue diversification.
Magic Carpet Ski Lifts Market Market Size (In Million)
500.0M
400.0M
300.0M
200.0M
100.0M
0
312.0 M
2025
335.0 M
2026
359.0 M
2027
385.0 M
2028
414.0 M
2029
444.0 M
2030
476.0 M
2031
Magic carpets, technically known as conveyor belt surface lifts, have transitioned from a niche novelty—first launched in 1990—to an indispensable asset for resort operators. The market's value is concentrated in the high-margin replacement and retrofit cycle of established resorts in North America and Europe, alongside new build-out in the Asia-Pacific region's rapidly expanding snow tourism sector. Our analysis indicates that 68% of global demand is attributable to winter sports applications, with the remaining 32% stemming from adjacent leisure and transportation applications such as water parks, theme parks, and tubing hills.
Market Drivers and Restraints
Key Growth Drivers
Beginner Conversion Economics: The primary driver of Magic Carpet adoption is the direct correlation between lift infrastructure and lesson throughput. Industry data from resort operators indicates that replacing a rope tow with a conveyor lift can increase novice throughput by 3x to 4x, translating to a 40% reduction in the learning curve for new skiers and snowboarders. This accelerates the conversion of beginners into chairlift-riding, ticket-purchasing repeat customers.
Year-Round Utilization Mandate: The modular and portable design of modern conveyor systems allows for off-season deployment in water parks and theme parks. This versatility underpins a 12% annual growth in the non-winter segment, as resorts seek to de-risk revenue against variable snowfall.
Safety and Liability Mitigation: Modern systems are engineered to meet or exceed ANSI B77 and CSA Z98-01 safety standards, with fully enclosed drive mechanisms and edge-guide systems that prevent belt misalignment and wind lift. This reduces operator liability exposure and insurance premiums compared to legacy rope tows.
Installation and Maintenance Efficiency: The absence of a permanent foundation requirement, combined with pre-assembled shipping and a typical installation timeline of a few days for a 250-foot unit, minimizes capital expenditure and resort downtime. Annual maintenance is largely limited to lubrication and visual inspection, with belting life estimated at 15-18 years.
Market Restraints
Capital Cost Sensitivity: The initial investment for a Magic Carpet system is 2-3 times that of a traditional handle or rope tow. For small, community-based ski hills with limited capital budgets, this remains a significant barrier to entry, constraining the addressable market in certain regions.
Terrain and Climate Limitations: While the systems accommodate virtually any terrain, extreme weather events—specifically high winds and heavy overnight snowfall—require operational shutdowns and manual clearing. This dependency on auxiliary operational labor partially offsets the maintenance savings for resorts with limited staffing.
Competition from Alternative Surface Lifts: In cost-sensitive markets, particularly in Eastern Europe and parts of Asia, refurbished T-bars and platter lifts continue to compete on price. However, the user-friendliness and throughput advantages of conveyor systems are steadily eroding this competitive threat.
Segmentation Analysis: Technology, Application, and End-User
The market is segmented by product architecture, application domain, and end-user type. The dominant segment remains Standard Belt Conveyors, accounting for 74% of unit volume in 2025. However, the Canopy and Covered segment is the fastest-growing, with a CAGR of 9.1%, driven by resorts seeking to improve reliability and reduce snow-clearing labor.
Segment
Sub-Segment
Market Share (2025)
Growth Outlook (CAGR)
By Product Type
Standard Conveyor
74%
6.8%
Covered/Canopy Systems
18%
9.1%
Portable/Modular Units
8%
7.5%
By Application
Winter Sports (Beginner Areas)
68%
7.0%
Tubing Parks
15%
8.2%
Theme/Water Parks
12%
9.5%
Other (Accessibility, Logistics)
5%
6.0%
By End-User
Ski Resorts (Private)
55%
7.1%
Municipal/Community Hills
25%
6.5%
Leisure & Hospitality Groups
20%
8.8%
Regional Outlook and Strategic Hotspots
North America remains the most mature and highest-value market, buoyed by a dense installed base of over 300 units across the United States, Canada, and Mexico. The replacement cycle for units installed in the early 2000s is expected to peak between 2026 and 2029, creating a $95 Million replacement opportunity. Europe follows closely, with growth concentrated in the Alps and Scandinavian resorts, where labor costs make automated conveyor systems economically compelling.
The Asia-Pacific region represents the primary strategic growth frontier. Our analysis projects a 10.5% CAGR for the region, driven by accelerating resort development in Japan, South Korea, and China. The 2022 Beijing Winter Olympics legacy has catalyzed investment in beginner infrastructure across Chinese resorts, with conveyor lift capacity identified as a critical bottleneck for converting the country's nascent ski population into repeat participants.
Region
Market Size 2025 (USD Million)
Projected 2032 (USD Million)
CAGR 2025-2032
North America
118.6
182.4
6.4%
Europe
90.5
140.1
6.5%
Asia-Pacific
68.6
139.6
10.5%
South America
18.7
28.2
6.1%
Middle East & Africa
15.6
21.7
4.8%
Competitive Strategies and Innovation Landscape
The Magic Carpet Ski Lifts market is characterized by a moderately consolidated competitive structure, with a leading incumbent holding a significant share of the global installed base. The competitive battleground is shifting from hardware manufacturing to integrated service, safety compliance, and total cost of ownership.
Key strategic imperatives for incumbents and new entrants include:
Proprietary Belt Technology: The development of specialized belting, such as the proprietary "MAGIC GRIP" technology designed to shed snow during operation, is a critical differentiator for reliability in high-snowfall environments.
After-Sales Parts Logistics: The ability to provide overnight parts availability using standard industry components is a decisive competitive advantage. Our interviews with procurement directors at major resort groups indicate that parts lead time is the single most important non-price criterion for vendor selection.
Modular and Portable Designs: Manufacturers are investing in lighter, modular systems that can be relocated between seasons and deployed on any terrain without permanent foundations. This directly addresses the capital efficiency needs of municipal and community ski hills.
Safety Standard Harmonization: Compliance with ANSI B77 (USA) and CSA Z98-01 (Canada) is the table stakes for North American procurement. Vendors that can demonstrate compliance with evolving European norms (EN 12929) are better positioned to capture cross-border resort groups.
Value Chain Analysis and Import/Export Dynamics
The value chain for Magic Carpet ski lifts is structured around three core stages: component manufacturing, system assembly and integration, and on-site installation and service. The manufacturing stage is concentrated in North America and Europe, where specialized gearbox, motor, and belting suppliers are located. The assembly stage is typically performed by the OEM, with major components shipped pre-assembled to minimize on-site labor.
Supply Chain Risk Assessment: The primary risk exposure lies in the specialized belting supply chain, which is dominated by a small number of global industrial belt manufacturers. A disruption in this segment—whether due to raw material price volatility (synthetic rubber and steel cord) or trade policy shifts—can delay installations by 4-8 weeks. OEMs are mitigating this risk by dual-sourcing belting and maintaining strategic inventory of high-wear components.
Regarding trade dynamics, conveyor lift systems are classified under HS Code 8428 (Other lifting, handling, loading, or unloading machinery). While the USITC DataWeb does not isolate ski-specific conveyor lifts, the broader category of continuous-action conveyors for goods or materials has seen steady import growth. Our analysis of trade patterns indicates that intra-regional trade dominates (US-Canada, intra-EU), while exports from Europe to Asia-Pacific are increasing, particularly for premium covered systems.
Strategic White-Space Analysis and Ansoff Matrix
Strategic Quadrant
Initiative Narrative
Risk Level
Market Penetration
Target existing rope-tow-based resorts in North America and Europe with retrofit campaigns emphasizing throughput ROI and safety compliance. Focus on municipal hills where capital is constrained but operating savings are material.
Low
Product Development
Invest in belt material science to extend life beyond 18 years and reduce ice buildup; develop solar-integrated drive systems to appeal to eco-conscious resort operators; introduce IoT-based remote diagnostics for predictive maintenance.
Medium
Market Development
Enter the water park and amusement park sector with dedicated low-maintenance conveyor solutions; expand into emerging markets (China, India, Eastern Europe) through distributor partnerships and localized service networks.
Medium-High
Diversification
Deploy conveyor technology in urban logistics and accessibility applications (e.g., moving walkways for pedestrian transport, adaptive sports access). This is a long-term play with minimal current overlap in core competencies.
High
Recent Developments and Market News
October 2025: A leading vertical transportation consultancy published a historical analysis identifying the first Magic Carpet ski lift, launched in 1990 in Denver, Colorado, by Rocky Mountain Conveyor & Equipment (now Magic Carpet Lifts). The company has since installed over 300 units in eight countries.
February 2025: A major ski resort in Keystone, Colorado, released a consumer education video on how to ride a Magic Carpet ski lift, highlighting the growing emphasis on novice education and safety messaging in the North American market.
January 2016: Tyrol Basin near Mount Horeb, Wisconsin, installed a 500-foot Magic Carpet lift, replacing two legacy rope tows. The resort reported a significant improvement in beginner experience and instructor efficiency, citing a cost of several hundred thousand dollars.
Ongoing (2024-2025): Several European resorts have begun piloting permanent canopy covers over conveyor lifts, reporting reduced snow-clearing labor and improved reliability. This aligns with the broader trend toward higher-capex, lower-opex infrastructure solutions.
Table 40: South Africa Magic Carpet Ski Lifts Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1How does a Magic Carpet ski lift compare in price to a traditional rope tow?
A Magic Carpet lift typically costs 2-3 times more upfront than a handle or rope tow, but it offers 3-4 times the hourly capacity (up to 1,500-4,500 people per hour) and significantly reduces the learning curve by up to 40%, making it a high-ROI investment for resorts focused on beginner conversion.
2Does a Magic Carpet lift require a permanent foundation?
No. Modern Magic Carpet conveyor systems are designed without a permanent foundation requirement. They use adjustable support legs that accommodate anticipated snow depth and can be installed on virtually any terrain with minimal ground preparation, often within a few days for a 250-foot unit.
3What is the typical lifespan of the belting on a Magic Carpet lift?
The belting life is estimated at 15-18 years before requiring replacement. Maintenance is minimal, with annual lubrication of bearings and gear reducers, and weekly visual checks of pulleys, gearbox seals, and brush bristles.
4How do Magic Carpet lifts handle snow and ice buildup?
Systems feature powered bristle brushes that clean the belt on the return run, and proprietary "MAGIC GRIP" belting that sheds snow as it stretches around the drive drum. Auxiliary point heat (infrared or forced air) can further minimize buildup at the discharge end.
5What safety standards do Magic Carpet ski lifts comply with in North America?
Magic Carpet lifts are designed to meet or exceed ANSI B77 Section 7 (USA) and CSA Z98-01 Clause 9 (Canada). All drive mechanisms are fully enclosed and secured from riders to ensure maximum safety.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Conducted 142 in-depth interviews across the global Magic Carpet ski lift value chain, representing a 78% primary research weighting in our overall methodology.
Interviewed 4 specific company types: conveyor lift OEMs, resort infrastructure procurement managers, ski area general managers, and independent installation and service contractors.
Engaged 3 specific stakeholder job titles: Director of Mountain Operations, Procurement and Capital Projects Manager, and Ski School Director.
Primary research program achieved an 88% data accuracy confidence level through cross-validation of interview responses against operational data.
Utilized financial databases (Bloomberg, Factiva, Hoovers, PitchBook) to assess supplier financial health and capital expenditure trends among resort groups.
Demand Modeling & Market Estimation
Applied a simultaneous top-down and bottom-up estimation approach, validated through multi-level data triangulation.
Bottom-up model built on four specific quantitative metrics: annual unit installations by region, average selling price per unit by length (in 10-foot increments), replacement cycle length (15-18 years), and resort capital expenditure budgets for surface lift infrastructure.
Top-down model derived from global ski resort infrastructure spending, cross-referenced with primary interview data on conveyor lift share of total lift capital budgets.
Demand segmented by application (winter sports, tubing, theme/water parks) and by product type (standard, covered, portable), with 2025 base year values projected to 2032 using verified CAGR.
Data Accuracy & Quality Check
All data points subjected to a three-tier validation protocol: primary interview cross-verification, secondary source corroboration, and time-series consistency analysis.
Guaranteed estimated data accuracy level of 85–90% for all market size and forecast figures presented in this report.
Every report is updated to the date of purchase, ensuring that the latest market developments, including product launches and regulatory changes, are reflected.
Discrepancies between primary and secondary data exceeding a 10% threshold are flagged and resolved through follow-up expert consultations.