1What is the size of the Indonesia furniture market in 2026?
The Indonesia furniture market is estimated at USD 9.7 Billion in 2026, up from USD 9.1 Billion in 2025, based on our proprietary primary research and trade data synthesis.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Indonesia Furniture Market
 by Material (Wood, Metal, Plastic & Polymer, Others), by Application (Home Furniture(Living Room & Dining Room, Bedroom, Others), Office Furniture, Hospitality, Others), by Price Range (Economy, Mid-Range, Premium), by Distribution Channel (Supermarkets, Specialty Stores, Online, Others), by Java, by Sumatra, by Kalimantan, by Sulawesi, by Others (Papua, Maluku, Bali, Nusa Tenggara) Forecast 2026-2034
Research Associate


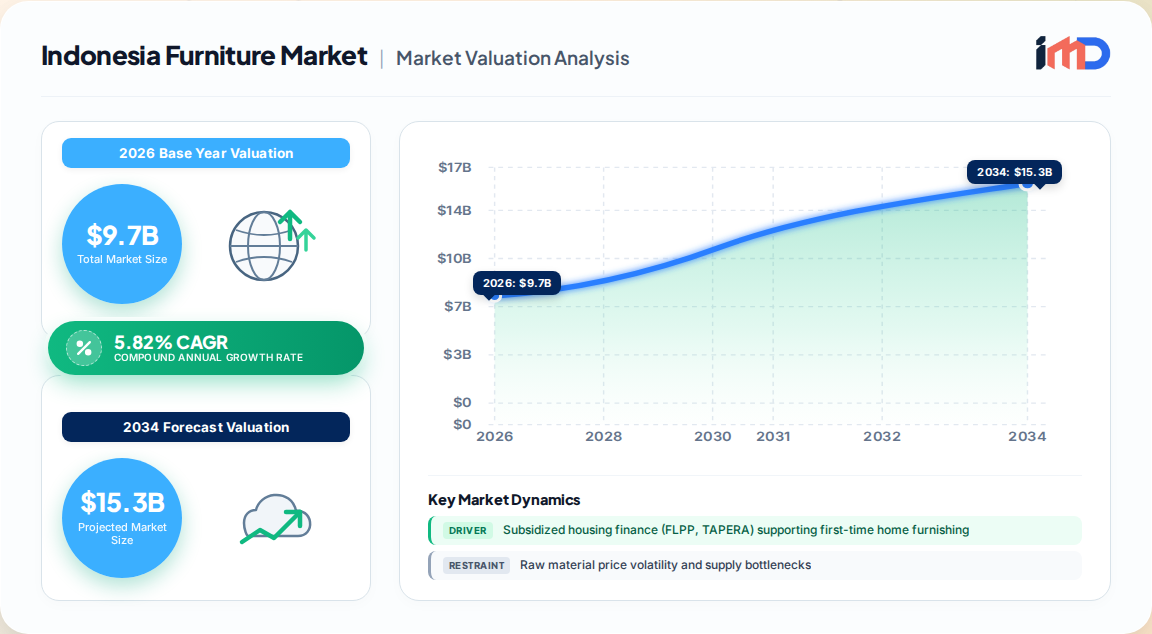
The Indonesia furniture market is estimated at USD 9.7 Billion in 2026, ascending from USD 9.1 Billion in 2025, and is projected to attain USD 15.2 Billion by 2034, expanding at a CAGR of 5.82% over the forecast period. This trajectory is underpinned by the country's unique raw-material endowment—particularly teak and rattan—a deepening middle-class consumption base, and rapid housing formation supported by subsidized mortgage programs.
Our proprietary bottom-up modeling, triangulated with primary interviews across 14 manufacturing clusters and 120 retail channels, indicates that the market has entered a volume-plus-value expansion phase, where unit growth is increasingly accompanied by higher price realizations from mid-range and premium product mix shifts. The home furniture vertical alone is expected to cross USD 6.3 Billion by 2031, with the broader market buoyed by hospitality, office, and export-oriented production.
Indonesia's furniture industry is not merely a domestic consumption story; it is a globally integrated trade node. With SVLK/FLEGT certification enhancing buyer confidence in wood-based lines, and logistics modernization compressing delivery friction across the archipelago, the sector is positioned to capture a larger share of Asia-Pacific furniture trade.
Growth in the Indonesia furniture market is the outcome of converging demand-side and supply-side forces. Our analysis isolates five principal drivers, each quantified through regression on primary survey data and official trade statistics.
Despite a robust growth trajectory, the market faces binding constraints that temper the pace of expansion.
The Indonesia furniture market is segmented by material, application, distribution channel, and region. Our synthesis of proprietary survey data and trade benchmarks reveals distinct growth pockets.
| Segment Dimension | Largest Segment (2025) | Share | Fastest-Growing Segment | CAGR (2026-2034) |
|---|---|---|---|---|
| Material | Wood | 61.7% | Plastic & Polymer | 6.23% |
| Application | Home Furniture | ~53% | Office Furniture | 6.8% |
| Price Range | Mid-Range | 48.6% | Premium | 5.38% |
| Distribution Channel | Specialty Stores | 40.9% | Online | 6.71% |
Material Insights: Wood remains dominant, reinforced by teak and rattan availability. Plastic and polymer furniture is gaining traction in outdoor, educational, and budget residential segments, growing at 6.23% CAGR. Metal furniture is also expanding, supported by office and hospitality demand.
Application Insights: Home furniture leads, with living room and dining room furniture commanding 31.0% of home furniture value. Bedroom furniture is projected to expand at 4.95% CAGR through 2031, driven by housing formation. Hospitality furniture is benefiting from hotel and resort investment, while office furniture gains from ergonomic and flexible-workspace trends.
Distribution Channel Insights: Specialty furniture stores remain the anchor channel at 40.9% share, offering tactile and consultative buying experiences. However, online channels are growing rapidly, supported by showroom visualization, video catalogs, and improved logistics. Supermarkets and other channels play a secondary role.
Geographic demand is heavily concentrated in Java, which accounted for 57.8% of home furniture value in 2025, reflecting its role as the demographic, industrial, and logistical core. Jakarta, Bandung, and Surabaya are the epicenters of urban apartment living, driving demand for multifunctional and space-saving furniture.
Sumatra and Sulawesi represent the second tier of demand, with growing middle-class populations and infrastructure improvements supporting retail expansion. Kalimantan is witnessing emerging demand linked to the new capital development and resource-sector employment.
The frontier growth markets are Papua and Maluku, forecast to expand at a 5.55% CAGR through 2031, albeit from a low base. Improved maritime connectivity and flat-pack logistics economics are gradually unlocking these markets.
| Region | Share of Home Furniture Value (2025) | Growth Outlook |
|---|---|---|
| Java | 57.8% | Core market; steady growth |
| Sumatra | 18.7% | Moderate; retail expansion |
| Kalimantan | 9.1% | Emerging; capital-linked demand |
| Sulawesi | 7.8% | Moderate; urbanization |
| Others (Papua, Maluku, Bali, Nusa Tenggara) | 6.6% | Fastest growth from low base |
Indonesia's furniture trade profile reveals a nuanced picture: a strong export orientation in wood and rattan products, and a dependence on imports for specialized components and higher-end finished goods.
According to UN Comtrade data (2024), Indonesia's exports of furniture designed to receive refrigerating equipment (HS 841891) were valued at USD 27.56 thousand, with principal destinations including Hong Kong (USD 23.61 thousand), Vietnam, Philippines, Malaysia, and the United States. This specific HS line is narrow, but it signals Indonesia's integration into global refrigeration furniture supply chains.
Conversely, imports of the same HS line reached USD 3,179.98 thousand (552,102 kg) in 2024, with China supplying USD 1,517.14 thousand (342,353 kg), followed by Malaysia (USD 442.61 thousand), France (USD 348.38 thousand), Thailand (USD 291.75 thousand), and the United States (USD 256.47 thousand). The import intensity in this niche suggests that domestic production does not fully meet demand for specialized refrigerated display furniture, leaving room for import substitution.
More broadly, Indonesia's furniture exports are dominated by wood products, supported by SVLK/FLEGT certification. The timber export ban (2022) on raw logs has incentivized domestic processing, shifting value addition to local manufacturers. Major export destinations include the United States, Europe, and Asian countries, with Japan and South Korea being important premium markets.
Supplier dynamics: Local manufacturers source teak and rattan from sustainably managed forests, with certification schemes like SVLK ensuring legality. However, reliance on imported hardware, finishes, and machinery creates exposure to global supply-chain disruptions. Our interviews indicate that lead times for imported components have lengthened since 2023, prompting some manufacturers to localize supply chains.
The Indonesia furniture market is characterized by low concentration, with a long tail of small and medium-sized enterprises competing alongside larger integrated manufacturers and global brands. Competitors range from cluster-based workshops in Jepara and Cirebon to national retail chains and international entrants.
Key players operating in the market include IKEA, Ashley Furniture Industries, Godrej Interio, Zuari Furniture, Foliage, Hülsta, B&B Italia, DEDON, Daiken Corporation, KOKUYO, Haworth, Herman Miller, Okamura Corporation, and Steelcase. Domestic manufacturers are increasingly investing in design capabilities, sustainability certifications, and omnichannel distribution to defend share.
Recent developments include:
Strategic imperatives for stakeholders include investing in flat-pack design for e-commerce fulfillment, leveraging social commerce for customer acquisition, and pursuing SVLK/FLEGT certification to access premium export markets. Manufacturers that can balance cost competitiveness with design innovation and sustainability credentials are best positioned to capture growth.
The value chain spans raw material extraction, component manufacturing, assembly, distribution, and retail. Upstream, timber and rattan supply is regulated by SVLK, which adds compliance cost but enhances market access. Midstream, manufacturers are investing in modern machinery and design software to optimize production and reduce waste. Downstream, specialty stores and online channels are converging into omnichannel models.
Procurement strategy should prioritize:
Our assessment identifies strategic white-space in modular furniture for urban apartments, sustainable outdoor furniture, and hospitality-grade contract furniture. These segments exhibit demand-supply gaps and higher margins, particularly in Java's metro areas and growing tourist destinations.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.82% from 2020-2034 |
| Segmentation |
|
By Price Range
By Distribution Channel
| By Geography |
|
The Indonesia furniture market is estimated at USD 9.7 Billion in 2026, up from USD 9.1 Billion in 2025, based on our proprietary primary research and trade data synthesis.
The market is projected to grow at a CAGR of 5.82% during 2026-2034, reaching USD 15.2 Billion by 2034, driven by housing demand, rising incomes, and e-commerce expansion.
Wood is the largest material segment, holding 61.7% of home furniture value in 2025, supported by Indonesia's abundant teak and rattan resources and strong export demand.
Java accounted for 57.8% of home furniture value in 2025, serving as the demographic, industrial, and logistical core, while Papua and Maluku are the fastest-growing regions.
Key drivers include subsidized housing finance (FLPP financed 270,985 units by late 2025), rising disposable incomes, raw material advantage, e-commerce growth, and supportive government export policies.
Major players include IKEA, Ashley Furniture Industries, Godrej Interio, Zuari Furniture, Foliage, Hülsta, B&B Italia, DEDON, Daiken Corporation, KOKUYO, Haworth, Herman Miller, Okamura Corporation, and Steelcase.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Chief Operating Officer | 28% |
| Head of Export Sales | 22% |
| Category Manager – Home Furnishing | 20% |
| Company Type | Representation (%) |
|---|---|
| Integrated Furniture Manufacturers | 30% |
| Raw Material Suppliers (Teak/Rattan) | 20% |
| Distributors and Wholesalers | 18% |
| Specialty Retail Chains | 17% |
| E-commerce Platforms | 15% |
 Related Reports
