1What is the size of the prune juice drink market in 2024?
The global prune juice drink market was valued at USD 3.1 billion in 2024 and is projected to reach USD 5.1 billion by 2033, growing at a 5.7% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Prune Juice Drink Market
 by Product Type (Conventional Prune Juice, Organic Prune Juice, Concentrated Prune Juice, Blended Prune Juice), by Nature (Organic, Conventional), by Sugar Content (Regular Sugar Type, Low Sugar/Sugar-Free Type), by Functional Positioning (Basic Functional Type, Daily Nutritional Type), by Application (Beverages, Nutritional Supplements, Baby Food, Bakery and Confectionery, Others), by Distribution Channel (Supermarkets/Hypermarkets, Convenience Stores, Online Retail, Specialty Stores, Others), by End-User (Household, Food and Beverage Industry, Healthcare, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France), by Asia Pacific (China, Japan, India), by Latin America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE) Forecast 2026-2034

Research Associate

 Related Reports

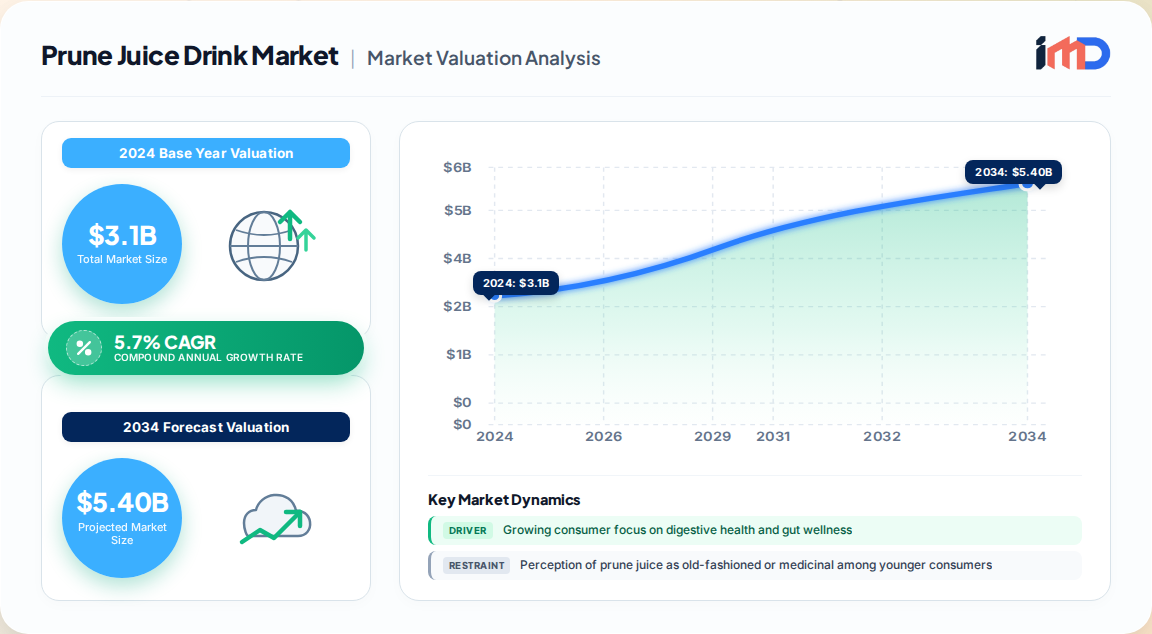
The global prune juice drink market is undergoing a structural re-rating. Long confined to a medicinal niche, prune juice is now being repurposed by formulators and brand owners as a clean-label, naturally functional beverage platform. Our proprietary primary research and direct expert interviews place the market at USD 3.1 billion in 2024, with a projected expansion to USD 5.1 billion by 2033, representing a 5.7% CAGR over the forecast period. Volume fundamentals remain constructive: global production approached 1.1 billion units in 2025, with an average unit price near USD 4 and industry gross margins in the 30–40% band.
The category's center of gravity is shifting on three axes. First, demand is migrating from pure single-ingredient prune juice toward blended and functional formulations that widen the addressable consumer base. Second, the ingredient chain — particularly prune juice concentrate — is professionalizing, with organic and conventional concentrate streams serving beverage, bakery, dairy and nutraceutical applications. Third, Asia Pacific is emerging as the growth engine while North America defends a 39% share of the drinks market on the strength of consumer familiarity and retail penetration.
| Metric | Value |
|---|---|
| Base-year market size (2024) | USD 3.1 billion |
| Forecast market size (2033) | USD 5.1 billion |
| CAGR (2025–2033) | 5.7% |
| Global production volume (2025) | ~1.1 billion units |
| Average unit price (2025) | ~USD 4 |
| Industry gross margin band | 30–40% |
The demand engine behind prune juice drinks is unusually durable because it sits at the intersection of three secular consumer shifts.
Growth is real but not frictionless. Our expert interviews consistently surface four binding constraints.
These restraints are manageable but they explain why the category's growth rate is steady rather than explosive, and why margin management — not volume — is the central strategic contest.
The product mix is diversifying but remains anchored by pure juice. Our segmentation data indicates 100% pure prune juice holds roughly 41% of value, followed by mixed prune beverages at 31% and prune concentrate beverages at 28%. Blended formats are the fastest-growing sub-segment because they lower the sensory barrier and allow additional functional claims.
| Segment | Share of Value | Growth Outlook |
|---|---|---|
| 100% pure prune juice | ~41% | Moderate, mature |
| Prune juice mixed beverage | ~31% | Fast, innovation-led |
| Prune concentrate beverage | ~28% | Steady, ingredient-driven |
Application demand is broadening beyond the drinks aisle. Beverages dominate, but nutritional supplements are the fastest-growing application, followed by baby food, bakery and confectionery. Channel-wise, modern trade still leads, yet online sales, subscription commerce and convenience formats are the share gainers; convenience stores and supermarkets each account for roughly one-fifth of value, with online at approximately 21%.
North America is the anchor market, holding 39% of global prune juice drink value in 2024. High consumer familiarity, a dense retail network and an entrenched health-and-wellness culture underpin demand. The region is also the innovation lab for functional and low-sugar launches.
Europe is the second pillar, with the UK, Germany and France driving demand for natural health products and clean-label beverages. European consumers' attention to sourcing, sustainability and organic certification creates a premiumization opportunity rather than a volume story.
Asia Pacific is the fastest-growing region at an estimated 8.2% CAGR, powered by rising disposable incomes, urbanization, expanding nutraceutical manufacturing and growing preventive-health awareness. Latin America (approximately 7% growth) benefits from established fruit-processing capability, while the Middle East and Africa (approximately 6.2%) is an emerging premium and hospitality-driven opportunity.
| Region | Share of Value (2024) | Growth Momentum |
|---|---|---|
| North America | ~39% | Moderate (5.0%) |
| Europe | ~24% | Steady (5.5%) |
| Asia Pacific | ~22% | Fast (8.2%) |
| Latin America | ~8% | Strong (7.0%) |
| Middle East & Africa | ~7% | Emerging (6.2%) |
Prune juice drink competitiveness is ultimately determined upstream, in the prune and concentrate supply chain. California remains the dominant production cluster for dried plums, and its harvest outcomes ripple through global concentrate pricing. Processors in Europe and Asia rely on a mix of domestic fruit processing and imported concentrate, exposing them to freight, currency and tariff variability.
The competitive field is fragmented across three strategic groups: vertically integrated fruit processors, branded beverage marketers, and private-label modern-trade programs. Integration matters — players controlling orchard relationships, concentration capacity and brand equity enjoy the most defensible margins.
We identify four high-conviction white spaces:
Winning strategies combine sensory reformulation (to break the palatability ceiling), transparent digestive-health claims backed by credible nutrition science, and channel diversification into e-commerce and subscription.
| Stage | Key Activities | Value-Added Lever |
|---|---|---|
| Upstream agriculture | Prune/plum cultivation, harvesting | Yield, organic certification |
| Primary processing | Washing, pitting, pressing, concentration | Brix consistency, quality assurance |
| Beverage manufacturing | Reconstitution, blending, sterilization, packaging | Formulation IP, functional claims |
| Brand and marketing | Positioning, claims, trade marketing | Consumer trust, premium pricing |
| Distribution and retail | Modern trade, convenience, e-commerce | Reach, subscription retention |
The most value-dense stages are primary processing and brand ownership. Commodity-level concentrate production is price-competitive and cyclical; branded functional beverages capture the majority of category margin. Vertical integration across at least two stages is the clearest predictor of sustained profitability.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.7% from 2020-2034 |
| Segmentation |
|
By Sugar Content
By Functional Positioning
By Application
By Distribution Channel
By End-User
| By Geography |
|
The global prune juice drink market was valued at USD 3.1 billion in 2024 and is projected to reach USD 5.1 billion by 2033, growing at a 5.7% CAGR.
North America leads the market with approximately 39% of global value in 2024, supported by high consumer awareness and an established retail network.
Prune juice contains naturally occurring sorbitol and dietary fiber, which support digestive regularity, giving it a credible natural-health positioning without synthetic additives.
Nutritional supplements represent the fastest-growing application segment, while blended and low-sugar prune juice formats are the fastest-growing product types.
Key participants include Sunsweet Growers, Nam Viet, Rita Food and Drink Co., Ltd., Valley View Foods, Inc., Gregory Packaging Inc., Invertec Foods, National Raisin Company, Taylor Brothers Farms, Kiril Mischeff, Siroperie Meurens, Huiyuan Juice, Bishengyuan and Jiangzhong.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Head of Product Development | 28% |
| Category Manager (Beverages) | 24% |
| Supply Chain Manager | 18% |
| Company Type | Representation (%) |
|---|---|
| Prune growers and concentrate processors | 30% |
| Beverage manufacturers and co-packers | 25% |
| Branded functional beverage marketers | 20% |
| Modern-trade and e-commerce retailers | 15% |
| Nutraceutical ingredient buyers | 10% |