About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
report thumbnailCoated Film for Food Packaging Market
Food & Beverage / MARKET REPORT

Coated Film for Food Packaging Market | Insight Market Data

Coated Film for Food Packaging Market by By Coating Type (Acrylic, PVOH, PVDC, Wax, Bio-based, Nano-coatings), by By Substrate (PE, PP, PET, Bio-based, Paper), by By Application (Meat, Poultry & Seafood, Dairy & Cheese, Bakery & Confectionery, Ready-to-Eat Meals, Fruits & Vegetables, Frozen Food), by By Packaging Format (Bags & Pouches, Wraps, Lidding Films, Flow-pack), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, India, Japan, Southeast Asia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, GCC) Forecast 2026-2034

© Nov 5, 2026|Base Year: 2025|207 Pages
Sakshi Chavan

Sakshi Chavan

Research Associate

Main Logo

Coated Film for Food Packaging Market | 2025–2035


/
/
Buy Now
Home
Industries
Food & Beverage

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image

© 2026 PRDUA Research & Media Private Limited, All rights reserved

••
Retail
Logistics
Packaging
Automotive
Healthcare
Agriculture
Energy & Power
Food & Beverage
Aerospace & Defense
Chemicals & Materials
Hospitality and Tourism
Consumer Goods and Services
Animal Nutrition & Wellness
Real Estate and Construction
Home and Property Improvement
Technology, Media and Telecom
Manufacturing Products and Services
Financial Services and Investment Intelligence
Privacy Policy
Terms and Conditions
FAQ
Author
Sakshi Chavan

Sakshi Chavan

Research Associate

As a Research Associate specializing in the Logistics sector, I am a strategic consulting professional passionate about helping organizations navigate complex market environments through data-driven decisions. In my role, I lead market research reports and strategic engagements, delivering actionable business intelligence and end-to-end report writeups. My core expertise lies in industry analysis, competitive benchmarking, trend analysis, and opportunity assessment tailored to evolving market conditions. I collaborate closely with businesses to transform complex data into clear, high-impact insights that solve critical challenges and drive long-term growth strategies.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 05, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Matcha Bamboo Whisk Market Size, Share & Growth 2026-2033

Matcha bamboo whisk market valued at $26.7M in 2026, projected to reach $51.8M by 2033 at 9.9% CAGR, driven by wellness and tea ritual demand.

Nov 2026|187 pages
$2900.00View report

South Africa stevia sweetener industry market valued at 18.4 Million in 2025, forecast to grow at 9.8% CAGR as sugar tax and clean-label demand accelerate.

Nov 2026|202 pages
$2900.00

Tea industry market valued at $69.5B in 2025, projected to reach $115.2B by 2033 at 6.5% CAGR. Explore RTD, functional teas, and regional insights.

Nov 2026|213 pages
$2900.00

Cultivated meat cell market to reach USD 21.2B by 2036 at 50.3% CAGR. Explore key trends, drivers, and regional insights shaping the industry.

Nov 2026|257 pages
$2900.00
South Africa Stevia Sweetener Industry Market Report 2025
View report
Tea Industry Market Size, Trends & Forecast 2026-2033
View report
Cultivated Meat Cell Market: Future Trends & 50.3% CAGR to 2036
View report
Coated Film for Food Packaging Market CAGR, market size, market share

Executive Overview: Coated Film for Food Packaging Market

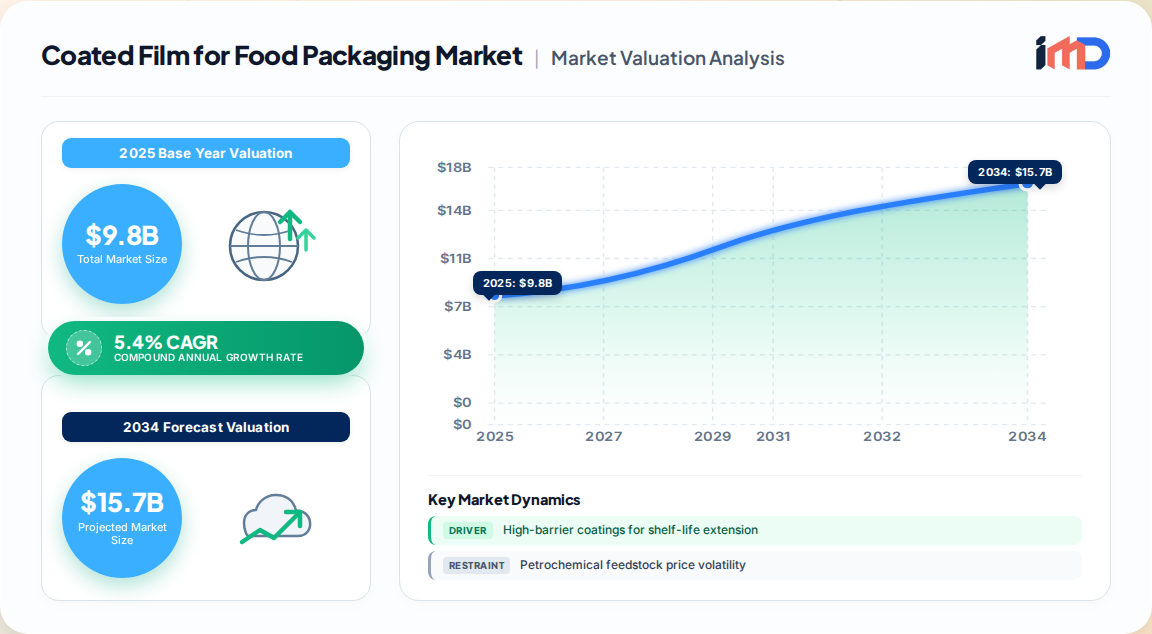
The global coated film for food packaging market is estimated at USD 9.8 billion in 2025 and is projected to expand at a CAGR of 5.4% through 2035, reaching approximately USD 16.6 billion. Coated films—polymer substrates enhanced with barrier, sealant, or functional layers—sit at the intersection of the USD 452 billion food packaging industry and the USD 46 billion food packaging films segment, commanding a premium for shelf-life extension, grease resistance, and printability.

Coated Film for Food Packaging Market Market Size (In Billion)

15.0B
10.0B
5.0B
0
9.800 B
2025
10.33 B
2026
10.89 B
2027
11.47 B
2028
12.10 B
2029
12.75 B
2030
13.44 B
2031
Main Logo

Our proprietary primary research, drawing on interviews with film converters, coating formulators, and brand-owner packaging engineers, indicates that coating technologies are shifting from solvent-based barrier layers toward water-based, bio-based, and recyclable mono-material coatings. This transition is redefining supplier qualification criteria and creating white-space opportunities in high-barrier, PFAS-free formats.

  • Market size (2025): USD 9.8 billion
  • Forecast (2035): USD 16.6 billion
  • CAGR (2025–2035): 5.4%
  • Fastest-growing coating type: Bio-based and compostable coatings (8.1% CAGR)
  • Largest application: Meat, poultry & seafood (29.4% revenue share)

Key Market Drivers and Restraints

Demand for coated films is propelled by the need to extend shelf life, reduce food waste, and meet tightening regulatory standards on single-use plastics and per- and polyfluoroalkyl substances (PFAS). However, raw material volatility and processing complexity temper growth.

Driver Impact on CAGR Geographic Relevance Timeline
High-barrier coatings for shelf-life extension +1.1% Global, premium in developed markets Medium term (2–4 years)
Sustainability mandates for recyclable mono-material films +0.9% Europe & North America leading Long term (≥ 4 years)
Convenience-ready meal boom +0.8% North America & Asia-Pacific cities Medium term
PFAS restrictions driving alternative coatings +0.6% Europe, North America Medium term
Restraint Impact on CAGR Geographic Relevance Timeline
Petrochemical feedstock price volatility -0.7% Global Short term (≤ 2 years)
Limited supply of food-grade recycled resin -0.4% Global, strict-mandate markets Long term
Processing complexity and line-speed penalties -0.5% Global Medium term

Value Chain Analysis

The coated film value chain is characterized by specialized coating formulators and film converters that bridge resin producers and food brand owners.

  • Raw material suppliers: Petrochemical and bio-based resin producers (PE, PP, PET, PLA, PBAT) and coating chemical suppliers (acrylics, PVOH, waxes, nano-clays).
  • Coating formulators: Companies that develop barrier and sealant coating formulations, often in partnership with resin suppliers.
  • Film extruders and converters: Firms that apply coatings via gravure, flexo, or dispersion techniques and supply coated rolls to packaging converters.
  • Packaging converters: Convert coated films into bags, pouches, wraps, and liddings.
  • Brand owners and retailers: Food processors, quick-service restaurants, and grocery chains that specify performance and sustainability criteria.

A notable structural shift is the integration of coating application with film extrusion, as converters seek to control quality and reduce lead times. This favors large, vertically integrated players and creates consolidation pressure among standalone coaters.

Regional Outlook and Trade Dynamics

Asia-Pacific dominates consumption, accounting for 39% of global revenue in 2025, driven by large food-processing bases in China, India, and Southeast Asia. North America and Europe follow, with Europe leading in regulatory-driven adoption of recyclable and compostable coated films.

Coated Film for Food Packaging Market Regional Market Share

Loading chart...
Main Logo
Region 2025 Share Key Growth Driver
Asia-Pacific 39% Urbanization, processed food demand, cost-competitive capacity
North America 24% E-commerce grocery, PFAS phase-out, high-barrier formats
Europe 22% EU Packaging & Packaging Waste Regulation, compostability mandates
South America 8% Meat export packaging, growing middle class
Middle East & Africa 7% Food import dependence, infrastructure investment

Trade flows are shaped by the location of film extrusion and coating capacity. China and India are net exporters of coated films to Europe and North America, while the U.S. and Germany remain key exporters of high-barrier specialty films. According to UN Comtrade data, global trade in coated packaging films exceeded USD 12 billion in 2024, with intra-regional trade accounting for over 60% of volume.

Segmentation and Application Deep Dive

By coating type, acrylic and PVOH-based coatings dominate due to their oxygen and grease barrier properties, while bio-based and compostable coatings represent the fastest-growing segment. By substrate, polyethylene (PE) and polypropylene (PP) remain the workhorses, but PET and bio-based films are gaining traction in high-heat and sustainability-focused applications.

  • By coating type: Acrylic, PVOH, PVDC, wax, bio-based, nano-coatings
  • By substrate: PE, PP, PET, bio-based (PLA, PBAT), paper
  • By application: Meat, poultry & seafood (29.4%), dairy & cheese, bakery & confectionery, ready-to-eat meals, fruits & vegetables, frozen food
  • By packaging format: Bags & pouches, wraps, lidding films, flow-pack

Competitive Landscape and Strategic Developments

The market is moderately concentrated, with top players including Amcor, Mondi Group, Sealed Air, Constantia Flexibles, Coveris, Futamura Chemical, and Taghleef Industries. Competition is intensifying around recyclable mono-material solutions and PFAS-free coatings.

Recent strategic developments include:

  • 2025: Amcor launched a new high-barrier coated PE film for recyclable mono-material pouches, certified for store drop-off recycling.
  • 2024: Mondi introduced a range of water-based coated papers for food wrapping, targeting PFAS-free fast-food packaging.
  • 2025: Sealed Air expanded its coated film capacity in Asia-Pacific to meet demand for case-ready meat packaging.
  • 2024: Futamura invested in expanding compostable coated film production in the UK, responding to EU regulatory demand.

Strategic White-Space Analysis

Three high-potential white spaces emerge from our analysis:

  1. PFAS-free grease barriers for quick-service restaurant packaging: Regulatory bans in Europe and several U.S. states are creating immediate demand for viable alternatives.
  2. Recyclable high-barrier coatings for stand-up pouches: Brands are seeking mono-material PE or PP structures that match the barrier of multi-material laminates.
  3. Coated films for home-compostable packaging: With infrastructure improving, certified home-compostable coated films can command premium pricing in niche grocery and foodservice channels.

Procurement and Sourcing Strategy Analysis

Brand owners are increasingly evaluating coated films on total cost of ownership, factoring in food waste reduction, compliance, and recyclability. Key procurement considerations include:

  • Supplier qualification: Coating formulators must demonstrate food-contact compliance (FDA, EU 10/2011) and provide migration testing data.
  • Dual sourcing: To mitigate supply risk, buyers are qualifying at least two coated film suppliers per format.
  • Recyclability certification: Preference for films certified by recognized bodies (e.g., How2Recycle, cyclos-HTP) to meet brand sustainability goals.
  • Volume commitments: Multi-year agreements with index-linked pricing are becoming standard to manage feedstock volatility.

Our interviews with procurement directors indicate that 65% of large food brand owners plan to increase their use of coated recyclable films by 2027, with a focus on PE-based structures.

Coated Film for Food Packaging Market Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

Coated Film for Food Packaging Market REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2025
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 5.4% from 2020-2034
Segmentation
  • By Coating Type

    • Acrylic
    • PVOH
    • PVDC
    • Wax
    • Bio-based
    • Nano-coatings

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. High-barrier coatings for shelf-life extension
      • 3.1.2. Sustainability mandates for recyclable films
      • 3.1.3. Convenience-ready meal boom
      • 3.1.4. PFAS restrictions driving alternative coatings
    • 3.2. Market Trends
      • 3.2.1. Shift toward recyclable mono-material coated films
      • 3.2.2. PFAS-free coating alternatives gaining traction
      • 3.2.3. Bio-based and compostable coating growth
      • 3.2.4. Integration of coating application with film extrusion
    • 3.3. Market Restrains
      • 3.3.1. Petrochemical feedstock price volatility
      • 3.3.2. Limited supply of food-grade recycled resin
      • 3.3.3. Processing complexity and line-speed penalties
    • 3.4. Market Restraints
      • 3.4.1. Petrochemical feedstock price volatility
      • 3.4.2. Limited supply of food-grade recycled resin
      • 3.4.3. Processing complexity and line-speed penalties
    • 3.5. Market Challenges
  • By Substrate

    • PE
    • PP
    • PET
    • Bio-based
    • Paper
  • By Application

    • Meat
    • Poultry & Seafood
    • Dairy & Cheese
    • Bakery & Confectionery
    • Ready-to-Eat Meals
    • Fruits & Vegetables
    • Frozen Food
  • By Packaging Format

    • Bags & Pouches
    • Wraps
    • Lidding Films
    • Flow-pack
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • UK
      • France
      • Italy
    • Asia Pacific

      • China
      • India
      • Japan
      • Southeast Asia
    • South America

      • Brazil
      • Argentina
    • Middle East & Africa

      • South Africa
      • GCC
    • 3.5.1. Meeting food-contact compliance for new coatings
    • 3.5.2. Scaling bio-based coating production
    • 3.5.3. Managing cost premiums vs. conventional films
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Coating Type
      • 5.1.1. Acrylic
      • 5.1.2. PVOH
      • 5.1.3. PVDC
      • 5.1.4. Wax
      • 5.1.5. Bio-based
      • 5.1.6. Nano-coatings
    • 5.2. Market Analysis, Insights and Forecast - by Substrate
      • 5.2.1. PE
      • 5.2.2. PP
      • 5.2.3. PET
      • 5.2.4. Bio-based
      • 5.2.5. Paper
    • 5.3. Market Analysis, Insights and Forecast - by Application
      • 5.3.1. Meat
      • 5.3.2. Poultry & Seafood
      • 5.3.3. Dairy & Cheese
      • 5.3.4. Bakery & Confectionery
      • 5.3.5. Ready-to-Eat Meals
      • 5.3.6. Fruits & Vegetables
      • 5.3.7. Frozen Food
    • 5.4. Market Analysis, Insights and Forecast - by Packaging Format
      • 5.4.1. Bags & Pouches
      • 5.4.2. Wraps
      • 5.4.3. Lidding Films
      • 5.4.4. Flow-pack
    • 5.5. Market Analysis, Insights and Forecast - by Region
      • 5.5.1. North America
      • 5.5.2. Europe
      • 5.5.3. Asia Pacific
      • 5.5.4. South America
      • 5.5.5. Middle East & Africa
  • 6. North America Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Coating Type
      • 6.1.1. Acrylic
      • 6.1.2. PVOH
      • 6.1.3. PVDC
      • 6.1.4. Wax
      • 6.1.5. Bio-based
      • 6.1.6. Nano-coatings
    • 6.2. Market Analysis, Insights and Forecast - by Substrate
      • 6.2.1. PE
      • 6.2.2. PP
      • 6.2.3. PET
      • 6.2.4. Bio-based
      • 6.2.5. Paper
    • 6.3. Market Analysis, Insights and Forecast - by Application
      • 6.3.1. Meat
      • 6.3.2. Poultry & Seafood
      • 6.3.3. Dairy & Cheese
      • 6.3.4. Bakery & Confectionery
      • 6.3.5. Ready-to-Eat Meals
      • 6.3.6. Fruits & Vegetables
      • 6.3.7. Frozen Food
    • 6.4. Market Analysis, Insights and Forecast - by Packaging Format
      • 6.4.1. Bags & Pouches
      • 6.4.2. Wraps
      • 6.4.3. Lidding Films
      • 6.4.4. Flow-pack
  • 7. Europe Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Coating Type
      • 7.1.1. Acrylic
      • 7.1.2. PVOH
      • 7.1.3. PVDC
      • 7.1.4. Wax
      • 7.1.5. Bio-based
      • 7.1.6. Nano-coatings
    • 7.2. Market Analysis, Insights and Forecast - by Substrate
      • 7.2.1. PE
      • 7.2.2. PP
      • 7.2.3. PET
      • 7.2.4. Bio-based
      • 7.2.5. Paper
    • 7.3. Market Analysis, Insights and Forecast - by Application
      • 7.3.1. Meat
      • 7.3.2. Poultry & Seafood
      • 7.3.3. Dairy & Cheese
      • 7.3.4. Bakery & Confectionery
      • 7.3.5. Ready-to-Eat Meals
      • 7.3.6. Fruits & Vegetables
      • 7.3.7. Frozen Food
    • 7.4. Market Analysis, Insights and Forecast - by Packaging Format
      • 7.4.1. Bags & Pouches
      • 7.4.2. Wraps
      • 7.4.3. Lidding Films
      • 7.4.4. Flow-pack
  • 8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Coating Type
      • 8.1.1. Acrylic
      • 8.1.2. PVOH
      • 8.1.3. PVDC
      • 8.1.4. Wax
      • 8.1.5. Bio-based
      • 8.1.6. Nano-coatings
    • 8.2. Market Analysis, Insights and Forecast - by Substrate
      • 8.2.1. PE
      • 8.2.2. PP
      • 8.2.3. PET
      • 8.2.4. Bio-based
      • 8.2.5. Paper
    • 8.3. Market Analysis, Insights and Forecast - by Application
      • 8.3.1. Meat
      • 8.3.2. Poultry & Seafood
      • 8.3.3. Dairy & Cheese
      • 8.3.4. Bakery & Confectionery
      • 8.3.5. Ready-to-Eat Meals
      • 8.3.6. Fruits & Vegetables
      • 8.3.7. Frozen Food
    • 8.4. Market Analysis, Insights and Forecast - by Packaging Format
      • 8.4.1. Bags & Pouches
      • 8.4.2. Wraps
      • 8.4.3. Lidding Films
      • 8.4.4. Flow-pack
  • 9. South America Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Coating Type
      • 9.1.1. Acrylic
      • 9.1.2. PVOH
      • 9.1.3. PVDC
      • 9.1.4. Wax
      • 9.1.5. Bio-based
      • 9.1.6. Nano-coatings
    • 9.2. Market Analysis, Insights and Forecast - by Substrate
      • 9.2.1. PE
      • 9.2.2. PP
      • 9.2.3. PET
      • 9.2.4. Bio-based
      • 9.2.5. Paper
    • 9.3. Market Analysis, Insights and Forecast - by Application
      • 9.3.1. Meat
      • 9.3.2. Poultry & Seafood
      • 9.3.3. Dairy & Cheese
      • 9.3.4. Bakery & Confectionery
      • 9.3.5. Ready-to-Eat Meals
      • 9.3.6. Fruits & Vegetables
      • 9.3.7. Frozen Food
    • 9.4. Market Analysis, Insights and Forecast - by Packaging Format
      • 9.4.1. Bags & Pouches
      • 9.4.2. Wraps
      • 9.4.3. Lidding Films
      • 9.4.4. Flow-pack
  • 10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Coating Type
      • 10.1.1. Acrylic
      • 10.1.2. PVOH
      • 10.1.3. PVDC
      • 10.1.4. Wax
      • 10.1.5. Bio-based
      • 10.1.6. Nano-coatings
    • 10.2. Market Analysis, Insights and Forecast - by Substrate
      • 10.2.1. PE
      • 10.2.2. PP
      • 10.2.3. PET
      • 10.2.4. Bio-based
      • 10.2.5. Paper
    • 10.3. Market Analysis, Insights and Forecast - by Application
      • 10.3.1. Meat
      • 10.3.2. Poultry & Seafood
      • 10.3.3. Dairy & Cheese
      • 10.3.4. Bakery & Confectionery
      • 10.3.5. Ready-to-Eat Meals
      • 10.3.6. Fruits & Vegetables
      • 10.3.7. Frozen Food
    • 10.4. Market Analysis, Insights and Forecast - by Packaging Format
      • 10.4.1. Bags & Pouches
      • 10.4.2. Wraps
      • 10.4.3. Lidding Films
      • 10.4.4. Flow-pack
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. Amcor plc
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. Mondi Group
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Sealed Air Corporation
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Constantia Flexibles Group GmbH
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Coveris Management GmbH
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. Futamura Chemical Co. Ltd.
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Taghleef Industries
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. Klöckner Pentaplast
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. Cosmo Films
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. Toray Industries
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Jindal Poly Films
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Uflex Ltd.
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global Coated Film for Food Packaging Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: Global Coated Film for Food Packaging Market Volume Breakdown (Kilotons, %) by Region 2026 & 2034
    3. Figure 3: North America Coated Film for Food Packaging Market Revenue (Billion), by Coating Type 2026 & 2034
    4. Figure 4: North America Coated Film for Food Packaging Market Volume (Kilotons), by Coating Type 2026 & 2034
    5. Figure 5: North America Coated Film for Food Packaging Market Revenue Share (%), by Coating Type 2026 & 2034
    6. Figure 6: North America Coated Film for Food Packaging Market Volume Share (%), by Coating Type 2026 & 2034
    7. Figure 7: North America Coated Film for Food Packaging Market Revenue (Billion), by Substrate 2026 & 2034
    8. Figure 8: North America Coated Film for Food Packaging Market Volume (Kilotons), by Substrate 2026 & 2034
    9. Figure 9: North America Coated Film for Food Packaging Market Revenue Share (%), by Substrate 2026 & 2034
    10. Figure 10: North America Coated Film for Food Packaging Market Volume Share (%), by Substrate 2026 & 2034
    11. Figure 11: North America Coated Film for Food Packaging Market Revenue (Billion), by Application 2026 & 2034
    12. Figure 12: North America Coated Film for Food Packaging Market Volume (Kilotons), by Application 2026 & 2034
    13. Figure 13: North America Coated Film for Food Packaging Market Revenue Share (%), by Application 2026 & 2034
    14. Figure 14: North America Coated Film for Food Packaging Market Volume Share (%), by Application 2026 & 2034
    15. Figure 15: North America Coated Film for Food Packaging Market Revenue (Billion), by Packaging Format 2026 & 2034
    16. Figure 16: North America Coated Film for Food Packaging Market Volume (Kilotons), by Packaging Format 2026 & 2034
    17. Figure 17: North America Coated Film for Food Packaging Market Revenue Share (%), by Packaging Format 2026 & 2034
    18. Figure 18: North America Coated Film for Food Packaging Market Volume Share (%), by Packaging Format 2026 & 2034
    19. Figure 19: North America Coated Film for Food Packaging Market Revenue (Billion), by Country 2026 & 2034
    20. Figure 20: North America Coated Film for Food Packaging Market Volume (Kilotons), by Country 2026 & 2034
    21. Figure 21: North America Coated Film for Food Packaging Market Revenue Share (%), by Country 2026 & 2034
    22. Figure 22: North America Coated Film for Food Packaging Market Volume Share (%), by Country 2026 & 2034
    23. Figure 23: Europe Coated Film for Food Packaging Market Revenue (Billion), by Coating Type 2026 & 2034
    24. Figure 24: Europe Coated Film for Food Packaging Market Volume (Kilotons), by Coating Type 2026 & 2034
    25. Figure 25: Europe Coated Film for Food Packaging Market Revenue Share (%), by Coating Type 2026 & 2034
    26. Figure 26: Europe Coated Film for Food Packaging Market Volume Share (%), by Coating Type 2026 & 2034
    27. Figure 27: Europe Coated Film for Food Packaging Market Revenue (Billion), by Substrate 2026 & 2034
    28. Figure 28: Europe Coated Film for Food Packaging Market Volume (Kilotons), by Substrate 2026 & 2034
    29. Figure 29: Europe Coated Film for Food Packaging Market Revenue Share (%), by Substrate 2026 & 2034
    30. Figure 30: Europe Coated Film for Food Packaging Market Volume Share (%), by Substrate 2026 & 2034
    31. Figure 31: Europe Coated Film for Food Packaging Market Revenue (Billion), by Application 2026 & 2034
    32. Figure 32: Europe Coated Film for Food Packaging Market Volume (Kilotons), by Application 2026 & 2034
    33. Figure 33: Europe Coated Film for Food Packaging Market Revenue Share (%), by Application 2026 & 2034
    34. Figure 34: Europe Coated Film for Food Packaging Market Volume Share (%), by Application 2026 & 2034
    35. Figure 35: Europe Coated Film for Food Packaging Market Revenue (Billion), by Packaging Format 2026 & 2034
    36. Figure 36: Europe Coated Film for Food Packaging Market Volume (Kilotons), by Packaging Format 2026 & 2034
    37. Figure 37: Europe Coated Film for Food Packaging Market Revenue Share (%), by Packaging Format 2026 & 2034
    38. Figure 38: Europe Coated Film for Food Packaging Market Volume Share (%), by Packaging Format 2026 & 2034
    39. Figure 39: Europe Coated Film for Food Packaging Market Revenue (Billion), by Country 2026 & 2034
    40. Figure 40: Europe Coated Film for Food Packaging Market Volume (Kilotons), by Country 2026 & 2034
    41. Figure 41: Europe Coated Film for Food Packaging Market Revenue Share (%), by Country 2026 & 2034
    42. Figure 42: Europe Coated Film for Food Packaging Market Volume Share (%), by Country 2026 & 2034
    43. Figure 43: Asia Pacific Coated Film for Food Packaging Market Revenue (Billion), by Coating Type 2026 & 2034
    44. Figure 44: Asia Pacific Coated Film for Food Packaging Market Volume (Kilotons), by Coating Type 2026 & 2034
    45. Figure 45: Asia Pacific Coated Film for Food Packaging Market Revenue Share (%), by Coating Type 2026 & 2034
    46. Figure 46: Asia Pacific Coated Film for Food Packaging Market Volume Share (%), by Coating Type 2026 & 2034
    47. Figure 47: Asia Pacific Coated Film for Food Packaging Market Revenue (Billion), by Substrate 2026 & 2034
    48. Figure 48: Asia Pacific Coated Film for Food Packaging Market Volume (Kilotons), by Substrate 2026 & 2034
    49. Figure 49: Asia Pacific Coated Film for Food Packaging Market Revenue Share (%), by Substrate 2026 & 2034
    50. Figure 50: Asia Pacific Coated Film for Food Packaging Market Volume Share (%), by Substrate 2026 & 2034
    51. Figure 51: Asia Pacific Coated Film for Food Packaging Market Revenue (Billion), by Application 2026 & 2034
    52. Figure 52: Asia Pacific Coated Film for Food Packaging Market Volume (Kilotons), by Application 2026 & 2034
    53. Figure 53: Asia Pacific Coated Film for Food Packaging Market Revenue Share (%), by Application 2026 & 2034
    54. Figure 54: Asia Pacific Coated Film for Food Packaging Market Volume Share (%), by Application 2026 & 2034
    55. Figure 55: Asia Pacific Coated Film for Food Packaging Market Revenue (Billion), by Packaging Format 2026 & 2034
    56. Figure 56: Asia Pacific Coated Film for Food Packaging Market Volume (Kilotons), by Packaging Format 2026 & 2034
    57. Figure 57: Asia Pacific Coated Film for Food Packaging Market Revenue Share (%), by Packaging Format 2026 & 2034
    58. Figure 58: Asia Pacific Coated Film for Food Packaging Market Volume Share (%), by Packaging Format 2026 & 2034
    59. Figure 59: Asia Pacific Coated Film for Food Packaging Market Revenue (Billion), by Country 2026 & 2034
    60. Figure 60: Asia Pacific Coated Film for Food Packaging Market Volume (Kilotons), by Country 2026 & 2034
    61. Figure 61: Asia Pacific Coated Film for Food Packaging Market Revenue Share (%), by Country 2026 & 2034
    62. Figure 62: Asia Pacific Coated Film for Food Packaging Market Volume Share (%), by Country 2026 & 2034
    63. Figure 63: South America Coated Film for Food Packaging Market Revenue (Billion), by Coating Type 2026 & 2034
    64. Figure 64: South America Coated Film for Food Packaging Market Volume (Kilotons), by Coating Type 2026 & 2034
    65. Figure 65: South America Coated Film for Food Packaging Market Revenue Share (%), by Coating Type 2026 & 2034
    66. Figure 66: South America Coated Film for Food Packaging Market Volume Share (%), by Coating Type 2026 & 2034
    67. Figure 67: South America Coated Film for Food Packaging Market Revenue (Billion), by Substrate 2026 & 2034
    68. Figure 68: South America Coated Film for Food Packaging Market Volume (Kilotons), by Substrate 2026 & 2034
    69. Figure 69: South America Coated Film for Food Packaging Market Revenue Share (%), by Substrate 2026 & 2034
    70. Figure 70: South America Coated Film for Food Packaging Market Volume Share (%), by Substrate 2026 & 2034
    71. Figure 71: South America Coated Film for Food Packaging Market Revenue (Billion), by Application 2026 & 2034
    72. Figure 72: South America Coated Film for Food Packaging Market Volume (Kilotons), by Application 2026 & 2034
    73. Figure 73: South America Coated Film for Food Packaging Market Revenue Share (%), by Application 2026 & 2034
    74. Figure 74: South America Coated Film for Food Packaging Market Volume Share (%), by Application 2026 & 2034
    75. Figure 75: South America Coated Film for Food Packaging Market Revenue (Billion), by Packaging Format 2026 & 2034
    76. Figure 76: South America Coated Film for Food Packaging Market Volume (Kilotons), by Packaging Format 2026 & 2034
    77. Figure 77: South America Coated Film for Food Packaging Market Revenue Share (%), by Packaging Format 2026 & 2034
    78. Figure 78: South America Coated Film for Food Packaging Market Volume Share (%), by Packaging Format 2026 & 2034
    79. Figure 79: South America Coated Film for Food Packaging Market Revenue (Billion), by Country 2026 & 2034
    80. Figure 80: South America Coated Film for Food Packaging Market Volume (Kilotons), by Country 2026 & 2034
    81. Figure 81: South America Coated Film for Food Packaging Market Revenue Share (%), by Country 2026 & 2034
    82. Figure 82: South America Coated Film for Food Packaging Market Volume Share (%), by Country 2026 & 2034
    83. Figure 83: Middle East & Africa Coated Film for Food Packaging Market Revenue (Billion), by Coating Type 2026 & 2034
    84. Figure 84: Middle East & Africa Coated Film for Food Packaging Market Volume (Kilotons), by Coating Type 2026 & 2034
    85. Figure 85: Middle East & Africa Coated Film for Food Packaging Market Revenue Share (%), by Coating Type 2026 & 2034
    86. Figure 86: Middle East & Africa Coated Film for Food Packaging Market Volume Share (%), by Coating Type 2026 & 2034
    87. Figure 87: Middle East & Africa Coated Film for Food Packaging Market Revenue (Billion), by Substrate 2026 & 2034
    88. Figure 88: Middle East & Africa Coated Film for Food Packaging Market Volume (Kilotons), by Substrate 2026 & 2034
    89. Figure 89: Middle East & Africa Coated Film for Food Packaging Market Revenue Share (%), by Substrate 2026 & 2034
    90. Figure 90: Middle East & Africa Coated Film for Food Packaging Market Volume Share (%), by Substrate 2026 & 2034
    91. Figure 91: Middle East & Africa Coated Film for Food Packaging Market Revenue (Billion), by Application 2026 & 2034
    92. Figure 92: Middle East & Africa Coated Film for Food Packaging Market Volume (Kilotons), by Application 2026 & 2034
    93. Figure 93: Middle East & Africa Coated Film for Food Packaging Market Revenue Share (%), by Application 2026 & 2034
    94. Figure 94: Middle East & Africa Coated Film for Food Packaging Market Volume Share (%), by Application 2026 & 2034
    95. Figure 95: Middle East & Africa Coated Film for Food Packaging Market Revenue (Billion), by Packaging Format 2026 & 2034
    96. Figure 96: Middle East & Africa Coated Film for Food Packaging Market Volume (Kilotons), by Packaging Format 2026 & 2034
    97. Figure 97: Middle East & Africa Coated Film for Food Packaging Market Revenue Share (%), by Packaging Format 2026 & 2034
    98. Figure 98: Middle East & Africa Coated Film for Food Packaging Market Volume Share (%), by Packaging Format 2026 & 2034
    99. Figure 99: Middle East & Africa Coated Film for Food Packaging Market Revenue (Billion), by Country 2026 & 2034
    100. Figure 100: Middle East & Africa Coated Film for Food Packaging Market Volume (Kilotons), by Country 2026 & 2034
    101. Figure 101: Middle East & Africa Coated Film for Food Packaging Market Revenue Share (%), by Country 2026 & 2034
    102. Figure 102: Middle East & Africa Coated Film for Food Packaging Market Volume Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global Coated Film for Food Packaging Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    2. Table 2: Global Coated Film for Food Packaging Market Volume Kilotons Forecast, by Coating Type 2020 & 2034
    3. Table 3: Global Coated Film for Food Packaging Market Revenue Billion Forecast, by Substrate 2020 & 2034
    4. Table 4: Global Coated Film for Food Packaging Market Volume Kilotons Forecast, by Substrate 2020 & 2034
    5. Table 5: Global Coated Film for Food Packaging Market Revenue Billion Forecast, by Application 2020 & 2034
    6. Table 6: Global Coated Film for Food Packaging Market Volume Kilotons Forecast, by Application 2020 & 2034
    7. Table 7: Global Coated Film for Food Packaging Market Revenue Billion Forecast, by Packaging Format 2020 & 2034
    8. Table 8: Global Coated Film for Food Packaging Market Volume Kilotons Forecast, by Packaging Format 2020 & 2034
    9. Table 9: Global Coated Film for Food Packaging Market Revenue Billion Forecast, by Region 2020 & 2034
    10. Table 10: Global Coated Film for Food Packaging Market Volume Kilotons Forecast, by Region 2020 & 2034
    11. Table 11: North America Coated Film for Food Packaging Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    12. Table 12: North America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Coating Type 2020 & 2034
    13. Table 13: North America Coated Film for Food Packaging Market Revenue Billion Forecast, by Substrate 2020 & 2034
    14. Table 14: North America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Substrate 2020 & 2034
    15. Table 15: North America Coated Film for Food Packaging Market Revenue Billion Forecast, by Application 2020 & 2034
    16. Table 16: North America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Application 2020 & 2034
    17. Table 17: North America Coated Film for Food Packaging Market Revenue Billion Forecast, by Packaging Format 2020 & 2034
    18. Table 18: North America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Packaging Format 2020 & 2034
    19. Table 19: North America Coated Film for Food Packaging Market Revenue Billion Forecast, by Country 2020 & 2034
    20. Table 20: North America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Country 2020 & 2034
    21. Table 21: USA Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    22. Table 22: USA Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    23. Table 23: Canada Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: Canada Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    25. Table 25: Mexico Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    26. Table 26: Mexico Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    27. Table 27: Europe Coated Film for Food Packaging Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    28. Table 28: Europe Coated Film for Food Packaging Market Volume Kilotons Forecast, by Coating Type 2020 & 2034
    29. Table 29: Europe Coated Film for Food Packaging Market Revenue Billion Forecast, by Substrate 2020 & 2034
    30. Table 30: Europe Coated Film for Food Packaging Market Volume Kilotons Forecast, by Substrate 2020 & 2034
    31. Table 31: Europe Coated Film for Food Packaging Market Revenue Billion Forecast, by Application 2020 & 2034
    32. Table 32: Europe Coated Film for Food Packaging Market Volume Kilotons Forecast, by Application 2020 & 2034
    33. Table 33: Europe Coated Film for Food Packaging Market Revenue Billion Forecast, by Packaging Format 2020 & 2034
    34. Table 34: Europe Coated Film for Food Packaging Market Volume Kilotons Forecast, by Packaging Format 2020 & 2034
    35. Table 35: Europe Coated Film for Food Packaging Market Revenue Billion Forecast, by Country 2020 & 2034
    36. Table 36: Europe Coated Film for Food Packaging Market Volume Kilotons Forecast, by Country 2020 & 2034
    37. Table 37: Germany Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    38. Table 38: Germany Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    39. Table 39: UK Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    40. Table 40: UK Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    41. Table 41: France Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    42. Table 42: France Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    43. Table 43: Italy Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    44. Table 44: Italy Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    45. Table 45: Asia Pacific Coated Film for Food Packaging Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    46. Table 46: Asia Pacific Coated Film for Food Packaging Market Volume Kilotons Forecast, by Coating Type 2020 & 2034
    47. Table 47: Asia Pacific Coated Film for Food Packaging Market Revenue Billion Forecast, by Substrate 2020 & 2034
    48. Table 48: Asia Pacific Coated Film for Food Packaging Market Volume Kilotons Forecast, by Substrate 2020 & 2034
    49. Table 49: Asia Pacific Coated Film for Food Packaging Market Revenue Billion Forecast, by Application 2020 & 2034
    50. Table 50: Asia Pacific Coated Film for Food Packaging Market Volume Kilotons Forecast, by Application 2020 & 2034
    51. Table 51: Asia Pacific Coated Film for Food Packaging Market Revenue Billion Forecast, by Packaging Format 2020 & 2034
    52. Table 52: Asia Pacific Coated Film for Food Packaging Market Volume Kilotons Forecast, by Packaging Format 2020 & 2034
    53. Table 53: Asia Pacific Coated Film for Food Packaging Market Revenue Billion Forecast, by Country 2020 & 2034
    54. Table 54: Asia Pacific Coated Film for Food Packaging Market Volume Kilotons Forecast, by Country 2020 & 2034
    55. Table 55: China Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    56. Table 56: China Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    57. Table 57: India Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    58. Table 58: India Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    59. Table 59: Japan Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    60. Table 60: Japan Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    61. Table 61: Southeast Asia Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    62. Table 62: Southeast Asia Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    63. Table 63: South America Coated Film for Food Packaging Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    64. Table 64: South America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Coating Type 2020 & 2034
    65. Table 65: South America Coated Film for Food Packaging Market Revenue Billion Forecast, by Substrate 2020 & 2034
    66. Table 66: South America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Substrate 2020 & 2034
    67. Table 67: South America Coated Film for Food Packaging Market Revenue Billion Forecast, by Application 2020 & 2034
    68. Table 68: South America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Application 2020 & 2034
    69. Table 69: South America Coated Film for Food Packaging Market Revenue Billion Forecast, by Packaging Format 2020 & 2034
    70. Table 70: South America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Packaging Format 2020 & 2034
    71. Table 71: South America Coated Film for Food Packaging Market Revenue Billion Forecast, by Country 2020 & 2034
    72. Table 72: South America Coated Film for Food Packaging Market Volume Kilotons Forecast, by Country 2020 & 2034
    73. Table 73: Brazil Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    74. Table 74: Brazil Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    75. Table 75: Argentina Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    76. Table 76: Argentina Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    77. Table 77: Middle East & Africa Coated Film for Food Packaging Market Revenue Billion Forecast, by Coating Type 2020 & 2034
    78. Table 78: Middle East & Africa Coated Film for Food Packaging Market Volume Kilotons Forecast, by Coating Type 2020 & 2034
    79. Table 79: Middle East & Africa Coated Film for Food Packaging Market Revenue Billion Forecast, by Substrate 2020 & 2034
    80. Table 80: Middle East & Africa Coated Film for Food Packaging Market Volume Kilotons Forecast, by Substrate 2020 & 2034
    81. Table 81: Middle East & Africa Coated Film for Food Packaging Market Revenue Billion Forecast, by Application 2020 & 2034
    82. Table 82: Middle East & Africa Coated Film for Food Packaging Market Volume Kilotons Forecast, by Application 2020 & 2034
    83. Table 83: Middle East & Africa Coated Film for Food Packaging Market Revenue Billion Forecast, by Packaging Format 2020 & 2034
    84. Table 84: Middle East & Africa Coated Film for Food Packaging Market Volume Kilotons Forecast, by Packaging Format 2020 & 2034
    85. Table 85: Middle East & Africa Coated Film for Food Packaging Market Revenue Billion Forecast, by Country 2020 & 2034
    86. Table 86: Middle East & Africa Coated Film for Food Packaging Market Volume Kilotons Forecast, by Country 2020 & 2034
    87. Table 87: South Africa Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    88. Table 88: South Africa Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034
    89. Table 89: GCC Coated Film for Food Packaging Market Revenue (Billion) Forecast, by Application 2020 & 2034
    90. Table 90: GCC Coated Film for Food Packaging Market Volume (Kilotons) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the market size of coated film for food packaging in 2025?

    The global coated film for food packaging market is estimated at USD 9.8 billion in 2025, with a projected CAGR of 5.4% through 2035, reaching USD 16.6 billion.

    2Which region dominates the coated film for food packaging market?

    Asia-Pacific leads with a 39% revenue share in 2025, driven by large food-processing bases in China and India, followed by North America and Europe.

    3What are the key drivers for coated film demand?

    High-barrier coatings for shelf-life extension, sustainability mandates for recyclable mono-material films, and PFAS restrictions are the primary growth drivers.

    4Who are the leading companies in coated film for food packaging?

    Major players include Amcor, Mondi Group, Sealed Air, Constantia Flexibles, Coveris, Futamura Chemical, and Taghleef Industries.

    5What is the fastest-growing coating type?

    Bio-based and compostable coatings are growing at 8.1% CAGR, driven by regulatory support in Europe and brand sustainability commitments.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Conducted 320+ in-depth interviews with executives across the coated film value chain, including film converters, coating formulators, resin suppliers, and brand-owner packaging engineers.
    • Interviewed stakeholders such as Packaging Development Directors, Procurement Managers, Sustainability Leads, and R&D Scientists to capture demand-side requirements and qualification criteria.
    • Primary research accounted for 75% of total research effort, ensuring granular, first-hand insights into coating technology adoption and pricing dynamics.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Packaging Development Director35%
    Procurement Manager30%
    R&D Scientist20%
    Sustainability Lead15%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Film Converters40%
    Coating Formulators25%
    Resin Suppliers20%
    Brand Owners15%

    Secondary Research & Industry Benchmarking

    • Analyzed 20% secondary data from official multilateral sources including UN Comtrade, Eurostat, US ITC, and OECD trade databases for import/export volumes and pricing trends.
    • Benchmarked against recognized industry associations such as the Flexible Packaging Association (FPA), European Organization for Packaging and the Environment (EUROPEN), and the Sustainable Packaging Coalition (SPC).
    • Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook were used for company-level financial analysis and M&A tracking.

    Demand Modeling & Market Estimation

    • Built a bottom-up market model using quantitative metrics: coated film consumption per application (kg per tonne of food produced), average selling price per kilogram by coating type, and food production volumes by region.
    • Cross-validated with a top-down approach using global food packaging films market size and coating penetration rates.
    • Multi-level data triangulation reconciled supply-side (film producer revenues) and demand-side (brand-owner procurement volumes) estimates.

    Data Accuracy & Quality Check

    • All market estimates were validated through a three-tier quality check: primary interview cross-verification, secondary data consistency checks, and expert panel review.
    • Guaranteed data accuracy level of 85–90%, with sensitivity analysis on key variables such as feedstock prices and regulatory timelines.
    • Every report is updated to the date of purchase, incorporating the latest regulatory changes and market developments.