1What is the current size of the global tea industry market?
The global tea industry market was valued at USD 69.5 billion in 2025 and is estimated to reach USD 74.0 billion in 2026, according to our proprietary research.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Tea Industry
 by Product (Black, Green, Oolong, Herbal, Others), by Form (CTC Tea, Leaf Tea), by Category (Conventional, Organic), by Flavoring (Unflavored, Flavored), by Packaging (Box, Pouch, Others), by Distribution Channel (Supermarkets & Hypermarkets, Convenience Stores, Grocery Stores, Online, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, India, Japan, Australia, South Korea), by Central & South America (Brazil), by Middle East & Africa (UAE) Forecast 2026-2034

Research Associate


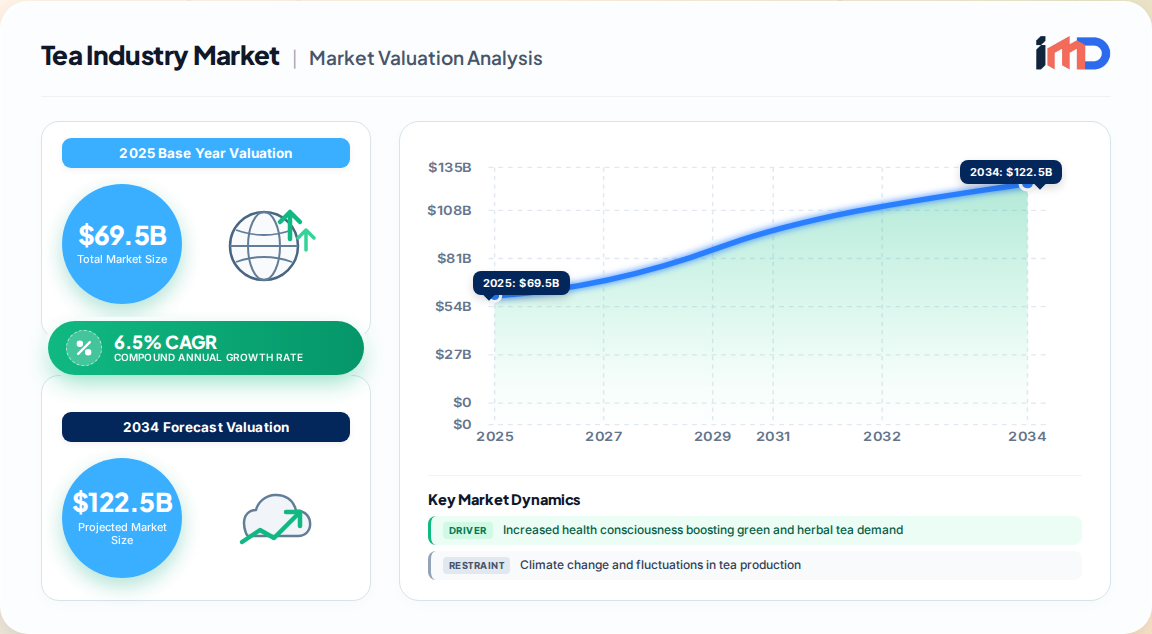
Our proprietary primary research and expert interview program places the global tea industry market at USD 69.5 billion in 2025, with a forecast expansion to USD 74.0 billion in 2026 and USD 115.2 billion by 2033, representing a 6.5% CAGR across the 2026–2033 evaluation window. This trajectory positions tea as one of the most resilient and rapidly diversifying segments within the broader non-alcoholic beverage landscape.
Asia Pacific commands a dominant 67.9% revenue share, anchored by India's position as the largest single-country market and China's unparalleled production and consumption ecosystem. Meanwhile, the Middle East & Africa region is identified as the fastest-growing geography, driven by urbanization, a young demographic dividend, and rising disposable incomes.
Our bottom-up demand modeling indicates that the shift toward functional beverages—those delivering health benefits beyond basic nutrition—is the single most consequential structural force reshaping the market. Consumers increasingly seek teas that aid detoxification, boost energy, support weight management, and address specific wellness needs.
The expansion of ready-to-drink (RTD) tea products and online retail channels constitutes the primary growth engine. Consumers gravitate toward convenient, healthy, on-the-go formats, propelling demand for bottled, canned, and packaged RTD teas. E-commerce and quick-commerce platforms have democratized access to premium, single-origin, and specialty teas, enabling brands to bypass traditional retail gatekeepers and reach niche audiences directly.
Global tea trade flows are concentrated among a handful of producing nations, with China, India, Kenya, and Sri Lanka serving as the dominant exporters. Our supply chain intelligence reveals that Kenya remains a critical source for CTC (crush/tear/curl) teas, particularly for the European and Middle Eastern markets, while China and India dominate leaf tea and specialty segments.
The supply side is undergoing a structural shift toward sustainable and ethically sourced products. Certification schemes (Fairtrade, Rainforest Alliance, organic) are becoming commercially meaningful as retailers convert own-brand ranges to certified supply, giving participating producers access to established selling channels. Suppliers that secure placement in certified retail ranges gain a durable commercial advantage.
| Product Segment | Market Share (2025/2026) | Growth Outlook |
|---|---|---|
| Black Tea | 53.3% (2025) / 41.32% (2026) | Steady; largest revenue contributor |
| Green Tea | Significant and growing | Health-driven demand; matcha and specialty varieties gaining traction |
| Herbal & Fruit Infusions | Smaller base | Fastest-growing at 7.25% CAGR (2027–2032) |
| Oolong | Niche | Premium and specialty positioning |
The largest regional market, accounting for 67.9% revenue share in 2025. India holds the largest country-level market share, while China, Japan, and Southeast Asian nations contribute significantly. Cultural tea rituals, favorable climatic conditions, and a vast domestic consumer base underpin regional dominance.
The U.S. market generated USD 3.39 billion in 2025 and is projected to reach USD 5.37 billion by 2033, growing at a 5.9% CAGR. Black tea is the largest product segment (84.75% share), while herbal tea is the fastest-growing. Functional and RTD formats are gaining traction among health-conscious consumers and Gen Z.
Driven by health consciousness and sustainability preferences. Fairtrade tea sales volume in the UK rose 35% in 2025 versus 2024, with 41% of adults aged 16+ actively choosing Fairtrade tea. Germany and the UK are key markets for green, herbal, and specialty teas.
The fastest-growing region, forecast at an 8.2% CAGR (2027–2032). Urbanization, a young population, and rising disposable incomes are driving increased tea consumption, particularly in the Middle East and Sub-Saharan Africa.
A smaller but growing market, with Brazil and Mexico showing increasing demand for premium and functional tea products. Mexico is the fastest-growing market in North America, projected to reach USD 153.7 million by 2033.
The market is characterized by medium concentration, with major players including Unilever (Lipton), Associated British Foods (Twinings), Tata Consumer Products (Tetley), PepsiCo, ITO EN, and Starbucks. Recent strategic developments include:
The tea value chain spans cultivation, processing, blending, packaging, distribution, and retail. Key value-adding stages include:
Our opportunity assessment identifies several high-potential white spaces:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.5% from 2020-2034 |
| Segmentation |
|
By Category
By Flavoring
By Packaging
By Distribution Channel
| By Geography |
|
The global tea industry market was valued at USD 69.5 billion in 2025 and is estimated to reach USD 74.0 billion in 2026, according to our proprietary research.
The market is projected to grow at a CAGR of 6.5% from 2026 to 2033, reaching USD 115.2 billion by 2033.
Asia Pacific dominates the market, accounting for 67.9% of global revenue in 2025, driven by India and China.
Key drivers include the expansion of ready-to-drink (RTD) tea products, growth of online retail channels, rising health consciousness, and demand for functional and sustainable teas.
Black tea is the largest product segment, holding a 53.3% market share in 2025, while herbal and fruit infusions are the fastest-growing at a 7.25% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Head of Product Innovation | 25% |
| Supply Chain Manager | 25% |
| Category Buyer | 20% |
| Company Type | Representation (%) |
|---|---|
| Tea Producers and Plantations | 30% |
| RTD Beverage Manufacturers | 25% |
| Brand Owners and Marketers | 20% |
| Distributors and Retailers | 15% |
| Packaging and Equipment Suppliers | 10% |
 Related Reports
