1What is the PCB Rework and Repair Service market size in 2025?
The market is valued at USD 1,974.7 Million in 2025 and is projected to reach USD 3,500 Million by 2035, growing at a 5.9% CAGR.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 PCB Rework and Repair Service
 by Service Type (Rework Services, Repair Services, Inspection Services, Testing Services), by Application (Consumer Electronics, Automotive Electronics, Industrial Electronics, Medical Electronics), by End User (Original Equipment Manufacturers, Contract Manufacturers, Aftermarket Service Providers), by Technology (Automatic Repair, Manual Repair, Hybrid Repair), by Rework Type (Component Replacement, Resoldering Services, Cleaning Services, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Rest of Europe), by Asia Pacific (China, Japan, South Korea, India, Southeast Asia, Australia, Rest of Asia Pacific), by South America (Brazil, Rest of South America), by Middle East & Africa (GCC, South Africa, Rest of Middle East & Africa) Forecast 2026-2034

Senior Analyst


 Related Reports

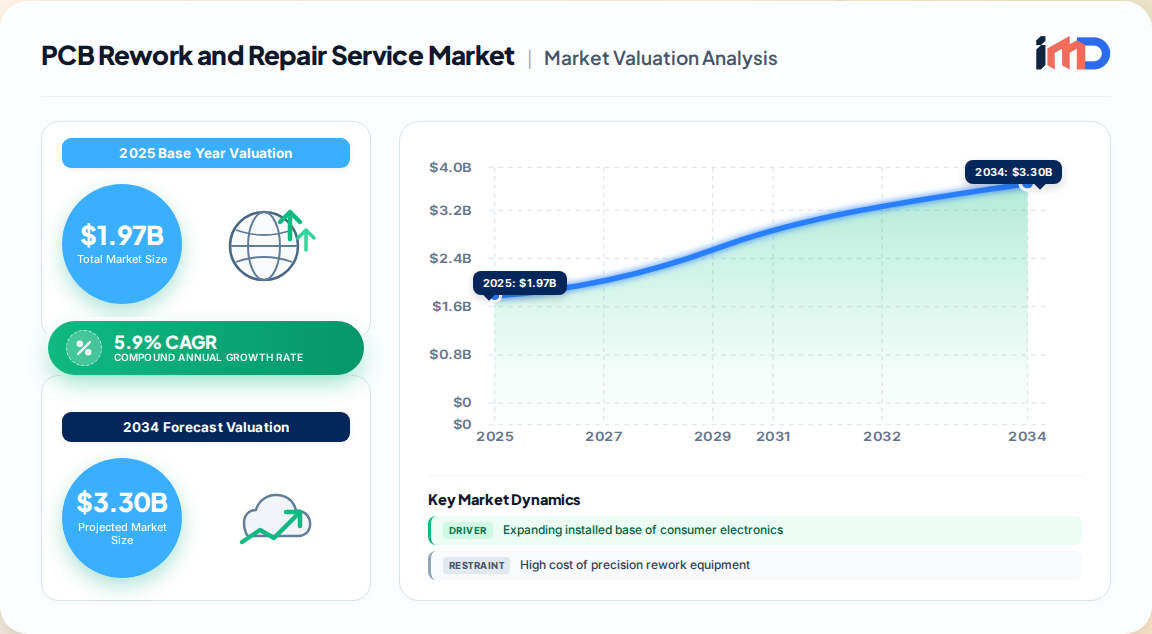
The global PCB Rework and Repair Service market represents a critical aftermarket and production-support ecosystem for the electronics value chain. Our proprietary primary research places the market at USD 1,974.7 Million in 2025, advancing from USD 1,864.7 Million in 2024, with a projected valuation of USD 3,500 Million by 2035 at a 5.9% CAGR over 2026–2035. This growth is structurally anchored in the installed base of electronic devices, the rising complexity of printed circuit board assemblies, and the globalization of repair networks.
The service domain spans component-level replacement, precision resoldering, cleaning, inspection, and functional testing. Demand is increasingly pulled by high-density interconnect (HDI) and micro-via boards deployed across consumer electronics, automotive electronics, industrial controls, and medical devices. Our expert interviews indicate that nearshoring of electronics manufacturing and tightening repair-rights legislation are unlocking new service volume, particularly in North America and Europe.
Drivers are robust and multi-layered. The consumer electronics installed base continues to expand, and out-of-warranty failures create a durable service pool. Automotive electronics complexity — driven by ADAS, infotainment, and electrification — is pushing OEMs toward specialized rework partnerships. Sustainability mandates and right-to-repair statutes (e.g., EU repairability requirements effective June 2025, and multiple US state laws) are formally expanding access to repair services. Finally, automation and AI-assisted diagnostics are improving first-pass yield and reducing turnaround time.
Restraints include the high cost of precision rework equipment, a persistent shortage of certified technicians, and the risk of collateral damage to increasingly miniaturized boards. Sealed wearable designs and proprietary parts programs continue to limit independent service access. Additionally, OEM warranty policies can suppress out-of-warranty service volumes in the early years of device lifecycles.
The value chain is structured around four nodes: component and consumable suppliers (solder, flux, nozzles, thermal profiles), equipment providers (rework stations, X-ray inspection, AOI), service providers (OEM in-house, contract manufacturers, independent repair shops), and end users (consumer, automotive, industrial, medical). Our channel checks reveal that OEMs are increasingly embedding rework cells directly into production lines, compressing the addressable market for standalone service providers while elevating the importance of hybrid service models.
By service type, rework services account for the largest revenue share, followed by repair, inspection, and testing. By application, consumer electronics leads, with automotive electronics the fastest-growing vertical at an estimated incremental CAGR of 6.4% to 6.8%. Industrial and medical electronics are stable, regulation-driven segments with high margin profiles.
| Segment | 2025 Share (est.) | Growth Outlook |
|---|---|---|
| Consumer Electronics | 38% | Steady, replacement-cycle driven |
| Automotive Electronics | 24% | Fastest, ADAS and EV boards |
| Industrial Electronics | 21% | Stable, high-mix low-volume |
| Medical Electronics | 17% | Premium, compliance-intensive |
By end user, original equipment manufacturers hold a dominant share, while aftermarket service providers represent the fastest-growing channel. By technology, manual repair still dominates volume, but automatic and hybrid repair platforms are gaining share due to yield and repeatability advantages.
Asia-Pacific is the largest and fastest-growing region, underpinned by China's electronics manufacturing ecosystem and India's rising repair demand (22,864 phone and tablet repair complaints in 2024–25, up from 19,057 in 2022–23). North America holds a significant share, supported by advanced electronics OEMs and right-to-repair legislation in ten states as of October 2026. Europe is shaped by EU repairability rules and dual-use export controls, which add compliance layers for high-end board repair. South America and the Middle East & Africa remain emerging markets with slower but steady adoption.
The competitive landscape is moderately fragmented, with equipment vendors and service specialists converging. Key players include Metcal, Hakko, Weller, Nordson, Pace Technologies, Scienscope, SolderStar, BEST Inc., PSI Repair Services, Circuit Technology Center, Circuit Board Medics, and Precision PCB Services. Strategic moves are centered on automation integration (e.g., Nordson's acquisition of SolderStar in June 2024), partnerships combining soldering platforms with X-ray inspection (Metcal and Scienscope, September 2024), and micro-rework station launches (Hakko MiniPro X1, February 2025). Providers that combine certified technicians, deep spare-parts inventory, and digital booking platforms are best positioned to capture out-of-warranty demand.
Rework equipment and consumables are globally traded, with export control regimes adding complexity. The EU dual-use export control framework (Regulation 2021/821) governs certain high-precision soldering and inspection systems, while EU General Export Authorisations exist for "export after repair/replacement," streamlining cross-border service flows. Suppliers in Asia-Pacific dominate consumable volumes, while North American and European equipment vendors lead in precision systems. Tariff exposure and lead times for specialty nozzles and thermal profiling tools represent a measurable supply chain risk for independent service providers.
Three high-potential white spaces emerge from our analysis. First, certified third-party repair networks targeting smartphones, laptops, and appliances are poised to gain share as parts portals mature. Second, automotive-grade rework services for high-reliability boards represent a premium, underpenetrated segment. Third, sustainability-linked repair offerings — including eco-friendly cleaning and component reuse — can command pricing premiums and align with corporate ESG mandates. Providers investing in AI-based failure analysis and predictive diagnostics will capture disproportionate value across all three spaces.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.9% from 2020-2034 |
| Segmentation |
|
By End User
By Technology
By Rework Type
| By Geography |
|
The market is valued at USD 1,974.7 Million in 2025 and is projected to reach USD 3,500 Million by 2035, growing at a 5.9% CAGR.
Asia-Pacific holds the largest share at approximately 43%, driven by China's manufacturing base and India's rising repair demand, followed by North America at 27%.
Key players include Metcal, Hakko, Weller, Nordson, Pace Technologies, Scienscope, SolderStar, BEST Inc., PSI Repair Services, and Circuit Technology Center.
Major trends include automation and AI-assisted repair, growth in HDI board rework, right-to-repair legislation, and strategic M&A such as Nordson's acquisition of SolderStar in June 2024.
Growth is driven by the expanding installed base of consumer and automotive electronics, sustainability mandates, and the rising complexity of PCB assemblies requiring specialized repair.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Service Operations | 30% |
| Director of Electronics Manufacturing | 25% |
| Repair Center Manager | 25% |
| Procurement Head | 20% |
| Company Type | Representation (%) |
|---|---|
| Equipment OEMs | 30% |
| Independent Repair Shops | 25% |
| Contract Manufacturers | 20% |
| OEM In-house Service Units | 15% |
| Component/Consumable Suppliers | 10% |