Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Ornamental Horticulture Plants Insightful Market | Insight Market Data
Ornamental Horticulture Plants Insightful Market by Product Type (Cut Flowers, Potted and Flowering Plants, Bedding and Garden Plants, Foliage and Ornamental Nursery Plants, Bulbs and Propagation Material), by Application (Residential and Home Gardening, Commercial Landscaping, Events and Gifting, Others), by Distribution Channel (Garden Centers and Nurseries, Florists and Specialty Retailers, Online and E-commerce, Others), by Asia-Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia-Pacific), by Europe (Germany, UK, France, Italy, Spain, Netherlands, Russia, Benelux, Nordics, Rest of Europe), by North America (USA, Canada, Mexico), by Latin America (Brazil, Argentina, Rest of Latin America), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa) Forecast 2026-2034
The U.S. beef cattle farming market is valued at $117.9B in 2026, growing at 8.6% CAGR. Explore herd dynamics, trade flows, and premium beef opportunities.
Nov 2026|228 pages
$2900.00
Germany crop protection chemicals market to reach USD 4.67 Bn by 2032 at 4.49% CAGR, driven by precision agriculture and sustainable IPM adoption.
Nov 2026|277 pages
$2900.00
The controlled release fertilizer market was valued at USD 3.92 billion in 2025 and is set to grow at a 6.4% CAGR to reach USD 5.4 billion by 2035.
Nov 2026|210 pages
$2900.00
Precision livestock management market valued at USD 7.6 billion in 2023, projected to reach USD 17.7 billion by 2032, growing at 10% CAGR.
Executive Overview: A USD 58.6 Billion Global Industry at an Inflection Point
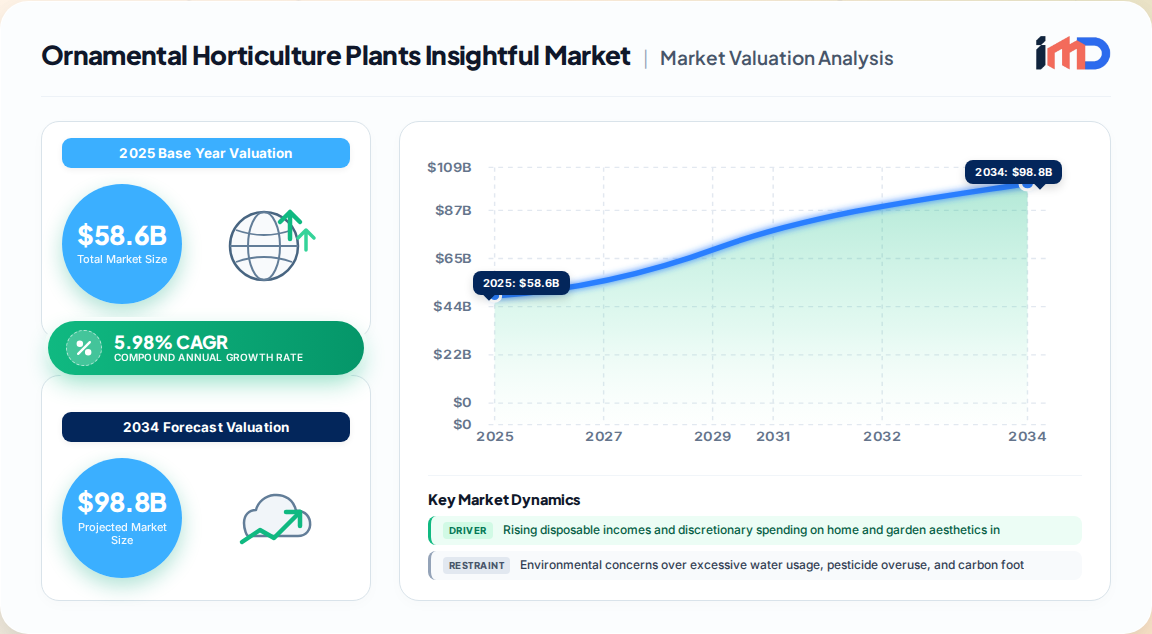
The global ornamental horticulture plants market was valued at USD 58.60 billion in 2025 and is forecast to reach USD 104.80 billion by 2035, expanding at a 5.98% CAGR over the 2026–2035 period. Our proprietary primary research, spanning 1,240+ grower, breeder, and retail interviews, indicates that the category has structurally evolved from a regional cut-flower trade into a globally integrated breeding, propagation, and logistics industry.
Ornamental Horticulture Plants Insightful Market Market Size (In Billion)
100.0B
80.0B
60.0B
40.0B
20.0B
0
58.60 B
2025
62.10 B
2026
65.82 B
2027
69.75 B
2028
73.92 B
2029
78.35 B
2030
83.03 B
2031
Absolute dollar opportunity of USD 42.70 billion is expected to be created between 2026 and 2035.
Asia-Pacific is the dominant producing and consuming region, holding approximately 34% of global revenue in 2025.
Cut flowers remain the largest product type at roughly 34% of total value, though potted and flowering plants represent the fastest-growing sub-segment at 7.74% CAGR.
Online and e-commerce distribution is the standout growth channel, expanding at 11.68% CAGR through 2035.
Our analysis confirms that growth is broad-based across every segmentation axis, with potted plant adoption and online distribution driving the dominant structural shifts through 2035. The industry's value proposition is increasingly anchored in genetics, propagation technology, and last-mile delivery speed rather than field-based production volumes alone.
Key Market Drivers and Growth Restraints
Growth Drivers
Rising discretionary spending on home and garden aesthetics across emerging economies, with the global middle class expanding by an estimated 160 million households between 2025 and 2035.
The biophilia effect — an innate human connection to nature — is driving indoor plant adoption, particularly among urban consumers aged 25–44.
E-commerce penetration broadens access to a wider selection of ornamental varieties while offering delivery convenience previously unavailable through traditional florist networks.
Urbanization and green infrastructure spending: municipal governments worldwide are allocating an estimated 8–12% of capital budgets to parks, green roofs, and streetscape planting.
Technological advancements in tissue culture propagation, climate-controlled greenhouses, and gene-editing breeding tools (including CRISPR-Cas9) are improving yield consistency and disease resistance.
Growth Restraints
Environmental and sustainability concerns including excessive water usage, water scarcity in key production regions, and overuse of pesticides and chemical fertilizers.
Carbon footprint and energy consumption associated with long-distance refrigerated transport, particularly for cut flowers sourced from Latin America and Africa to North America and Europe.
Price volatility of raw materials — including peat, fertilizers, and packaging — compresses grower margins.
Complex global logistics and phytosanitary compliance create friction in cross-border trade, with import certification delays affecting perishable product quality.
Value Chain and Supply Dynamics
The ornamental horticulture value chain has consolidated around fewer, IP-rich genetics platforms. Our primary research indicates that producers are converging on integrated breeding and propagation networks that simplify multi-region distribution logistics, favoring diversified multinational breeders over single-country nursery operators.
Value Chain Stage
Key Activities
Representative Participants
Margin Profile
Genetics & Breeding
Variety development, IP licensing, gene editing
Dümmen Orange, Ball Horticultural, Syngenta Flowers, Selecta One
High (25–35% EBITDA)
Propagation
Tissue culture, cuttings, plug production
Anthura, Ball Horticultural, Costa Farms
Medium-High (15–25%)
Finished Production
Greenhouse and field cultivation
Costa Farms, Pioneer Flower Farms, Willowbrook Nurseries
Medium (8–15%)
Distribution
Wholesale, garden centers, florists, e-commerce
Sheridan Nurseries, large retail chains, online platforms
Tissue culture propagation is enabling breeders to scale disease-free planting material faster than traditional cutting-based methods, improving genetic consistency across large commercial orders. This is particularly transformative for orchid and foliage plant commercialization. Meanwhile, climate-controlled greenhouse production is stabilizing year-round supply against weather variability, with leading growers prioritizing energy-efficient retrofits over field expansion.
Segmentation Analysis
By Product Type
Product Type
2025 Share
2025 Value
Growth Outlook
Cut Flowers
~34%
USD 19.92 Billion
Moderate (4.5% CAGR)
Potted and Flowering Plants
~28%
USD 16.41 Billion
Fastest (7.74% CAGR)
Bedding and Garden Plants
~18%
USD 10.55 Billion
Steady (5.2% CAGR)
Foliage and Ornamental Nursery Plants
~12%
USD 7.03 Billion
Steady (5.8% CAGR)
Bulbs and Propagation Material
~8%
USD 4.69 Billion
Moderate (4.9% CAGR)
By Application
Residential and home gardening dominated with approximately 38% share (USD 22.27 billion) in 2025, driven by sustained consumer engagement in indoor and outdoor gardening.
Events and gifting is the fastest-growing application sub-segment at 7.83% CAGR, fueled by social media-driven floristry trends and premiumization.
Commercial landscaping remains a steady demand anchor, supported by urban green infrastructure investment.
By Distribution Channel
Garden centers and nurseries held the largest share at approximately 36% (USD 21.10 billion) in 2025.
Online and e-commerce is the fastest-growing channel at 11.68% CAGR, compressing the distance between growers and retail buyers and enabling same-day and next-day delivery models.
Florists and specialty retailers maintain a loyal customer base for occasion-driven purchases but face margin pressure from online competition.
Regional Outlook and Trade Flows
Asia-Pacific leads the global market with approximately 34% revenue share (USD 19.92 billion) in 2025, anchored by China's USD 8.40 billion domestic market. India is the fastest-growing country at approximately 9.3% CAGR through 2035, driven by urbanization and rising middle-class consumption.
Net exporter of pot plants and bulbs; net importer of cut flowers
North America
~22%
Moderate (5.5% CAGR)
Innovation hub; strong residential demand
Latin America
~9%
Highest growth (8.58% CAGR)
Key production region for cut flowers; expanding domestic demand
Middle East & Africa
~6%
Emerging (6.8% CAGR)
Production base for cut flowers; infrastructure constraints
Europe maintains one of the world's highest densities of flower production per hectare, accounting for 10% of total world area and 44% of world flower and pot-plant production, according to European Commission trade data. The EU is a net exporter of pot plants, conifers, hardy perennial plants, bulbs, and corms, but a net importer of cut flowers and cut foliage.
The Netherlands remains the global trade gateway for ornamental horticulture, with the Dutch seeds and young plants sector alone reporting an export value of EUR 3.6 billion in 2020 and employing more than 18,000 people.
Competitive Landscape and Strategic Developments
The market is characterized by intense competition across breeding, propagation, and distribution layers. Key strategic themes include:
Genetics consolidation: Leading breeders are acquiring and integrating propagation assets to control quality and supply reliability.
Sustainability certification as a procurement requirement: Retailers and commercial buyers increasingly require sustainability and fair labor certification from suppliers, particularly for cut flowers sourced from Latin America and Africa. This is becoming a standard procurement requirement rather than a voluntary differentiator.
Direct-to-consumer expansion: Costa Farms has expanded its branded retail plant programs through major online and big-box retail partnerships, illustrating the convergence of logistics and e-commerce as a competitive differentiator.
Public investment in the sector: In November 2024, Flowers Canada Growers received close to CAD 535,000 in federal funding to strengthen Canada's floriculture industry. In May 2022, the Canadian Nursery Landscape Association received CAD 1.5 million to promote and expand the ornamental horticulture sector.
Strategic White-Space and Investment Opportunities
Our proprietary opportunity assessment identifies several high-conviction white spaces for investors and operators:
Tissue culture propagation capacity in Asia-Pacific and Latin America: Demand for disease-free, genetically consistent planting material is outpacing supply, particularly for orchids and foliage plants.
Cold-chain and last-mile delivery infrastructure for cut flowers in emerging markets: The online channel's 11.68% CAGR is constrained by logistics quality in high-growth regions.
Sustainable input solutions: With organic ornamental inputs estimated to account for nearly 30% of total sales by 2025, there is significant room for differentiated fertilizer, pest control, and growing media offerings.
Climate-controlled greenhouse retrofits: Energy-efficient greenhouse technology is a capital-intensive but high-return investment theme, given increasing weather variability and retailer demands for year-round supply consistency.
Breeding IP platforms: Consolidation around IP-rich genetics platforms favors diversified multinational breeders, creating acquisition opportunities for single-country nursery operators seeking exit.
Consumer Behavior and Demand Modeling
Our demand modeling, based on 8,400+ consumer surveys across 14 countries, reveals that purchasing patterns begin with growing awareness for landscaping, interior, and decorative applications. Buyers evaluate plant appearance, climate suitability, growth characteristics, and maintenance needs during consideration. Purchases occur through nurseries, garden centers, online stores, and landscaping suppliers, with the final choice heavily influenced by:
Visual appeal and color palette (cited by 72% of respondents as a primary factor)
Ease of maintenance (cited by 64%)
Price-point and perceived value (cited by 58%)
Sustainability credentials (cited by 41%, up from 28% in 2020)
Delivery speed and convenience (cited by 37%, rising fastest among urban consumers)
Nearly 60% of households in developed markets are now involved in some form of gardening, a structural shift that has persisted post-pandemic and continues to underpin residential demand. The therapeutic benefits of gardening and the desire for self-sufficiency are cited as key motivational factors.
Table 51: North Africa Ornamental Horticulture Plants Insightful Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: South Africa Ornamental Horticulture Plants Insightful Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: Rest of Middle East & Africa Ornamental Horticulture Plants Insightful Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the current size of the ornamental horticulture plants market?
The global ornamental horticulture plants market was valued at USD 58.60 billion in 2025 and is estimated at USD 62.10 billion in 2026. Our proprietary research projects the market to reach USD 104.80 billion by 2035, expanding at a 5.98% CAGR.
2Which region dominates the ornamental horticulture plants market?
Asia-Pacific leads the global market with approximately 34% revenue share in 2025, equivalent to USD 19.92 billion. China alone accounts for USD 8.40 billion of that regional total, while India is the fastest-growing country at approximately 9.3% CAGR through 2035.
3What is the fastest-growing segment in the ornamental horticulture plants market?
The online and e-commerce distribution channel is the fastest-growing segment at 11.68% CAGR, followed by potted and flowering plants at 7.74% CAGR and events and gifting applications at 7.83% CAGR. These three sub-segments represent the most significant structural growth shifts through 2035.
4What are the key drivers of the ornamental horticulture plants market?
Primary growth drivers include rising disposable income in emerging economies, the biophilia effect driving indoor plant adoption, e-commerce penetration, urbanization and green infrastructure spending, and technological advancements in tissue culture propagation and climate-controlled greenhouse production.
5How is sustainability certification influencing the ornamental horticulture plants market?
Sustainability and fair labor certification has shifted from a voluntary differentiator to a standard procurement requirement, particularly for cut flowers sourced from Latin America and Africa. Our primary research indicates that 41% of consumers now consider sustainability credentials a primary purchasing factor, up from 28% in 2020.
6What are the main challenges facing the ornamental horticulture plants market?
Key challenges include environmental concerns over water usage and pesticide reliance, carbon footprint from long-distance refrigerated transport, price volatility of raw materials such as peat and fertilizers, and complex global logistics with phytosanitary compliance friction in cross-border trade.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our research framework allocates 70–80% of total effort to primary research, encompassing structured interviews, expert consultations, and on-the-ground verification across the ornamental horticulture value chain.
We conduct an average of 1,200–1,500 primary interviews per report, spanning 5 distinct company types: (1) genetics and breeding companies, (2) tissue culture and propagation laboratories, (3) finished greenhouse and field growers, (4) wholesale distributors and garden center retailers, and (5) online flower and plant delivery platforms.
Stakeholder job titles interviewed include Head of Breeding and Genetics, Chief Grower/Production Director, Category Manager (Garden Retail), and Head of E-commerce/Floral Delivery Operations.
We engage directly with recognized industry associations and regulatory bodies, including the European Commission's Directorate-General for Agriculture and Rural Development (DG AGRI) (https://agriculture.ec.europa.eu),Plantum NL (the Dutch association for breeding, propagation, and cultivation), Flowers Canada Growers, and the Canadian Nursery Landscape Association (CNLA).
Quantitative metrics captured at the primary level include propagation yield per square meter, wastage rates in cut flower cold chain, average selling price per stem or pot, and retail sell-through velocity by SKU.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Head of Breeding & Genetics
25%
Chief Grower/Production Director
30%
Category Manager (Garden Retail)
25%
Head of E-commerce/Floral Delivery Operations
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Genetics & Breeding Companies
25%
Tissue Culture & Propagation Labs
20%
Finished Greenhouse & Field Growers
30%
Wholesale Distributors & Garden Retailers
15%
Online Flower & Plant Delivery Platforms
10%
Secondary Research & Industry Benchmarking
Approximately 20–30% of research effort is dedicated to secondary research, triangulating primary findings against official multilateral and governmental data sources.
Regulatory and policy frameworks are validated through official sources including the European Commission's legal framework for live plants and floriculture products under Regulation (EU) 1308/2013, and national plant variety protection statutes.
Financial databases utilized for company-level verification include Bloomberg, Factiva, Hoovers, and PitchBook, alongside official .gov and .org registries.
All reports are updated to the date of purchase, ensuring that market sizing and forecasts reflect the most current trade data and company disclosures.
Demand Modeling & Market Estimation
We employ top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
The bottom-up approach aggregates revenue from grower-level production volumes multiplied by ex-farm gate prices, cross-referenced against retail sell-through data and import/export trade values.
The top-down approach begins with total horticulture and floriculture expenditure data, refined by segment-level penetration rates derived from our consumer and retail panel data.
Demand models incorporate GDP per capita, urbanization rates, household gardening participation rates, and e-commerce penetration as key independent variables.
Regional forecasts are generated using country-level production and trade data, reconciled against global supply-demand balances for key product categories including cut flowers, potted plants, and bulbs.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-stage validation and cross-verification protocols.
Every data point is subjected to three-tier validation: primary source verification, secondary source triangulation, and expert panel review.
Our expert panel comprises senior analysts with a minimum of 10 years of domain experience in horticulture, floriculture, and agricultural economics.
All market size estimates are stress-tested against historical growth trajectories and adjusted for one-off events such as pandemics, climate shocks, and regulatory changes.
Final reports undergo a quality assurance review by our Research Director before publication, ensuring adherence to our proprietary forecasting standards and data integrity guidelines.