1What is the Germany crop protection chemicals market size?
The market was valued at USD 3.59 billion in 2026 and is projected to reach USD 4.67 billion by 2032, growing at a CAGR of 4.49%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Germany Crop Protection Chemicals Market
 by Function (Fungicide, Herbicide, Insecticide, Molluscicide, Others), by Application Mode (Chemigation, Foliar, Fumigation, Seed Treatment, Soil Treatment), by Crop Type (Commercial Crops, Fruits and Vegetables, Grains and Cereals, Oilseeds and Pulses, Others), by Bavaria, by North Rhine-Westphalia, by Lower Saxony, by Baden-Württemberg, by Other States Forecast 2026-2034
Research Associate

 Related Reports

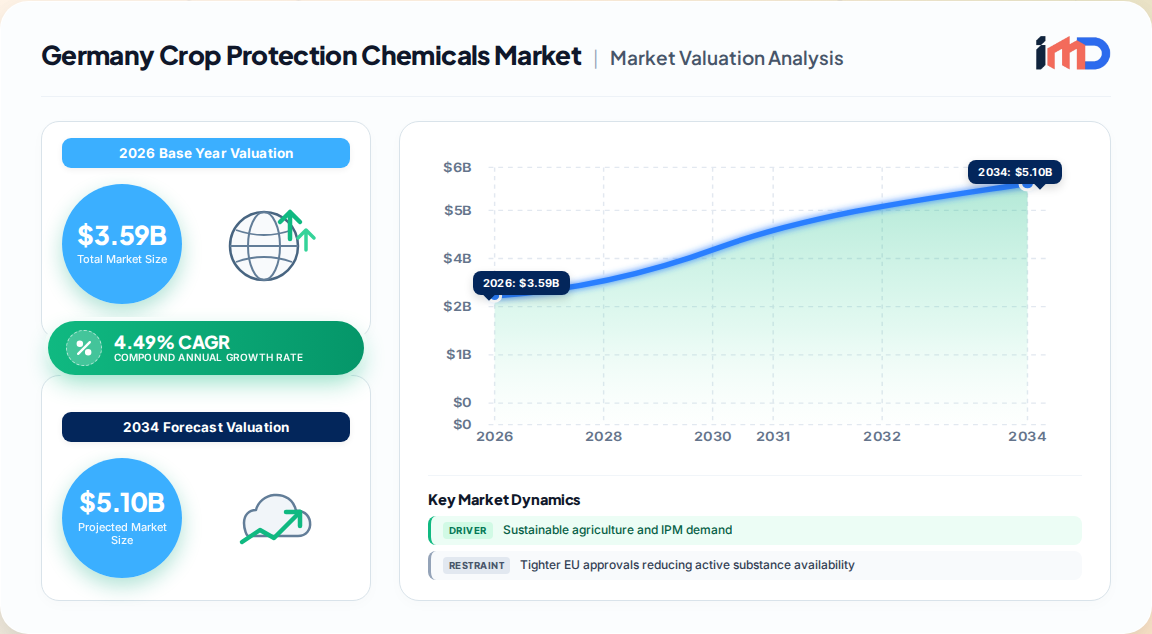
The Germany crop protection chemicals market is valued at USD 3.59 billion in 2026 and is projected to reach USD 4.67 billion by 2032, expanding at a CAGR of 4.49% during the forecast period (2027–2032). Germany remains Europe's largest agricultural chemical market, underpinned by intensive cereal, oilseed rape, and sugar beet rotations that demand recurring protection programs. The market is transitioning from volume-driven conventional spraying toward value-driven, precision-guided applications, with treated volumes stabilizing as regulatory pressures and integrated pest management (IPM) mandates reshape grower behavior.
Germany's crop protection sector operates within the EU's stringent regulatory framework, which has progressively narrowed the active substance portfolio. This has accelerated demand for replacement chemistries, co-formulations, and biologicals. Simultaneously, the national Zukunftsprogramm Pflanzenschutz (Future Program for Plant Protection) and Bavaria's target to cut synthetic chemical plant protection products by 50% by 2028 are compelling growers to adopt precision tools and integrated approaches.
The German crop protection value chain is characterized by a high degree of integration between R&D-intensive innovators and sophisticated distribution networks.
| Stage | Key Activities | Representative Participants | Value-Added Share |
|---|---|---|---|
| R&D and Active Ingredient Synthesis | Discovery, toxicology, formulation development, regulatory dossiers | BASF SE, Bayer AG, Syngenta, Corteva | 35–40% |
| Formulation and Blending | Mixing, packaging, co-formulation, biological integration | Same as above plus specialty formulators | 15–20% |
| Distribution and Logistics | Wholesale, retail, parallel trade, advisory services | Agrarhandel, Raiffeisen cooperatives, specialized distributors | 20–25% |
| Application and Advisory | Precision spraying, record-keeping, IPM consulting | Commercial farms, contractors, advisory services | 15–20% |
| End User | Crop production | Arable and horticultural farms | 5–10% (margin) |
A distinctive feature of the German market is the role of parallel trade normalization, which improves local product availability and exerts downward pressure on prices. Distributors are increasingly bundling digital record-keeping and spray advisory services with product sales to build stickiness.
Germany is a net exporter of crop protection chemicals, with significant trade flows within the EU and to non-EU markets. Official Eurostat data on pesticide sales (compiled by the German Federal Office of Consumer Protection and Food Safety, BVL) indicates that domestic sales of active substances have remained relatively stable in recent years, while export volumes have grown.
Supply chain risks include raw material price volatility, regulatory changes affecting key intermediates, and logistical bottlenecks. However, Germany's robust chemical infrastructure and strategic location within the EU mitigate these risks relative to other regions.
The German crop protection chemicals market is segmented by function, application mode, and crop type, with each segment exhibiting distinct growth dynamics.
| Segment | Share (2026) | CAGR (2027–2032) | Key Insights |
|---|---|---|---|
| Insecticides | 63% | 4.2% | Dominant share due to high pest pressure in oilseed rape and cereals; however, growth is tempered by regulatory restrictions on neonicotinoids. |
| Herbicides | 22% | 4.0% | Mature segment facing resistance challenges; precision spot spraying is reducing volumes but increasing value per hectare. |
| Fungicides | 10% | 4.8% | Driven by disease pressure in cereals and sugar beet; climate change is expanding fungal disease geography. |
| Molluscicides | 3% | 5.1% | Fastest-growing segment due to wet autumns favoring slug populations in oilseed rape establishment. |
| Others (including PGRs, biologicals) | 2% | 5.5% | Biologicals and plant growth regulators are gaining traction under IPM programs. |
| Mode | Share (2026) | CAGR (2027–2032) |
|---|---|---|
| Foliar | 53% | 4.3% |
| Seed Treatment | 18% | 5.5% |
| Soil Treatment | 15% | 4.0% |
| Chemigation | 10% | 4.8% |
| Fumigation | 4% | 3.5% |
Foliar application remains the dominant mode, but seed treatment is the fastest-growing, driven by convenience and targeted protection at planting.
| Crop Type | Share (2026) | CAGR (2027–2032) |
|---|---|---|
| Grains & Cereals | 60% | 4.4% |
| Oilseeds & Pulses | 18% | 4.6% |
| Fruits & Vegetables | 12% | 5.3% |
| Commercial Crops (sugar beet, etc.) | 7% | 4.5% |
| Others | 3% | 4.9% |
Grains and cereals dominate due to extensive acreage, while fruits and vegetables exhibit the highest growth rate, supported by higher-value crops and intensive protection regimes.
Germany's agricultural landscape varies significantly by region, influencing crop protection demand patterns.
The German market is characterized by a mix of global innovators and regional distributors, with competition centered on active ingredient pipelines, formulation technology, and regulatory expertise.
| Company | Headquarters | Key Strengths in Germany |
|---|---|---|
| BASF SE | Ludwigshafen, Germany | Broad portfolio, strong R&D, integrated digital tools (xarvio) |
| Bayer AG | Leverkusen, Germany | Leading in seed treatments and insecticides; extensive distribution network |
| Syngenta Crop Protection AG | Basel, Switzerland | Strong fungicide and herbicide portfolio; precision agriculture partnerships |
| Corteva Agriscience | Wilmington, USA | Growing presence in biologicals and seed-applied technologies |
| FMC Corporation | Philadelphia, USA | Focus on insecticides and herbicides; niche crop expertise |
| UPL Europe Ltd. | Mumbai, India | Competitive generic portfolio; strong in post-patent actives |
| Nufarm Ltd. | Melbourne, Australia | Herbicide-focused; strategic acquisitions in Europe |
| ADAMA Group | Tel Aviv, Israel | Diverse off-patent portfolio; strong distribution relationships |
| Certis Europe BV | Utrecht, Netherlands | Biologicals and IPM-compatible products |
| Novozymes A/S | Copenhagen, Denmark | Biological solutions and seed treatments |
Recent developments include Bayer's registration of Buteo Start for sugar beet in 2025, demonstrating continued innovation in high-value crop programs. BASF has expanded its digital advisory platform, while Syngenta has invested in biologicals through partnerships.
Several underpenetrated segments present growth opportunities:
Companies that can provide integrated solutions combining chemistry, biologicals, and digital tools are best positioned to capture premium value.
German growers and distributors employ sophisticated procurement strategies:
Distributors must balance portfolio breadth with regulatory compliance, as products must be approved for German use. Suppliers that offer complete resistance management programs and reliable local supply are favored.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.49% from 2020-2034 |
| Segmentation |
|
By Crop Type
| By Geography |
|
The market was valued at USD 3.59 billion in 2026 and is projected to reach USD 4.67 billion by 2032, growing at a CAGR of 4.49%.
Insecticides account for 63% of the market share in 2026, driven by high pest pressure in oilseed rape and cereals.
Key players include BASF SE, Bayer AG, Syngenta Crop Protection AG, Corteva Agriscience, and FMC Corporation, among others.
Drivers include sustainable agriculture and IPM demand, precision agriculture adoption, climate-driven pest pressure, and yield protection in key crops.
Grains and cereals accounted for 60% of the market share in 2026, supported by extensive wheat, barley, and rye acreage.
Precision tools like real-time spot spraying are economically viable for sugar beet farms above 60–172 hectares and cereal farms above 300–400 hectares, shifting demand toward specialized formulations and reducing overall volumes.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| C-Level Executives (CEO, Managing Director) | 25% |
| Procurement Directors | 30% |
| Regulatory Affairs Managers | 20% |
| Farm Operations Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Crop Protection Chemical Manufacturers | 30% |
| Formulation & Blending Specialists | 20% |
| Agricultural Distributors & Cooperatives | 25% |
| Precision Agriculture Technology Providers | 15% |
| Contract Research Organizations | 10% |