1What is the current size of the controlled release fertilizer market?
The controlled release fertilizer market was valued at USD 3.92 billion in 2025 and is projected to reach USD 5.4 billion by 2035, growing at a CAGR of 6.4% from 2026 to 2035.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Controlled Release Fertilizer Market
 by Coating Technology (Polymer-Coated, Polymer-Sulfur-Coated, Sulfur-Coated, Others), by Nutrient Composition (Nitrogen, Phosphorus, Potassium, Micronutrients), by Crop Type (Field Crops, Horticultural Crops, Turf and Ornamental), by End User (Farmers, Commercial Growers), by Distribution Channel (Retail Stores, Online Sales), by Asia-Pacific (China, Japan, India, Australia), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Spain), by South America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, South Africa) Forecast 2026-2034
Research Associate


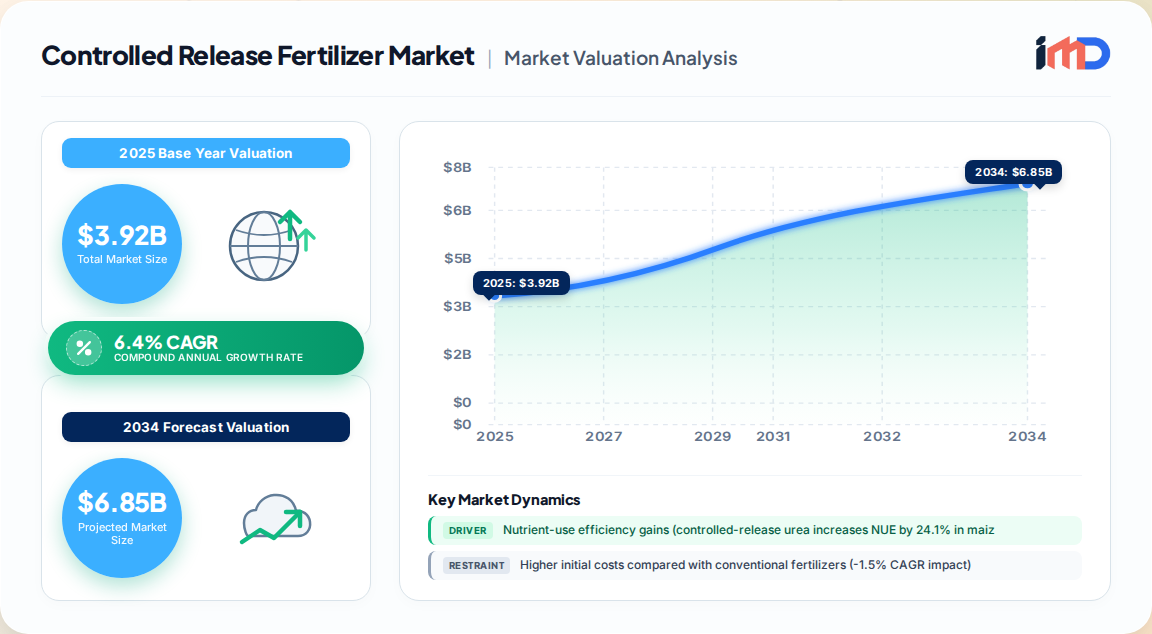
The global controlled release fertilizer (CRF) market is undergoing a structural reallocation of spending, moving away from conventional commodity nutrient volume toward controlled delivery and nutrient-use efficiency. Our proprietary primary research estimates the market at USD 3.92 billion in 2025, advancing to approximately USD 4.30 billion in 2026, and projected to reach USD 5.4 billion by 2035 at a CAGR of 6.4% (2026–2035).
The commercial proposition of CRFs is anchored in eliminating the mismatch between soluble nutrient pulses and staged crop demand. As global nutrient demand is projected to reach 224 million tonnes by FY2029 (per the International Fertilizer Association), and nitrogen loss pathways—leaching, volatilization, and denitrification—remain a critical economic and environmental concern, CRFs are increasingly viewed as a risk-mitigation input rather than a premium luxury.
Key Market Metrics (2025–2035):
| Metric | Value |
|---|---|
| 2025 Market Size | USD 3.92 Billion |
| 2026 Market Size | USD 4.30 Billion |
| 2035 Forecast Size | USD 5.4 Billion |
| CAGR (2026–2035) | 6.4% |
| Largest Region | Asia-Pacific (46% share) |
| Fastest-Growing Region | Latin America |
| Leading Coating Technology | Polymer-Coated (72.5% share) |
| Top 5 Player Concentration | 47.7% |
By Coating Technology:
By Crop Type:
By Application and End User:
Asia-Pacific holds the largest regional share at approximately 46%, driven by China's massive agricultural sector, government support for efficient fertilizer usage, and rapid modernization. China alone captures roughly 20% of the global market. The region is also projected to be the fastest-growing at a 7.6% CAGR through 2031, supported by precision agriculture adoption and polymer-coated urea penetration.
North America is the second-largest market, with the U.S. alone estimated at USD 444.16 million in 2025, growing at a robust 8.20% CAGR to reach USD 976.81 million by 2035. The Far West region leads U.S. growth at a 9.5% CAGR, followed by the Rocky Mountain region at 8.9%. Polymer-coated urea is the leading product type in the U.S., with a 9.0% CAGR, and cereals and grains account for a 9.3% market share.
Europe is a compliance-driven market. The EU's biodegradability criteria are accelerating substitution away from persistent conventional coatings. Producers able to document compliant biodegradation can defend regulated channels, while others must reformulate before the 2028 deadline.
Latin America is the fastest-growing region globally, driven by sugarcane, plantation crops, and a large agricultural base demanding efficient nutrient management.
The market is concentrated, with the top five players—ICL Group Ltd., Haifa Group, Koch Agronomic Services, The Scotts Miracle-Gro Company, and Nutrien Ltd.—collectively holding 47.7% of the market in 2025. ICL Group leads with over 11.4% share.
Strategic White-Space Opportunities:
The CRF value chain is exposed to feedstock and coating-material supply risks. In May 2026, Mosaic partially curtailed phosphate production at its Louisiana and Bartow facilities due to record sulfur prices, tightening nutrient inputs critical to coated fertilizer manufacturing. This supply-side constraint is compounded by tight supply of polyethylene and polyurethane feedstocks, which is nudging producers toward starch-polyester blends that comply with the 2028 biodegradability deadline and reduce exposure to petrochemical volatility.
On the trade policy front, Mosaic and Simplot submitted support for maintaining countervailing duties on Moroccan and Russian phosphate fertilizer in the active five-year International Trade Commission review, reinforcing domestic supply chain protections in the U.S. market.
Supplier and Distribution Dynamics:
The CRF market's trajectory is not a uniform conversion to biodegradable chemistry but a disciplined product tiering and compliance-led substitution. The addressable opportunity is strongest where one well-timed application can replace repeated field access, or where nutrient losses threaten a regulated water body, a high-value crop, or a professional landscape standard.
As water scarcity intensifies and labor costs rise in Japan, Western Europe, and peri-urban Asia-Pacific, the value of application avoidance will continue to rise. The forecast of USD 5.4 billion by 2035 at a 6.4% CAGR reflects a fundamental reallocation of fertilizer spend toward controllability—a shift that rewards producers who can combine release precision, regulatory compliance, and data-driven service bundles.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
By Crop Type
By End User
By Distribution Channel
| By Geography |
|
The controlled release fertilizer market was valued at USD 3.92 billion in 2025 and is projected to reach USD 5.4 billion by 2035, growing at a CAGR of 6.4% from 2026 to 2035.
Asia-Pacific holds the largest regional share at approximately 46%, driven by China's massive agricultural sector, which alone captures about 20% of the global market.
The top five players—ICL Group Ltd., Haifa Group, Koch Agronomic Services, The Scotts Miracle-Gro Company, and Nutrien Ltd.—collectively held 47.7% of the market in 2025, with ICL Group leading at over 11.4% share.
Key drivers include nutrient-use efficiency gains (controlled-release urea increases nitrogen-use efficiency by 24.1% in maize), precision agriculture integration, labor cost reduction, and environmental regulations limiting nutrient losses.
EU Delegated Regulation 2024/2770 sets biodegradability criteria for coating agents from October 2028, forcing producers to reformulate away from persistent conventional coatings toward starch-polyester blends and polycaprolactone. This shifts competition from release performance alone toward verifiable end-of-function coating behavior.
Polymer-coated fertilizers are the fastest-growing coating technology at a 7.4% CAGR, while turf and ornamental crops are the fastest-growing crop segment at a 7.2% CAGR through 2031.
Higher initial costs compared with conventional fertilizers (a -1.5% CAGR impact) and limited farmer awareness in developing agricultural economies are the primary restraints, alongside reformulation cost and performance trade-offs due to the EU biodegradability deadline.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Agronomist | 34% |
| Supply Chain Director | 26% |
| Product Development Manager | 24% |
| Sustainability & Regulatory Affairs Director | 16% |
| Company Type | Representation (%) |
|---|---|
| CRF Manufacturers & Blenders | 32% |
| Coating Technology Developers | 22% |
| Agricultural Input Distributors & Cooperatives | 20% |
| Precision Agriculture Equipment OEMs | 14% |
| Commercial Growers & Plantation Managers | 12% |
 Related Reports
