1What is the size of the U.S. beef cattle farming market in 2026?
The U.S. beef cattle farming market (NAICS 11211) is estimated at $117.9 billion in revenue for 2026, growing at a CAGR of 8.6% since 2021 despite a historically small national herd.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Beef Cattle Farming Market
 by By Product (cattle)(Steers, Heifers, Dairy Cows), by By Cut Type (Ground Beef, Steak Cuts, Ribeye, Sirloin, Processed and Value-Added Products), by By Distribution Channel (Retail Grocery Stores, Foodservice, E-Commerce and Online Retail), by By Production System (Conventional Grain-Fed Feedlot, Grass-Fed/Finished, Certified Organic, Natural/Antibiotic-Free), by United States (West, Midwest, South, Northeast) Forecast 2026-2034
Research Associate

 Related Reports

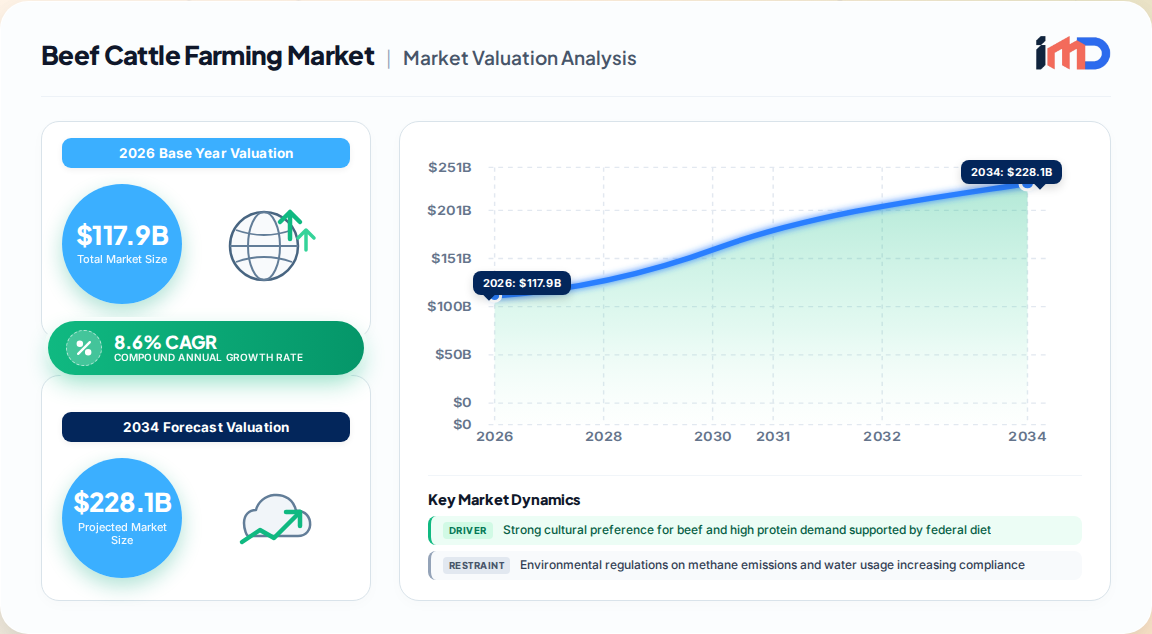
The U.S. beef cattle farming market—defined by NAICS 11211 and encompassing cow-calf operations, stocker/backgrounding programs, and feedlot finishing—generated an estimated $117.9 billion in revenue in 2026, expanding at a CAGR of 8.6% since 2021. This growth has been achieved despite a historically contracted national herd: beef cow numbers stood at a record July low of 28.5 million head in 2026, and the 2026 calf crop is projected to be the smallest on record.
The fundamental market equation is one of scarcity-driven price appreciation. Persistent drought through the early 2020s forced aggressive liquidation, and the biological lag of the cattle cycle (8–12 years) means supply cannot respond quickly. The result is elevated cattle prices, improved cow-calf margins, and a sector that is structurally smaller but economically more valuable per head.
Key market metrics at a glance:
| Metric | 2025 Value | 2026 Estimate | 2033 Forecast | CAGR (2026–2033) |
|---|---|---|---|---|
| Beef cattle farming revenue (U.S.) | $115.5 billion | $117.9 billion | $201.6 billion | 8.6% |
| Beef cattle health input market | $6.2 billion | $6.7 billion | $12.6 billion | 9.4% |
| U.S. beef retail/foodservice market | $113.5 billion | $119.0 billion | $174.8 billion (2034) | 4.92% |
Domestic demand remains resilient, supported by higher federal protein recommendations and GLP-1-driven consumer interest in protein-dense foods. However, the industry faces structural headwinds: a phased reopening of the U.S.–Mexico cattle border, rising export competition from Brazil, and tightening environmental regulation.
1. Tight domestic inventories and elevated cattle prices. The smallest calf crop on record has created a seller's market. Feeder cattle and fed cattle prices have reached cyclical highs, driving revenue growth even as volumes decline. Cow-calf operators are retaining heifers at higher rates, signaling early-stage herd rebuilding.
2. Resilient domestic protein demand. Per capita beef consumption stands at approximately 57 pounds annually. Ground beef remains the largest cut segment at 23.4% share (2025), prized for versatility and affordability, while steak cuts are the fastest-growing at a 12.3% CAGR as disposable income and premiumization drive indulgent at-home dining.
3. Export market expansion. U.S. beef exports have exceeded 3 billion pounds in volume and $10 billion in value in recent years, with Japan, South Korea, Mexico, and Canada as key destinations. Trade agreements such as the USMCA provide tariff-free access and support higher cattle prices for ranchers.
4. Technological advancement in herd management. Precision livestock monitoring, AI-enabled disease detection, and supply chain traceability tools are improving feed efficiency, health surveillance, and quality assurance—critical as margins tighten and export buyers demand verified sustainability attributes.
Environmental regulation and input volatility. Cattle production is under scrutiny for methane emissions and water usage. Compliance costs for emissions monitoring, waste management, and water rights are disproportionately burdensome for smaller operations. Feed, energy, and fertilizer costs remain volatile, compressing margins in feedlot operations.
Animal disease and biosecurity risks. Bovine respiratory disease (BRD) remains the costliest feedlot health issue. The New World screwworm threat has prompted coordinated preparedness initiatives, while foot-and-mouth disease concerns periodically disrupt trade. The phased reopening of the U.S.–Mexico cattle border adds supply uncertainty.
Labor shortages. Processing and production facilities continue to face difficulty attracting and retaining skilled labor, limiting throughput and raising wage costs. This constraint is particularly acute in rural areas where packing plants are concentrated.
International competition. Brazil has emerged as the world's largest beef exporter at approximately 2.9 million metric tons (2024), leveraging lower production costs and expanding access to Asian markets. U.S. exporters face increasing price competition in price-sensitive segments.
The U.S. beef cattle farming value chain is segmented and biologically constrained:
The U.S. is the world's largest beef producer and a major exporter, but it is also a significant importer of lean beef for blending. Trade flows are shaped by animal disease status, currency movements, and bilateral agreements.
Top beef exporting countries, 2024 (metric tons):
| Country | Export Volume |
|---|---|
| Brazil | ~2,900,000 |
| Australia | ~1,690,000 |
| United States | ~1,500,000 |
| India | ~1,400,000 |
| Argentina | ~600,000 |
| Uruguay | ~420,000 |
Supplier dynamics:
The U.S. beef cattle farming market is geographically concentrated, with distinct regional profiles:
| Region | Share of Market | Key Characteristics |
|---|---|---|
| West | 32% | Great Plains feedlot concentration; large-scale cow-calf operations; drought exposure |
| Midwest | 27% | Corn Belt feeding operations; integrated crop-livestock systems |
| South | 23% | Texas, Oklahoma, Florida cow-calf herds; stocker operations |
| Northeast | 18% | Premium and direct-to-consumer markets; smaller herds; high-value niche products |
Investment opportunities are strongest in:
By product type (cattle): Steers, heifers, and dairy cows (for dairy herd replacements and beef).
By beef cut type:
By distribution channel (beef products):
By production system:
The beef cattle farming industry is highly fragmented at the farm level—no single company holds more than 5% market share in ranching and farming. However, the processing and packing sector is highly concentrated, dominated by large vertically integrated processors.
Key companies in the broader beef value chain:
Strategic imperatives for producers and integrators:
Several underpenetrated opportunities merit attention:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2026 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.6% from 2020-2034 |
| Segmentation |
|
By Distribution Channel
By Production System
| By Geography |
|
The U.S. beef cattle farming market (NAICS 11211) is estimated at $117.9 billion in revenue for 2026, growing at a CAGR of 8.6% since 2021 despite a historically small national herd.
Prices are elevated because beef cow numbers sit at a record July low of 28.5 million head and the 2026 calf crop is the smallest on record, tightening supplies while domestic and export demand remain strong.
Steak cuts are the fastest-growing segment at a 12.3% CAGR, driven by premiumization and rising disposable incomes, while ground beef remains the largest segment with 23.4% share in 2025.
The processing sector is highly concentrated, with Tyson Foods, JBS USA, Cargill, and National Beef Packing dominating. At the farm level, the industry is highly fragmented with no company holding more than 5% market share.
U.S. beef exports have exceeded 3 billion pounds in volume and $10 billion in value in recent years, with Japan, South Korea, Mexico, and Canada as the top destinations.
Tight cattle supplies, high input costs, labor shortages in processing, and biosecurity risks such as New World screwworm and bovine respiratory disease are the most pressing challenges.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Ranch Owner/Operator | 35% |
| Feedlot Production Manager | 30% |
| Beef Procurement Director | 20% |
| Veterinary Herd Health Advisor | 15% |
| Company Type | Representation (%) |
|---|---|
| Cow-Calf Ranching Operations | 30% |
| Cattle Feedlot Operators | 25% |
| Beef Processors & Packers | 20% |
| Animal Health & Feed Suppliers | 15% |
| Retail & Foodservice Buyers | 10% |