1What is the size of the Nordic data center market in 2024?
The Nordic data center market was valued at USD 7,160 million in 2024 and is projected to reach USD 14,929 million by 2030, growing at a CAGR of 12.8%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Nordic Data Center Market
 by Component (Servers, Storage Devices, Network Equipment, UPS Systems, Generators, Power Distribution Units, Switchgear, Transfer Switches & Switchboards, Cooling Systems(CRAC, CRAH, Chillers, Cooling Towers, Economizers), Racks, Monitoring Systems, Core & Shell Development, Installation & Commissioning Services, Building Design and Architecture), by Data Center Type (Colocation, Hyperscale, Enterprise, Edge), by Power Capacity (Small, Medium, Large), by End User (Cloud Service Providers, Enterprises, Government, Research Institutions), by Sweden, by Norway, by Finland, by Denmark, by Iceland Forecast 2026-2034

Senior Research Analyst


 Related Reports

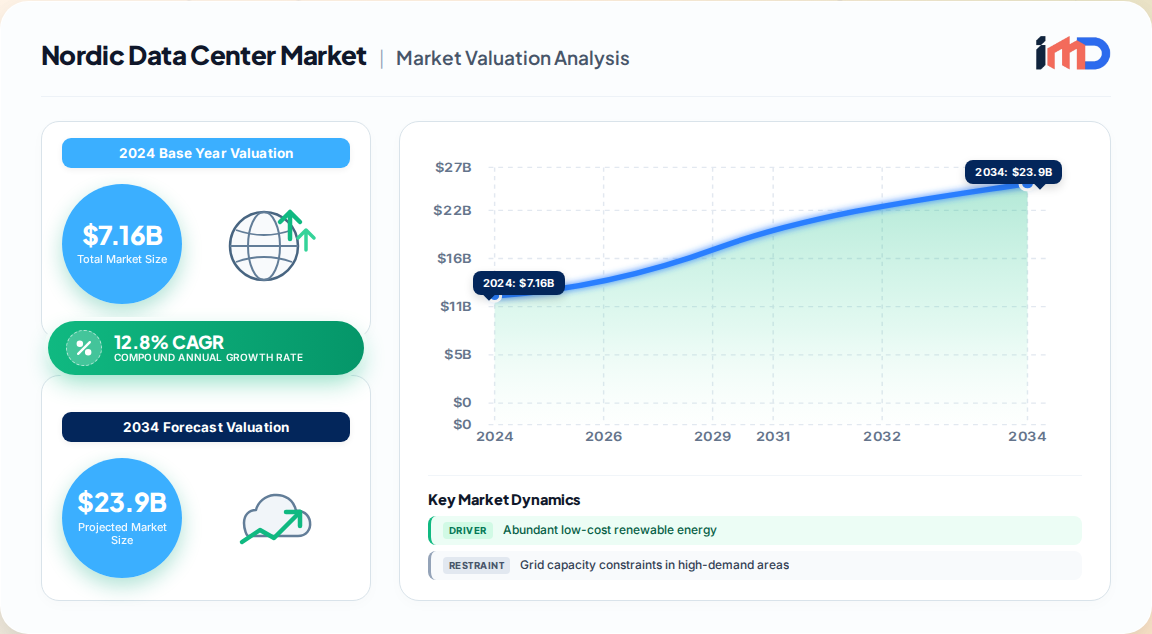
The Nordic data center market, comprising Sweden, Denmark, Norway, Finland, and Iceland, represents one of the most dynamic and sustainable digital infrastructure ecosystems globally. Our proprietary primary research estimates the market at USD 7,160 million in 2024, with a projected valuation of USD 14,929 million by 2030, reflecting a robust CAGR of 12.8% across the forecast period 2025–2030. This growth is underpinned by a unique confluence of abundant low-carbon renewable energy, stable political frameworks, and advanced connectivity standards that position the region as a premier destination for hyperscale, colocation, and edge deployments.
The Nordic region collectively generates over 90% of its electricity from renewable sources, with Norway deriving more than 95% from hydropower. This clean energy dominance enables operators to secure power at average costs 20–30% lower than major Western European markets, creating a compelling value proposition that balances sustainability with cost efficiency. In 2023 alone, data center operators in the region contracted over 2.5 TWh of renewable electricity through long-term power purchase agreements (PPAs), reinforcing their decarbonization commitments and mitigating price volatility.
The capital expenditure profile for Nordic data centers is characterized by high upfront intensity in electrical and cooling infrastructure, offset by long-term operational savings. Developers allocate significant budgets to site preparation, civil construction, and shell works designed for high structural loads and longevity.
| CAPEX Component | Share of Total CAPEX (Typical) | Key Considerations |
|---|---|---|
| Electrical Infrastructure (Switchgear, Transformers, UPS) | 30–35% | Carrier-class redundancy, grid interconnection costs |
| Cooling Systems (Free Cooling, Liquid Cooling) | 15–20% | Energy efficiency, PUE optimization, climate-driven design |
| Civil Construction and Shell | 15–20% | Permitting, land costs, structural requirements |
| IT Hardware (Servers, Storage, Networking) | 20–25% | Rack density, blade server selection, refresh cycles |
| Connectivity (Fiber, Cross-Connects) | 5–10% | Latency requirements, multi-operator ecosystems |
| Soft Costs (Design, Permitting, Legal) | 5–8% | Regulatory complexity, sustainability certifications |
Modular deployment strategies and phased construction are increasingly adopted to alleviate capital strain and accelerate time-to-revenue. Additional budgets may be reserved for renewable energy integration, PPAs, and waste heat recovery connections to municipal district heating systems.
The Nordic data center market is segmented by component, data center type, power capacity, and end user. Our analysis reveals that electrical infrastructure and cooling systems will remain the largest component segments, driven by the need for high availability and energy efficiency.
Sweden currently dominates the Nordic data center market, accounting for approximately 31% of regional capacity, followed by Norway (22%), Finland (19%), Denmark (18%), and Iceland (10%). Sweden’s leadership is attributed to its mature digital economy, robust fiber backbone, and proactive energy policies. Norway benefits from ultra-low hydropower costs, while Finland and Denmark offer strategic connectivity to the Baltic and Central European markets. Iceland, though smaller, provides geothermal and hydro power with exceptional sustainability credentials, attracting niche high-performance computing deployments.
| Country | Market Share (2024) | Key Attractiveness Factors |
|---|---|---|
| Sweden | 31% | Mature ecosystem, renewable energy, connectivity |
| Norway | 22% | Low-cost hydropower, stable grid, data sovereignty |
| Finland | 19% | Cool climate, EU integration, strong ICT sector |
| Denmark | 18% | Wind energy leadership, cross-border connectivity |
| Iceland | 10% | Geothermal energy, 100% renewable grid, niche HPC |
The Nordic data center market is characterized by the presence of global hyperscalers, established colocation providers, and specialized edge operators. Key players are pursuing aggressive expansion strategies to capture growing demand for AI-ready infrastructure.
The Nordics present a compelling investment case for digital infrastructure, driven by the lowest carbon intensity in Europe and long-term energy cost stability. However, investors must navigate grid connection delays and varying regulatory frameworks across the five countries. Sweden and Norway offer the most streamlined pathways for large-scale projects, while Iceland provides unique advantages for sustainability-focused deployments. We assess the region as a high-attractiveness, medium-risk market for data center investment over the next five years, with strong fundamentals supporting continued capital inflows.
The Nordic data center market relies heavily on imported equipment, including servers, storage devices, networking gear, and electrical infrastructure. Intra-EU trade facilitates rapid procurement, while global suppliers from Asia and North America dominate the IT hardware segment. Supply chain risks include semiconductor shortages and logistical bottlenecks, but long-term supplier agreements and regional inventory buffers are mitigating these challenges. Key suppliers include global OEMs and specialized Nordic electrical contractors who provide installation and commissioning services.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2024 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 12.8% from 2020-2034 |
| Segmentation |
|
By Data Center Type
By Power Capacity
By End User
| By Geography |
|
The Nordic data center market was valued at USD 7,160 million in 2024 and is projected to reach USD 14,929 million by 2030, growing at a CAGR of 12.8%.
Sweden holds the largest market share at approximately 31%, followed by Norway at 22%, driven by renewable energy availability and robust connectivity.
Abundant low-cost renewable energy, sustainability mandates, government incentives, and the need for data sovereignty and low-latency processing are key drivers.
The number of operational data centers in the Nordic region is projected to reach 150 by 2028, up from 119 in 2024 and 95 in 2020.
Over 90% of electricity in the Nordics comes from renewable sources, enabling operators to achieve lower power costs and meet decarbonization goals, with over 2.5 TWh of PPAs contracted in 2023 alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| C-Suite (CEO, CTO, COO) | 30% |
| VP/Director of Engineering & Operations | 35% |
| Procurement & Supply Chain Managers | 20% |
| Sustainability & Energy Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Hyperscale & Colocation Operators | 30% |
| Electrical Equipment Manufacturers | 25% |
| Cooling System Specialists | 20% |
| EPC Contractors & Installers | 15% |
| IT Hardware & Networking Vendors | 10% |