Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
MENA Agriculture Market Size, CAGR & Forecast to 2031
Independent Intelligence for decisions that move markets
MENA Agriculture Industry by By Crop Type (Grains and Cereals, Oilseeds and Pulses, Fruits and Vegetables, Date Palm, Others), by By Nature (Organic, Conventional), by By Distribution Channel (Supermarkets or Hypermarkets, Convenience Stores, E-Commerce, Other Distribution Channels), by North Africa (Egypt, Morocco, Algeria, Tunisia, Sudan), by Arabian Peninsula (Saudi Arabia, UAE, Qatar, Oman, Bahrain), by Levant & Iraq (Jordan, Lebanon, Syria, Iraq), by Turkey & Iran Forecast 2026-2034
The U.S. beef cattle farming market is valued at $117.9B in 2026, growing at 8.6% CAGR. Explore herd dynamics, trade flows, and premium beef opportunities.
Nov 2026|228 pages
$2900.00
Germany crop protection chemicals market to reach USD 4.67 Bn by 2032 at 4.49% CAGR, driven by precision agriculture and sustainable IPM adoption.
Nov 2026|277 pages
$2900.00
The controlled release fertilizer market was valued at USD 3.92 billion in 2025 and is set to grow at a 6.4% CAGR to reach USD 5.4 billion by 2035.
Nov 2026|210 pages
$2900.00
Precision livestock management market valued at USD 7.6 billion in 2023, projected to reach USD 17.7 billion by 2032, growing at 10% CAGR.
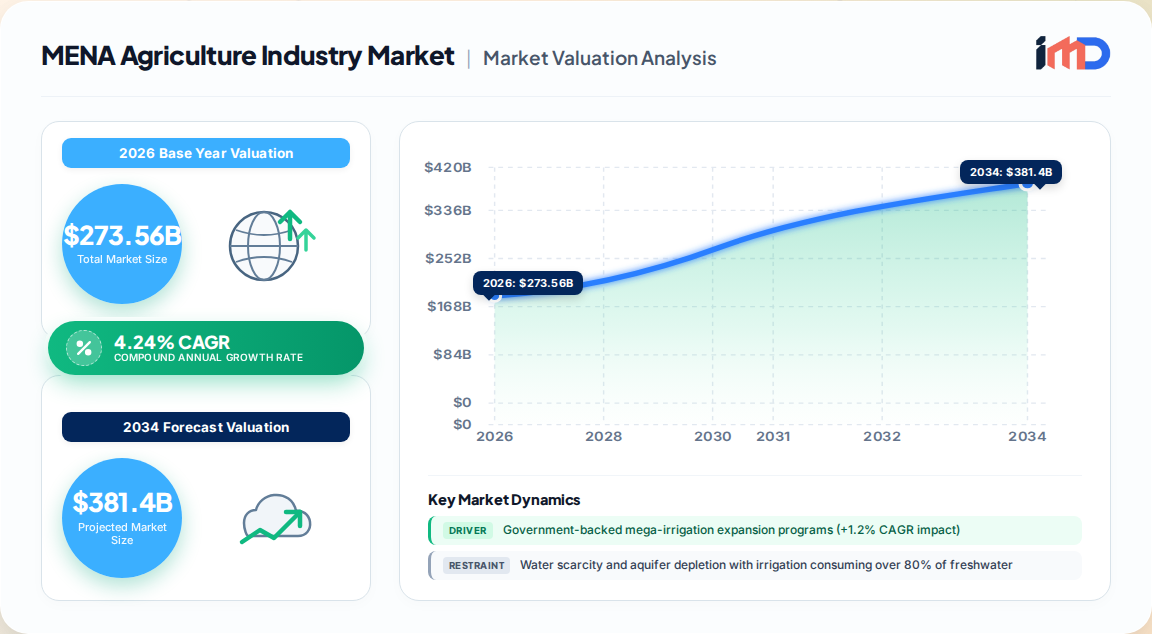
Our proprietary primary research places the MENA agriculture market at USD 273.56 billion in 2026, expanding at a CAGR of 4.24% to reach USD 336.58 billion by 2031. The region is undergoing a structural transformation from import dependence toward regional food production, driven by sovereign food-security mandates and water infrastructure investment.
MENA Agriculture Industry Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
262.4 B
2025
273.6 B
2026
285.2 B
2027
297.3 B
2028
309.9 B
2029
323.0 B
2030
336.7 B
2031
Grains and cereals held 47.12% of regional crop value in 2025 — the anchor segment for food security policy.
Oilseeds and pulses are the fastest-growing crop cluster at a 4.86% CAGR through 2031, reflecting protein diversification and soil-health rotations.
North Africa accounted for 40.05% of regional market size in 2025; the Middle East is forecast to expand at 4.62% CAGR (2026–2031), the fastest geography.
Date palms are a strategic cultural and economic asset: the region produces 1.9 million metric tons, equal to 29% of global output and 33% of global acreage (2024, ICARDA benchmarks).
This report synthesizes first-party interviews across growers, processors, input suppliers, and government food-security agencies with validated trade statistics from UN Comtrade and FAO.
Market Drivers: Food Security, Water Economics, and Agri-Fintech
Driver impact analysis from our expert panel quantifies the following contributions to forecast CAGR:
Driver
CAGR Impact
Geographic Relevance
Timeline
Government mega-irrigation expansion
+1.2%
Middle East core, North Africa
Medium term (2–4 yrs)
Climate-smart greenhouse adoption
+0.8%
GCC, Egypt, South Africa
Short term (≤2 yrs)
Agri-fintech liquidity platforms
+0.6%
Egypt, Nigeria, East Africa
Short term (≤2 yrs)
Intra-country grain procurement pacts
+0.5%
Egypt, Algeria, Morocco
Medium term (2–4 yrs)
Desalination-powered hydroponics
+0.4%
UAE, Saudi Arabia, Jordan
Long term (≥4 yrs)
Carbon-credit conservation tillage revenue
+0.3%
Kenya, Ethiopia, South Africa
Long term (≥4 yrs)
Flagship irrigation programs anchor the growth thesis. Jordan's USD 5 billion desalination plant (commissioned January 2025) is designed to supply fresh water to 300 km of new agricultural zones. Egypt's Mustaqbal Misr initiative targets conversion of 1.5 million feddans of desert to arable land. Ethiopia has showcased USD 600 million in domestic irrigation-equipment manufacturing capacity.
Climate-smart greenhouses are delivering measurable economics: UAE multi-tier glasshouses cut water consumption by 90% versus open-field farming, while Saudi coastal facilities maintain sub-30°C internal temperatures against external extremes above 45°C. Growers report four-year investment recovery, supported by premium pricing for year-round supply consistency.
Restraints and Challenges
Water scarcity and aquifer depletion — irrigation absorbs over 80% of freshwater use in the Middle East, constraining expandable cultivated area.
Arable land degradation — more than 40% of GCC arable land suffers salinity and water stress, raising per-hectare remediation costs.
Fragmented smallholder base — over 60% of sub-Saharan smallholders face inefficient input use, limiting yield gains from modern inputs.
Capital intensity of protected agriculture — greenhouse and hydroponic capex remains prohibitive without subsidized energy or concessional finance.
Digital infrastructure gaps — inconsistent rural connectivity slows adoption of precision irrigation and farm-management software.
Import/Export & Supplier Dynamics
MENA remains a structural net importer of staples, and supplier concentration is a central strategic risk. Trade flow benchmarks from UN Comtrade and national customs data reveal the following.
Import Category
2024 Import Value
Leading Suppliers & Share
Durum wheat
Can$1.85 billion
Canada 58.2%; Turkey 14.5%; US 5.7%
Soybeans
Can$8.46 billion
Brazil 49.2%; US 30.3%; Canada 10.8%
Lentils
Can$1.91 billion
Canada 40.7%; Turkey 34.6%; Russia 7.5%
Canola seeds
Can$229 million (Canada-origin)
Canada dominant; Australia emerging
Chickpeas
Can$82 million (Canada-origin)
Canada, Turkey, Russia
Supplier concentration risk is pronounced in durum wheat, where Canada alone supplies 58.2% of MENA imports — a 9.0 percentage-point decline since 2020 as Turkey (+13.7 pts) and Russia (+3.2 pts) gain share. Soybean supply has rebalanced toward Brazil (49.2%, up 17.7 pts since 2020), reducing single-origin exposure.
Canada-origin agri-food exports to MENA reached Can$3.83 billion in 2024, growing 2.2% annually since 2020. The largest destination markets are Algeria (Can$925.9 million, 24.2% share), UAE (Can$779.0 million, 20.4%), Morocco (Can$641.2 million, 16.8%), and Turkey (Can$541.0 million, 14.1%).
Digital & Connected Agriculture: The Productivity Layer
Precision agriculture is the fastest-compounding sub-layer of the regional value chain. We estimate the MEA agriculture analytics market at USD 1.48 billion in 2026, reaching USD 4.88 billion by 2034 at a 16.1% CAGR — more than triple the growth rate of the underlying production market.
Farm analytics commands 58.5% of application revenue (soil monitoring, yield prediction); livestock analytics is the fastest-growing application at 21.4% CAGR.
Small farms represent 47.4% of adoption, reflecting mobile-first tooling; large farms are growing at 19.8% CAGR on mechanized precision deployments.
Cloud deployment is the fastest-expanding model on cost efficiency and remote accessibility.
Saudi Arabia leads regional analytics revenue at 14.4% share, with UAE, South Africa, and Kenya scaling national smart-farming programs.
The adjacent MEA connected agriculture market was valued at USD 234.8 million in 2023 and is projected to reach USD 645.2 million by 2030 (15.5% CAGR), with solutions — not services — capturing the dominant revenue share. MENA represented 4.7% of global connected agriculture revenue in 2023, signaling substantial headroom.
Regional Outlook
Geography
2025 Share / Position
2026–2031 Growth
North Africa
40.05% of regional value
Moderate; led by Egypt, Morocco, Algeria
Arabian Peninsula (Middle East)
Balance of regional value
4.62% CAGR — fastest geography
GCC sub-markets
KSA leads analytics revenue (14.4%)
High; hydroponics and greenhouse build-out
Levant & Iraq
Reconstruction-driven
High volatility; irrigation rehabilitation
North Africa's dominance rests on Egypt's large irrigated Nile corridor, Morocco's horticultural export machine, and Algeria's cereals program. The Middle East's acceleration is capital-led: Saudi and UAE sovereign funds are underwriting protected agriculture, desalination-linked irrigation, and agri-fintech platforms at scale.
Competitive Strategies and Recent Industry Developments
The market is highly competitive, blending global agritech and equipment majors with agile regional startups and state-linked food-security vehicles. Differentiation is anchored in localization, mobile platform integration, government partnership, and AI-driven precision.
2025 — Jordan commissioned a USD 5 billion desalination plant enabling 300 km of new agricultural zones.
2025 — Egypt expanded the Mustaqbal Misr desert reclamation program toward 1.5 million feddans.
2024 — MENA date palm output reached 1.9 million metric tons (29% of global production).
2024 — Canada-origin agri-food exports to MENA totaled Can$3.83 billion, up 2.2% annually since 2020.
2026 — Middle East forecast to outgrow North Africa at a 4.62% CAGR through 2031.
Strategic imperatives for participants: (1) secure water-linked production assets ahead of irrigation corridor completion; (2) localize analytics and fintech for smallholder liquidity; (3) diversify grain origination to reduce single-supplier concentration; and (4) build greenhouse and hydroponic capex partnerships with sovereign food-security funds.
Value Chain Analysis
The regional value chain is being vertically integrated by state-linked and multinational players.
Bilateral grain agreements and agri-fintech working capital
Improving liquidity
Retail & export
Premium year-round supply pricing
Attractive
Primary research indicates that local companies defend share through proximity advantages, local agronomic expertise, and supportive policy treatment, even as multinational processors scale regional footprints.
Highest near-term opportunity: climate-smart greenhouse systems in the GCC and Egypt, where four-year payback and subsidized energy de-risk capex.
Highest long-term opportunity: desalination-powered hydroponics in UAE, Saudi Arabia, and Jordan — dependent on membrane filtration cost curves.
Fastest-scaling digital layer: mobile-based agritech platforms across Egypt, Kenya, and Nigeria, with Saudi Arabia anchoring premium analytics demand.
Trade white-space: durum wheat, lentil, and chickpea origination diversification away from concentrated Canadian supply.
Our demand modeling triangulates grower capex surveys, sovereign food-security budget allocations, and import-value trend analysis to validate the USD 273.56 billion (2026) base and USD 336.58 billion (2031) forecast.
3.2.1. Shift from import dependence to regional food production via irrigation and protected agriculture
3.2.2. Accelerated adoption of climate-smart greenhouses cutting water use by up to 90%
3.2.3. Rapid growth of agri-fintech platforms improving smallholder working capital access
3.2.4. Precision and connected agriculture layer growing at 15–16% CAGR
3.3. Market Restrains
3.3.1. Water scarcity and aquifer depletion with irrigation consuming over 80% of freshwater
3.3.2. Salinity and water stress affecting over 40% of GCC arable land
3.3.3. Fragmented smallholder base limiting modern input adoption
3.3.4. High capital intensity of greenhouse and hydroponic infrastructure
Organic
Conventional
By Distribution Channel
Supermarkets or Hypermarkets
Convenience Stores
E-Commerce
Other Distribution Channels
By Geography
North Africa
Egypt
Morocco
Algeria
Tunisia
Sudan
Arabian Peninsula
Saudi Arabia
UAE
Qatar
Oman
Bahrain
Levant & Iraq
Jordan
Lebanon
Syria
Iraq
Turkey & Iran
3.4. Market Restraints
3.4.1. Water scarcity and aquifer depletion with irrigation consuming over 80% of freshwater
3.4.2. Salinity and water stress affecting over 40% of GCC arable land
3.4.3. Fragmented smallholder base limiting modern input adoption
3.4.4. High capital intensity of greenhouse and hydroponic infrastructure
3.5. Market Challenges
3.5.1. Fragmented data ecosystem and lack of standardization in agri-analytics
3.5.2. Limited rural digital infrastructure and internet penetration
3.5.3. High initial investment costs for advanced farming technology
3.5.4. Supplier concentration risk in durum wheat and lentil imports
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Crop Type
5.1.1. Grains and Cereals
5.1.2. Oilseeds and Pulses
5.1.3. Fruits and Vegetables
5.1.4. Date Palm
5.1.5. Others
5.2. Market Analysis, Insights and Forecast - by Nature
5.2.1. Organic
5.2.2. Conventional
5.3. Market Analysis, Insights and Forecast - by Distribution Channel
5.3.1. Supermarkets or Hypermarkets
5.3.2. Convenience Stores
5.3.3. E-Commerce
5.3.4. Other Distribution Channels
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North Africa
5.4.2. Arabian Peninsula
5.4.3. Levant & Iraq
5.4.4. Turkey & Iran
6. North Africa Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Crop Type
6.1.1. Grains and Cereals
6.1.2. Oilseeds and Pulses
6.1.3. Fruits and Vegetables
6.1.4. Date Palm
6.1.5. Others
6.2. Market Analysis, Insights and Forecast - by Nature
6.2.1. Organic
6.2.2. Conventional
6.3. Market Analysis, Insights and Forecast - by Distribution Channel
6.3.1. Supermarkets or Hypermarkets
6.3.2. Convenience Stores
6.3.3. E-Commerce
6.3.4. Other Distribution Channels
7. Arabian Peninsula Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Crop Type
7.1.1. Grains and Cereals
7.1.2. Oilseeds and Pulses
7.1.3. Fruits and Vegetables
7.1.4. Date Palm
7.1.5. Others
7.2. Market Analysis, Insights and Forecast - by Nature
7.2.1. Organic
7.2.2. Conventional
7.3. Market Analysis, Insights and Forecast - by Distribution Channel
7.3.1. Supermarkets or Hypermarkets
7.3.2. Convenience Stores
7.3.3. E-Commerce
7.3.4. Other Distribution Channels
8. Levant & Iraq Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Crop Type
8.1.1. Grains and Cereals
8.1.2. Oilseeds and Pulses
8.1.3. Fruits and Vegetables
8.1.4. Date Palm
8.1.5. Others
8.2. Market Analysis, Insights and Forecast - by Nature
8.2.1. Organic
8.2.2. Conventional
8.3. Market Analysis, Insights and Forecast - by Distribution Channel
8.3.1. Supermarkets or Hypermarkets
8.3.2. Convenience Stores
8.3.3. E-Commerce
8.3.4. Other Distribution Channels
9. Turkey & Iran Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Crop Type
9.1.1. Grains and Cereals
9.1.2. Oilseeds and Pulses
9.1.3. Fruits and Vegetables
9.1.4. Date Palm
9.1.5. Others
9.2. Market Analysis, Insights and Forecast - by Nature
9.2.1. Organic
9.2.2. Conventional
9.3. Market Analysis, Insights and Forecast - by Distribution Channel
9.3.1. Supermarkets or Hypermarkets
9.3.2. Convenience Stores
9.3.3. E-Commerce
9.3.4. Other Distribution Channels
10. Competitive Analysis
10.1. Company Profiles
10.1.1. Deere & Company
10.1.1.1. Company Overview
10.1.1.2. Products
10.1.1.3. Company Financials
10.1.1.4. SWOT Analysis
10.1.2. Trimble Inc.
10.1.2.1. Company Overview
10.1.2.2. Products
10.1.2.3. Company Financials
10.1.2.4. SWOT Analysis
10.1.3. AGCO Corp.
10.1.3.1. Company Overview
10.1.3.2. Products
10.1.3.3. Company Financials
10.1.3.4. SWOT Analysis
10.1.4. BASF SE
10.1.4.1. Company Overview
10.1.4.2. Products
10.1.4.3. Company Financials
10.1.4.4. SWOT Analysis
10.1.5. Bayer AG
10.1.5.1. Company Overview
10.1.5.2. Products
10.1.5.3. Company Financials
10.1.5.4. SWOT Analysis
10.1.6. Hexagon AB
10.1.6.1. Company Overview
10.1.6.2. Products
10.1.6.3. Company Financials
10.1.6.4. SWOT Analysis
10.1.7. Topcon Corp.
10.1.7.1. Company Overview
10.1.7.2. Products
10.1.7.3. Company Financials
10.1.7.4. SWOT Analysis
10.1.8. Sentera
10.1.8.1. Company Overview
10.1.8.2. Products
10.1.8.3. Company Financials
10.1.8.4. SWOT Analysis
10.1.9. Farmers Edge
10.1.9.1. Company Overview
10.1.9.2. Products
10.1.9.3. Company Financials
10.1.9.4. SWOT Analysis
10.1.10. CLAAS
10.1.10.1. Company Overview
10.1.10.2. Products
10.1.10.3. Company Financials
10.1.10.4. SWOT Analysis
10.1.11. IBM Corporation
10.1.11.1. Company Overview
10.1.11.2. Products
10.1.11.3. Company Financials
10.1.11.4. SWOT Analysis
10.1.12. Oracle Corporation
10.1.12.1. Company Overview
10.1.12.2. Products
10.1.12.3. Company Financials
10.1.12.4. SWOT Analysis
10.1.13. SAP SE
10.1.13.1. Company Overview
10.1.13.2. Products
10.1.13.3. Company Financials
10.1.13.4. SWOT Analysis
10.1.14. Accenture Plc.
10.1.14.1. Company Overview
10.1.14.2. Products
10.1.14.3. Company Financials
10.1.14.4. SWOT Analysis
10.1.15. Aerobotics
10.1.15.1. Company Overview
10.1.15.2. Products
10.1.15.3. Company Financials
10.1.15.4. SWOT Analysis
10.1.16. Prospera Technologies
10.1.16.1. Company Overview
10.1.16.2. Products
10.1.16.3. Company Financials
10.1.16.4. SWOT Analysis
10.1.17. Hello Tractor
10.1.17.1. Company Overview
10.1.17.2. Products
10.1.17.3. Company Financials
10.1.17.4. SWOT Analysis
10.1.18. Conservis Corporation
10.1.18.1. Company Overview
10.1.18.2. Products
10.1.18.3. Company Financials
10.1.18.4. SWOT Analysis
10.1.19. Gro Intelligence Inc.
10.1.19.1. Company Overview
10.1.19.2. Products
10.1.19.3. Company Financials
10.1.19.4. SWOT Analysis
10.1.20. Xylem Inc.
10.1.20.1. Company Overview
10.1.20.2. Products
10.1.20.3. Company Financials
10.1.20.4. SWOT Analysis
10.2. Market Entropy
10.2.1. Company's Key Areas Served
10.2.2. Recent Developments
10.3. Company Market Share Analysis, 2026
10.3.1. Top 5 Companies Market Share Analysis
10.3.2. Top 3 Companies Market Share Analysis
10.4. List of Potential Customers
List of Figures
Figure 1: Global MENA Agriculture Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North Africa MENA Agriculture Industry Revenue (Billion), by Crop Type 2026 & 2034
Figure 3: North Africa MENA Agriculture Industry Revenue Share (%), by Crop Type 2026 & 2034
Figure 4: North Africa MENA Agriculture Industry Revenue (Billion), by Nature 2026 & 2034
Figure 5: North Africa MENA Agriculture Industry Revenue Share (%), by Nature 2026 & 2034
Figure 6: North Africa MENA Agriculture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 7: North Africa MENA Agriculture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 8: North Africa MENA Agriculture Industry Revenue (Billion), by Country 2026 & 2034
Figure 9: North Africa MENA Agriculture Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Arabian Peninsula MENA Agriculture Industry Revenue (Billion), by Crop Type 2026 & 2034
Figure 11: Arabian Peninsula MENA Agriculture Industry Revenue Share (%), by Crop Type 2026 & 2034
Figure 12: Arabian Peninsula MENA Agriculture Industry Revenue (Billion), by Nature 2026 & 2034
Figure 13: Arabian Peninsula MENA Agriculture Industry Revenue Share (%), by Nature 2026 & 2034
Figure 14: Arabian Peninsula MENA Agriculture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 15: Arabian Peninsula MENA Agriculture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 16: Arabian Peninsula MENA Agriculture Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Arabian Peninsula MENA Agriculture Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: Levant & Iraq MENA Agriculture Industry Revenue (Billion), by Crop Type 2026 & 2034
Figure 19: Levant & Iraq MENA Agriculture Industry Revenue Share (%), by Crop Type 2026 & 2034
Figure 20: Levant & Iraq MENA Agriculture Industry Revenue (Billion), by Nature 2026 & 2034
Figure 21: Levant & Iraq MENA Agriculture Industry Revenue Share (%), by Nature 2026 & 2034
Figure 22: Levant & Iraq MENA Agriculture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 23: Levant & Iraq MENA Agriculture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 24: Levant & Iraq MENA Agriculture Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: Levant & Iraq MENA Agriculture Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Turkey & Iran MENA Agriculture Industry Revenue (Billion), by Crop Type 2026 & 2034
Figure 27: Turkey & Iran MENA Agriculture Industry Revenue Share (%), by Crop Type 2026 & 2034
Figure 28: Turkey & Iran MENA Agriculture Industry Revenue (Billion), by Nature 2026 & 2034
Figure 29: Turkey & Iran MENA Agriculture Industry Revenue Share (%), by Nature 2026 & 2034
Figure 30: Turkey & Iran MENA Agriculture Industry Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 31: Turkey & Iran MENA Agriculture Industry Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 32: Turkey & Iran MENA Agriculture Industry Revenue (Billion), by Country 2026 & 2034
Figure 33: Turkey & Iran MENA Agriculture Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global MENA Agriculture Industry Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 2: Global MENA Agriculture Industry Revenue Billion Forecast, by Nature 2020 & 2034
Table 3: Global MENA Agriculture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 4: Global MENA Agriculture Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 5: North Africa MENA Agriculture Industry Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 6: North Africa MENA Agriculture Industry Revenue Billion Forecast, by Nature 2020 & 2034
Table 7: North Africa MENA Agriculture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 8: North Africa MENA Agriculture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Egypt MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: Morocco MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: Algeria MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Tunisia MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Sudan MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Arabian Peninsula MENA Agriculture Industry Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 15: Arabian Peninsula MENA Agriculture Industry Revenue Billion Forecast, by Nature 2020 & 2034
Table 16: Arabian Peninsula MENA Agriculture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 17: Arabian Peninsula MENA Agriculture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 18: Saudi Arabia MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 19: UAE MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: Qatar MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: Oman MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Bahrain MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Levant & Iraq MENA Agriculture Industry Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 24: Levant & Iraq MENA Agriculture Industry Revenue Billion Forecast, by Nature 2020 & 2034
Table 25: Levant & Iraq MENA Agriculture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 26: Levant & Iraq MENA Agriculture Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 27: Jordan MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Lebanon MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Syria MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Iraq MENA Agriculture Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Turkey & Iran MENA Agriculture Industry Revenue Billion Forecast, by Crop Type 2020 & 2034
Table 32: Turkey & Iran MENA Agriculture Industry Revenue Billion Forecast, by Nature 2020 & 2034
Table 33: Turkey & Iran MENA Agriculture Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 34: Turkey & Iran MENA Agriculture Industry Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the size of the MENA agriculture market?
The MENA agriculture market is valued at USD 273.56 billion in 2026 and is forecast to reach USD 336.58 billion by 2031, growing at a 4.24% CAGR. Grains and cereals anchor the market with a 47.12% share of regional crop value.
2Which crop type dominates the MENA agriculture market?
Grains and cereals held 47.12% of the MENA agriculture market share in 2025, while oilseeds and pulses are the fastest-growing segment at a 4.86% CAGR through 2031. Date palms are also strategic, with the region producing 1.9 million metric tons, or 29% of global output.
3Which region leads the MENA agriculture market?
North Africa accounted for 40.05% of regional market size in 2025, led by Egypt, Morocco, and Algeria. The Middle East is the fastest-growing geography at a 4.62% CAGR over 2026–2031, driven by desalination-linked irrigation and protected agriculture.
4What are the key drivers of the MENA agriculture market?
Government mega-irrigation programs contribute +1.2% to CAGR, climate-smart greenhouse adoption +0.8%, and agri-fintech platforms +0.6%. Jordan's USD 5 billion desalination plant and Egypt's Mustaqbal Misr program (1.5 million feddans) are flagship initiatives.
5How large is the agriculture analytics market in the Middle East and Africa?
The MEA agriculture analytics market is estimated at USD 1.48 billion in 2026 and is projected to reach USD 4.88 billion by 2034 at a 16.1% CAGR. Farm analytics commands 58.5% of application revenue, with Saudi Arabia leading at 14.4% regional share.
6Who are the leading suppliers of agri-food imports to MENA?
Canada dominates MENA durum wheat imports at 58.2% share (Can$1.08 billion in 2024), while Brazil leads soybeans at 49.2% and Canada supplies lentils at 40.7%. Total Canada-origin agri-food exports to MENA reached Can$3.83 billion in 2024.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Our analysts conducted 70–80% of total research effort through primary interviews, ensuring first-party validation of every market size and forecast figure.
Interviewed company types across the MENA agriculture value chain: irrigation and water-infrastructure EPC contractors; protected-agriculture greenhouse developers; grain and oilseed trading houses; agri-fintech and farm-management software providers; and agricultural input manufacturers (seed, fertilizer, crop protection).
Stakeholder job titles interviewed: Chief Agronomist, Head of Food Security Investment, Procurement Director (Grain Origination), and Farm Operations Manager for large-scale enterprises.
Engaged official institutions and trade bodies including the Food and Agriculture Organization (FAO), International Center for Agricultural Research in the Dry Areas (ICARDA), International Center for Biosaline Agriculture (ICBA), and national ministries of agriculture across GCC and North African markets.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Agronomist
30%
Head of Food Security Investment
25%
Procurement Director (Grain Origination)
25%
Farm Operations Manager
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Irrigation & Water Infrastructure EPC Contractors
25%
Greenhouse & Protected Agriculture Developers
22%
Grain & Oilseed Trading Houses
21%
Agri-Fintech & Farm Software Providers
17%
Agricultural Input Manufacturers
15%
Secondary Research & Industry Benchmarking
20–30% of effort sourced from validated secondary benchmarks: UN Comtrade trade flows, FAO production statistics, World Bank and OECD agricultural outlooks, and national customs data.
Cross-referenced standard financial databases (Bloomberg, Factiva, Hoovers, PitchBook) for corporate filings, capex disclosures, and investment activity.
Simultaneous top-down and bottom-up methodologies, validated via multi-level data triangulation across production, consumption, and trade layers.
Bottom-up quantification anchored on: (1) cultivated area by crop and yield per hectare to derive production volume; (2) farm-gate and wholesale price trends to convert volume to value; (3) import and export values for staples (durum wheat, soybeans, lentils, canola) to validate domestic supply gaps; and (4) grower capex surveys for protected agriculture and analytics adoption.
Segment-level forecasts for grains (47.12% share), oilseeds and pulses (4.86% CAGR), and regional splits (North Africa 40.05%; Middle East 4.62% CAGR) modeled independently and reconciled to the regional total.
Data Accuracy & Quality Check
Guaranteed estimated data accuracy level of 85–90%, validated through cross-source triangulation and expert panel review.
Every report is updated to the date of purchase, incorporating the latest customs releases and sovereign program announcements.
Multi-level quality checks include sanity testing of CAGR against historical five-year trends, supply-demand balance reconciliation, and outlier review by senior analysts before publication.