Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Medium Voltage Switchgears: A Technology Perspective
Manufacturing Products and Services / MARKET REPORT
Medium Voltage Switchgears: A Technology Perspective | Insight Market Data
Medium Voltage Switchgears: A Technology Perspective by Insulation (Air Insulated Switchgear, Gas Insulated Switchgear, Others(SF6-Free, Solid-Dielectric)), by Current Type (AC Switchgear, DC Switchgear), by Installation (Indoor, Outdoor), by Voltage Range (3 kV - 9 kV, 9 kV - 15 kV, 15 kV - 21 kV, 21 kV - 27 kV, 27 kV - 33 kV, Above 33 kV), by End-User (Utilities, Residential, Commercial, Industrial), by Component (Circuit Breakers, Contactors, Switches & Disconnectors, Fuses, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Australia), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA), by South America (Brazil, Argentina, Mexico, Rest of South America) Forecast 2026-2034
PC industry market to grow at 8.98% CAGR from USD 242.63 Bn in 2026 to USD 372.68 Bn by 2031, fueled by AI-enabled upgrades and Windows 10 EOL refresh.
The Kamado Grill Market is valued at USD 12.04 Billion in 2026, growing at a 5.6% CAGR to reach USD 20.76 Billion by 2036, driven by premium outdoor cooking.
Nov 2026|236 pages
$2900.00
Nursing education market valued at USD 26.6 billion in 2024, growing at 6.4% CAGR to reach USD 49.4 billion by 2034 amid global nurse shortages.
Nov 2026|259 pages
$2900.00
Regulatory T cell market to grow from USD 2.77 Billion in 2025 at a 40.0% CAGR, driven by autoimmune, transplant and CAR-Treg pipelines.
Nov 2026|277 pages
$2900.00
The cellular baseband chips market is valued at USD 1.97 billion in 2025 and is projected to reach USD 3.77 billion by 2032, growing at a CAGR of 9.70%.
Executive Overview: The Technology-Driven Evolution of MV Switchgear
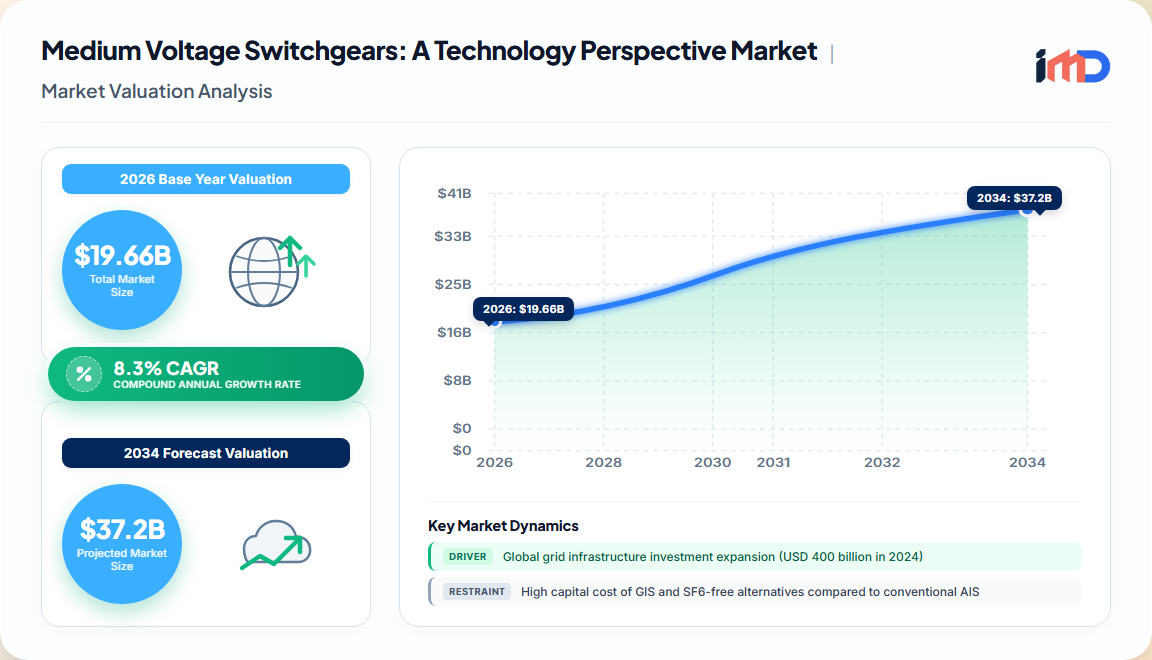
The global medium voltage (MV) switchgear market is undergoing a fundamental technology shift, moving from passive electromechanical hardware to intelligent, eco-efficient, and digitally integrated grid assets. Our proprietary primary research estimates the market at USD 19.66 billion in 2026, projected to reach USD 40.25 billion by 2035, expanding at a CAGR of 8.3%. This growth is not merely volume-led; it is increasingly value-driven by specification upgrades, regulatory mandates, and the integration of renewable and distributed energy resources (DERs).
Medium Voltage Switchgears: A Technology Perspective Market Size (In Billion)
30.0B
20.0B
10.0B
0
18.15 B
2025
19.66 B
2026
21.29 B
2027
23.06 B
2028
24.97 B
2029
27.05 B
2030
29.29 B
2031
The MV switchgear domain, covering equipment rated from 1 kV to 52 kV, sits at the critical intersection of transmission and distribution. Technology now determines market competitiveness as much as price and lead time. Three technology vectors dominate: the phase-out of SF6 insulation, the rise of digital substations with IEC 61850 interoperability, and the adoption of solid-state and hybrid switching architectures. These shifts are reshaping product portfolios, supply chains, and competitive positioning across utilities, industry, and commercial end-users.
Key Technology Trends Reshaping MV Switchgear
The technology landscape is being redrawn by regulatory, environmental, and operational imperatives. Based on our primary interviews and supply-side analysis, the following trends are most impactful for the 2026-2035 forecast period.
SF6-Free Insulation Transition: The EU Regulation 2024/573 bans SF6 in new MV switchgear ≤24 kV from January 2026, extending to ≤52 kV by 2030. This is accelerating adoption of vacuum interruption, solid-dielectric, and clean-air (fluoronitrile) technologies. SF6-free alternatives are forecast to grow at a 10.5% CAGR through 2035, albeit from a smaller base, with cost premiums of 8-12% currently accepted by early adopters.
Digitalization and IoT Integration: Smart switchgear with embedded sensors, condition monitoring, and remote diagnostics is becoming standard in utility and industrial procurement. These features enable predictive maintenance, reducing unplanned outages by 20-30% and cutting commissioning time by up to 40%. The shift raises average selling prices and strengthens service-based business models.
Compact Gas-Insulated Switchgear (GIS) for Space-Constrained Applications: GIS reduces footprint by up to 60% versus air-insulated switchgear (AIS), driving adoption in urban micro-substations, data centers, and underground networks. In North America, GIS is the fastest-growing insulation segment at a 9.2% CAGR, albeit from a smaller share than AIS.
DC Switchgear for Data Centers and EV Charging: Direct-current architectures, particularly 48 VDC and 380 VDC in hyperscale data centers, are creating a new product category. DC variants are growing at a 6.3% CAGR, with early adoption in North America and Europe.
Solid-State Switching Emergence: While still niche, solid-state and hybrid switching technologies promise faster fault clearing and reduced maintenance. We expect commercialization to accelerate post-2030, posing a long-term disruptive threat to conventional mechanical breakers.
Technology Vector
2025 Share (Est.)
2035 Growth Outlook
Key Driver
Air-Insulated Switchgear (AIS)
43.1%
Moderate (replacement-driven)
Cost, familiarity
Gas-Insulated Switchgear (GIS)
~26%
High (9.2% CAGR NA)
Space constraints, reliability
SF6-Free Alternatives
~15%
Very High (10.5% CAGR)
EU regulation, ESG mandates
DC Switchgear
~4%
High (6.3% CAGR)
Data centers, EV charging
Solid-State/Hybrid
<2%
Emerging
Performance, longevity
Market Drivers and Restraints: A Technology-Centric View
Drivers
Grid Infrastructure Investment Expansion: Global grid spending reached USD 400 billion in 2024, according to the International Energy Agency, driving procurement of MV protection and control equipment. Sustained modernization programs in Europe, North America, and China underpin volume growth.
Renewable Integration and Grid Connection Buildout: Global renewable capacity additions hit 585 GW in 2024 (IRENA). Each generation connection point requires MV switchgear, multiplying demand per GW added. This is especially pronounced in Asia-Pacific and Europe.
Smart Grid Digitalization Mandates: Utility modernization programs mandating IEC 61850 protocols and IoT condition monitoring are shifting procurement toward higher-specification, intelligent switchgear. This supports average value growth beyond headline volume gains.
Urban Reliability and Micro-Substation Build-out: Dense cities are deploying compact GIS in micro-substations to curb outages and hide equipment. Con Edison's USD 5 billion plan in New York and London's GBP 3 billion undergrounding program are prime examples.
Restraints
Developing-Market Investment Shortfall: Reaching net-zero power grids by 2030 requires USD 811 billion in annual grid investment, nearly three times current flows, per BloombergNEF. A persistent gap in emerging economies constrains utility procurement budgets, limiting MV switchgear rollout in MEA, Latin America, and parts of Southeast Asia.
Grid Connection Queue Congestion: Renewable capacity waiting for grid connections reached 1,650 GW by July 2024 (IEA), creating procurement timing uncertainty and slowing order conversion for manufacturers.
SF6 Phase-Out Compliance Complexity: Manufacturers face product redesign, re-certification, and inventory transition costs. Buyers may defer procurement during the technology substitution period, moderating near-term growth.
High Capex of GIS vs AIS: While GIS offers superior performance, its higher upfront cost remains a barrier in price-sensitive markets, particularly in developing regions.
Value Chain and Supply-Side Dynamics
The MV switchgear value chain is undergoing realignment as technology complexity increases and regulatory pressures mount. Our analysis identifies distinct stages and competitive dynamics.
Upstream Materials and Components: Key inputs include vacuum interrupters, protection relays, sensors, and insulation gases or solid dielectrics. The shift to SF6-free alternatives is creating new supplier ecosystems around g3 (fluoronitrile) and clean-air technologies, with limited licensing currently concentrated among a few technology leaders.
Midstream Manufacturing and Assembly: Panel builders and OEMs integrate components into switchgear assemblies. Manufacturing is increasingly modular, with factory-built yards shortening construction schedules by 20-30%. Localization is rising in North America and Europe due to supply chain resilience concerns.
Downstream Distribution and Service: Utilities and industrial end-users demand lifecycle services, including commissioning, maintenance, and retrofit. This has elevated the importance of service networks as a competitive differentiator, with top suppliers generating a growing share of revenue from services.
Supplier Landscape: The market is moderately concentrated, with the top five players holding approximately 55% share in 2025. Supply relationships are characterized by long qualification cycles, especially in utility segments, and growing scrutiny of environmental credentials.
Regional Technology Adoption and Market Outlook
Asia-Pacific remains the largest and fastest-growing region, accounting for 40.3% of 2025 revenue and projected to grow at a 6.8% CAGR through 2031. China, India, and ASEAN drive demand through massive grid investments and renewable buildout. Technology adoption is mixed: price sensitivity sustains AIS demand, but urban density and reliability requirements are accelerating GIS and digital switchgear uptake.
Medium Voltage Switchgears: A Technology Perspective Regional Market Share
Loading chart...
North America is a technology frontrunner, valued at USD 9.77 billion in 2025 and projected to reach USD 16.79 billion by 2034 at a 6.2% CAGR. The U.S. accounts for 92.1% of regional revenue. Aging infrastructure replacement, smart grid initiatives, and data center growth are key. GIS is the fastest-growing insulation type (9.2% CAGR), while circuit breakers dominate the component segment (52.7% share).
Europe is the regulatory pioneer, with the SF6 phase-out driving early adoption of eco-friendly technologies. The region is expected to see strong value growth despite moderate volume gains, as specification upgrades offset slower new-build activity. Offshore wind and undergrounding projects further support demand for marine-rated and compact equipment.
Middle East & Africa is the fastest-growing region by some measures, albeit from a smaller base, as grid investment accelerates. However, investment shortfalls and credit constraints temper the pace. Latin America shows steady growth, with Brazil and Mexico leading, but remains price-sensitive, favoring AIS and cost-effective solutions.
Region
2025 Market Size (USD B)
2035 Forecast (USD B)
CAGR (2026-2035)
Technology Highlights
Asia-Pacific
7.12
16.5
8.8%
GIS, digital, mixed AIS
North America
4.72
9.2
6.9%
GIS, smart grid, data centers
Europe
4.32
8.1
6.5%
SF6-free, offshore wind
Middle East & Africa
1.38
3.6
10.1%
AIS, gradual GIS
South America
1.18
2.8
9.0%
AIS, industrial
Competitive Landscape and Strategic Technology Positioning
The competitive arena is defined by technology leadership, installed-base relationships, and service capability. The top five players—Schneider Electric, Siemens AG, ABB/Hitachi Energy, Eaton, and GE Vernova—collectively held approximately 55% market share in 2025. Schneider Electric led with over 16% share.
Key strategic moves center on:
Portfolio Transition to SF6-Free: ABB's AirPlus and Siemens' Blue GIS are early commercial offerings, with others following. Companies that achieve certification and cost reduction fastest will gain share in Europe and beyond.
Digital Platform Integration: Partnerships with cloud analytics providers and investment in IoT-enabled switchgear are differentiating offerings. Schneider Electric links switchgear to cloud analytics for predictive maintenance, while Siemens Energy embeds sensors for real-time monitoring.
Geographic Expansion and Localization: Manufacturers are localizing production in North America and Europe to mitigate supply chain risks and meet "buy local" mandates. In Asia-Pacific, cost-effective AIS and GIS production is scaling.
Service and Retrofit Solutions: With a large installed base, retrofit and modernization services are a growing revenue stream. Companies offering turnkey lifecycle services are better positioned to capture value.
Recent industry developments include:
2025: Schneider Electric expanded its digital switchgear portfolio with new IoT-enabled MV equipment targeting data centers.
2024: Hitachi Energy launched a new SF6-free switchgear line for offshore wind applications.
2024: Siemens AG announced a manufacturing expansion in the U.S. to meet growing demand for smart switchgear.
2023: Eaton acquired a software company to enhance its grid analytics capabilities.
Import/Export and Global Trade Dynamics
While MV switchgear is primarily assembled and sold regionally due to logistics and customization, trade in components and finished units is significant. Key flows include:
Components: Vacuum interrupters and protection relays are heavily traded, with major production hubs in Europe and Asia. China is a net exporter of components, while the U.S. and Europe import specialized relays and sensors.
Finished Switchgear: Trade is more regionalized. Europe intra-trade is robust, while Asia-Pacific exports to emerging markets in MEA and Latin America.
Tariffs and Localization: Trade policies and local content requirements are influencing sourcing decisions, with manufacturers increasingly establishing local assembly in target markets.
According to our primary research, approximately 30% of MV switchgear components cross borders before final assembly, with supply chain resilience concerns prompting a shift toward regionalization.
Strategic White-Space and Investment Opportunities
Several underpenetrated technology segments offer high growth potential:
SF6-Free Retrofit Solutions: With a large installed base of SF6 equipment, retrofit modules and replacement services represent a significant opportunity, particularly in Europe.
Digital Switchgear for Data Centers: The hyperscale data center boom requires compact, high-reliability GIS and DC switchgear. This is a premium niche with strong growth.
Microgrid and DER Integration: Switchgear designed for bidirectional power flow and seamless islanding is in demand for microgrids and commercial campuses.
Emerging Market Grid Modernization: As investment flows increase, demand for cost-effective, modular, and digital-ready AIS will rise. Local manufacturing and financing solutions will be key to capturing share.
Investors and manufacturers should prioritize technology partnerships, certification pathways for SF6-free products, and service network expansion to capitalize on these opportunities.
Medium Voltage Switchgears: A Technology Perspective Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Medium Voltage Switchgears: A Technology Perspective REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2026
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.3% from 2020-2034
Segmentation
By Insulation
Air Insulated Switchgear
Gas Insulated Switchgear
Others
SF6-Free
Solid-Dielectric
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Global grid infrastructure investment expansion (USD 400 billion in 2024)
3.1.2. Renewable energy integration and grid connection buildout (585 GW added in 2024)
3.1.3. Smart grid digitalization and protection mandates (IEC 61850)
3.1.4. Urban reliability and micro-substation build-out in dense cities
3.2. Market Trends
3.2.1. Transition to SF6-free insulation technologies driven by EU regulations
3.2.2. Digitalization and IoT integration for predictive maintenance and remote diagnostics
3.2.3. Adoption of compact GIS for space-constrained urban and data center applications
3.2.4. Growth of DC switchgear for data centers and EV charging infrastructure
3.3. Market Restrains
3.3.1. High capital cost of GIS and SF6-free alternatives compared to conventional AIS
3.4.3. Investment shortfall in developing economies constraining utility procurement
3.4.4. Supply chain disruptions and material availability challenges
3.5. Market Challenges
3.5.1. Managing technology transition costs and inventory during SF6 phase-out
3.5.2. Meeting diverse regional regulatory requirements for eco-friendly insulation
3.5.3. Ensuring cybersecurity for digital switchgear per IEC 62351
3.5.4. Balancing cost competitiveness with advanced feature integration
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Insulation
5.1.1. Air Insulated Switchgear
5.1.2. Gas Insulated Switchgear
5.1.3. Others
5.1.3.1. SF6-Free
5.1.3.2. Solid-Dielectric
5.2. Market Analysis, Insights and Forecast - by Current Type
5.2.1. AC Switchgear
5.2.2. DC Switchgear
5.3. Market Analysis, Insights and Forecast - by Installation
5.3.1. Indoor
5.3.2. Outdoor
5.4. Market Analysis, Insights and Forecast - by Voltage Range
5.4.1. 3 kV - 9 kV
5.4.2. 9 kV - 15 kV
5.4.3. 15 kV - 21 kV
5.4.4. 21 kV - 27 kV
5.4.5. 27 kV - 33 kV
5.4.6. Above 33 kV
5.5. Market Analysis, Insights and Forecast - by End-User
5.5.1. Utilities
5.5.2. Residential
5.5.3. Commercial
5.5.4. Industrial
5.6. Market Analysis, Insights and Forecast - by Component
5.6.1. Circuit Breakers
5.6.2. Contactors
5.6.3. Switches & Disconnectors
5.6.4. Fuses
5.6.5. Others
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Middle East & Africa
5.7.5. South America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Insulation
6.1.1. Air Insulated Switchgear
6.1.2. Gas Insulated Switchgear
6.1.3. Others
6.1.3.1. SF6-Free
6.1.3.2. Solid-Dielectric
6.2. Market Analysis, Insights and Forecast - by Current Type
6.2.1. AC Switchgear
6.2.2. DC Switchgear
6.3. Market Analysis, Insights and Forecast - by Installation
6.3.1. Indoor
6.3.2. Outdoor
6.4. Market Analysis, Insights and Forecast - by Voltage Range
6.4.1. 3 kV - 9 kV
6.4.2. 9 kV - 15 kV
6.4.3. 15 kV - 21 kV
6.4.4. 21 kV - 27 kV
6.4.5. 27 kV - 33 kV
6.4.6. Above 33 kV
6.5. Market Analysis, Insights and Forecast - by End-User
6.5.1. Utilities
6.5.2. Residential
6.5.3. Commercial
6.5.4. Industrial
6.6. Market Analysis, Insights and Forecast - by Component
6.6.1. Circuit Breakers
6.6.2. Contactors
6.6.3. Switches & Disconnectors
6.6.4. Fuses
6.6.5. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Insulation
7.1.1. Air Insulated Switchgear
7.1.2. Gas Insulated Switchgear
7.1.3. Others
7.1.3.1. SF6-Free
7.1.3.2. Solid-Dielectric
7.2. Market Analysis, Insights and Forecast - by Current Type
7.2.1. AC Switchgear
7.2.2. DC Switchgear
7.3. Market Analysis, Insights and Forecast - by Installation
7.3.1. Indoor
7.3.2. Outdoor
7.4. Market Analysis, Insights and Forecast - by Voltage Range
7.4.1. 3 kV - 9 kV
7.4.2. 9 kV - 15 kV
7.4.3. 15 kV - 21 kV
7.4.4. 21 kV - 27 kV
7.4.5. 27 kV - 33 kV
7.4.6. Above 33 kV
7.5. Market Analysis, Insights and Forecast - by End-User
7.5.1. Utilities
7.5.2. Residential
7.5.3. Commercial
7.5.4. Industrial
7.6. Market Analysis, Insights and Forecast - by Component
7.6.1. Circuit Breakers
7.6.2. Contactors
7.6.3. Switches & Disconnectors
7.6.4. Fuses
7.6.5. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Insulation
8.1.1. Air Insulated Switchgear
8.1.2. Gas Insulated Switchgear
8.1.3. Others
8.1.3.1. SF6-Free
8.1.3.2. Solid-Dielectric
8.2. Market Analysis, Insights and Forecast - by Current Type
8.2.1. AC Switchgear
8.2.2. DC Switchgear
8.3. Market Analysis, Insights and Forecast - by Installation
8.3.1. Indoor
8.3.2. Outdoor
8.4. Market Analysis, Insights and Forecast - by Voltage Range
8.4.1. 3 kV - 9 kV
8.4.2. 9 kV - 15 kV
8.4.3. 15 kV - 21 kV
8.4.4. 21 kV - 27 kV
8.4.5. 27 kV - 33 kV
8.4.6. Above 33 kV
8.5. Market Analysis, Insights and Forecast - by End-User
8.5.1. Utilities
8.5.2. Residential
8.5.3. Commercial
8.5.4. Industrial
8.6. Market Analysis, Insights and Forecast - by Component
8.6.1. Circuit Breakers
8.6.2. Contactors
8.6.3. Switches & Disconnectors
8.6.4. Fuses
8.6.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Insulation
9.1.1. Air Insulated Switchgear
9.1.2. Gas Insulated Switchgear
9.1.3. Others
9.1.3.1. SF6-Free
9.1.3.2. Solid-Dielectric
9.2. Market Analysis, Insights and Forecast - by Current Type
9.2.1. AC Switchgear
9.2.2. DC Switchgear
9.3. Market Analysis, Insights and Forecast - by Installation
9.3.1. Indoor
9.3.2. Outdoor
9.4. Market Analysis, Insights and Forecast - by Voltage Range
9.4.1. 3 kV - 9 kV
9.4.2. 9 kV - 15 kV
9.4.3. 15 kV - 21 kV
9.4.4. 21 kV - 27 kV
9.4.5. 27 kV - 33 kV
9.4.6. Above 33 kV
9.5. Market Analysis, Insights and Forecast - by End-User
9.5.1. Utilities
9.5.2. Residential
9.5.3. Commercial
9.5.4. Industrial
9.6. Market Analysis, Insights and Forecast - by Component
9.6.1. Circuit Breakers
9.6.2. Contactors
9.6.3. Switches & Disconnectors
9.6.4. Fuses
9.6.5. Others
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Insulation
10.1.1. Air Insulated Switchgear
10.1.2. Gas Insulated Switchgear
10.1.3. Others
10.1.3.1. SF6-Free
10.1.3.2. Solid-Dielectric
10.2. Market Analysis, Insights and Forecast - by Current Type
10.2.1. AC Switchgear
10.2.2. DC Switchgear
10.3. Market Analysis, Insights and Forecast - by Installation
10.3.1. Indoor
10.3.2. Outdoor
10.4. Market Analysis, Insights and Forecast - by Voltage Range
10.4.1. 3 kV - 9 kV
10.4.2. 9 kV - 15 kV
10.4.3. 15 kV - 21 kV
10.4.4. 21 kV - 27 kV
10.4.5. 27 kV - 33 kV
10.4.6. Above 33 kV
10.5. Market Analysis, Insights and Forecast - by End-User
10.5.1. Utilities
10.5.2. Residential
10.5.3. Commercial
10.5.4. Industrial
10.6. Market Analysis, Insights and Forecast - by Component
10.6.1. Circuit Breakers
10.6.2. Contactors
10.6.3. Switches & Disconnectors
10.6.4. Fuses
10.6.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Schneider Electric SE
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Siemens AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. ABB Ltd./Hitachi Energy
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Eaton Corporation plc
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. GE Vernova (Grid Solutions)
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Mitsubishi Electric Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Toshiba Infrastructure Systems & Solutions Corporation
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. CG Power and Industrial Solutions Ltd.
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. TBEA Co. Ltd.
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Hyosung Heavy Industries Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. LS Electric Co. Ltd.
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. WEG S.A.
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Rockwell Automation Inc.
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Emerson Electric Co.
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. NKT A/S
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. ZIV Group
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. SEC Electric
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Medium Voltage Switchgears: A Technology Perspective Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Insulation 2026 & 2034
Figure 3: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Insulation 2026 & 2034
Figure 4: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Current Type 2026 & 2034
Figure 5: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Current Type 2026 & 2034
Figure 6: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Installation 2026 & 2034
Figure 7: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Installation 2026 & 2034
Figure 8: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Voltage Range 2026 & 2034
Figure 9: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Voltage Range 2026 & 2034
Figure 10: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by End-User 2026 & 2034
Figure 11: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by End-User 2026 & 2034
Figure 12: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Component 2026 & 2034
Figure 13: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Component 2026 & 2034
Figure 14: North America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Insulation 2026 & 2034
Figure 17: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Insulation 2026 & 2034
Figure 18: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Current Type 2026 & 2034
Figure 19: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Current Type 2026 & 2034
Figure 20: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Installation 2026 & 2034
Figure 21: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Installation 2026 & 2034
Figure 22: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Voltage Range 2026 & 2034
Figure 23: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Voltage Range 2026 & 2034
Figure 24: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by End-User 2026 & 2034
Figure 25: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by End-User 2026 & 2034
Figure 26: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Component 2026 & 2034
Figure 27: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Component 2026 & 2034
Figure 28: Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Insulation 2026 & 2034
Figure 31: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Insulation 2026 & 2034
Figure 32: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Current Type 2026 & 2034
Figure 33: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Current Type 2026 & 2034
Figure 34: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Installation 2026 & 2034
Figure 35: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Installation 2026 & 2034
Figure 36: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Voltage Range 2026 & 2034
Figure 37: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Voltage Range 2026 & 2034
Figure 38: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by End-User 2026 & 2034
Figure 39: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by End-User 2026 & 2034
Figure 40: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Component 2026 & 2034
Figure 41: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Component 2026 & 2034
Figure 42: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 44: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Insulation 2026 & 2034
Figure 45: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Insulation 2026 & 2034
Figure 46: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Current Type 2026 & 2034
Figure 47: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Current Type 2026 & 2034
Figure 48: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Installation 2026 & 2034
Figure 49: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Installation 2026 & 2034
Figure 50: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Voltage Range 2026 & 2034
Figure 51: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Voltage Range 2026 & 2034
Figure 52: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by End-User 2026 & 2034
Figure 53: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by End-User 2026 & 2034
Figure 54: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Component 2026 & 2034
Figure 55: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Component 2026 & 2034
Figure 56: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 57: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
Figure 58: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Insulation 2026 & 2034
Figure 59: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Insulation 2026 & 2034
Figure 60: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Current Type 2026 & 2034
Figure 61: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Current Type 2026 & 2034
Figure 62: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Installation 2026 & 2034
Figure 63: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Installation 2026 & 2034
Figure 64: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Voltage Range 2026 & 2034
Figure 65: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Voltage Range 2026 & 2034
Figure 66: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by End-User 2026 & 2034
Figure 67: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by End-User 2026 & 2034
Figure 68: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Component 2026 & 2034
Figure 69: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Component 2026 & 2034
Figure 70: South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion), by Country 2026 & 2034
Figure 71: South America Medium Voltage Switchgears: A Technology Perspective Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Insulation 2020 & 2034
Table 2: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Current Type 2020 & 2034
Table 3: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Installation 2020 & 2034
Table 4: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Voltage Range 2020 & 2034
Table 5: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by End-User 2020 & 2034
Table 6: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Component 2020 & 2034
Table 7: Global Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Insulation 2020 & 2034
Table 9: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Current Type 2020 & 2034
Table 10: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Installation 2020 & 2034
Table 11: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Voltage Range 2020 & 2034
Table 12: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by End-User 2020 & 2034
Table 13: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Component 2020 & 2034
Table 14: North America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 17: Mexico Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Insulation 2020 & 2034
Table 19: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Current Type 2020 & 2034
Table 20: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Installation 2020 & 2034
Table 21: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Voltage Range 2020 & 2034
Table 22: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by End-User 2020 & 2034
Table 23: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Component 2020 & 2034
Table 24: Europe Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Italy Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Spain Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Rest of Europe Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Insulation 2020 & 2034
Table 32: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Current Type 2020 & 2034
Table 33: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Installation 2020 & 2034
Table 34: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Voltage Range 2020 & 2034
Table 35: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by End-User 2020 & 2034
Table 36: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Component 2020 & 2034
Table 37: Asia Pacific Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 38: China Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: India Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Japan Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: South Korea Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: ASEAN Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Australia Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Insulation 2020 & 2034
Table 45: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Current Type 2020 & 2034
Table 46: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Installation 2020 & 2034
Table 47: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Voltage Range 2020 & 2034
Table 48: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by End-User 2020 & 2034
Table 49: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Component 2020 & 2034
Table 50: Middle East & Africa Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 51: Saudi Arabia Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: UAE Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: South Africa Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: Rest of MEA Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 55: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Insulation 2020 & 2034
Table 56: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Current Type 2020 & 2034
Table 57: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Installation 2020 & 2034
Table 58: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Voltage Range 2020 & 2034
Table 59: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by End-User 2020 & 2034
Table 60: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Component 2020 & 2034
Table 61: South America Medium Voltage Switchgears: A Technology Perspective Revenue Billion Forecast, by Country 2020 & 2034
Table 62: Brazil Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 63: Argentina Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 64: Mexico Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Table 65: Rest of South America Medium Voltage Switchgears: A Technology Perspective Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the size of the medium voltage switchgear market in 2026?
The global medium voltage switchgear market is estimated at USD 19.66 billion in 2026, based on our proprietary primary research. It is projected to reach USD 40.25 billion by 2035, growing at a CAGR of 8.3% from 2026 to 2035.
2Why is the MV switchgear market growing at 8.3% CAGR?
Growth is driven by global grid modernization investments (USD 400 billion in 2024), renewable energy integration (585 GW added in 2024), and smart grid digitalization mandates. These factors are increasing both the volume and value of MV switchgear deployments.
3Which technology is replacing SF6 in MV switchgear?
Vacuum interruption, solid-dielectric, and clean-air (fluoronitrile) technologies are replacing SF6. The EU bans SF6 in new MV switchgear ≤24 kV from January 2026, accelerating adoption of SF6-free alternatives, which are forecast to grow at a 10.5% CAGR through 2035.
4Which region dominates the MV switchgear market?
Asia-Pacific is the largest market, accounting for 40.3% of 2025 revenue, driven by grid investments in China, India, and ASEAN. It is also the fastest-growing region, with a projected CAGR of 6.8% through 2031.
5Who are the leading companies in the MV switchgear market?
The top five players—Schneider Electric, Siemens AG, ABB/Hitachi Energy, Eaton, and GE Vernova—collectively held approximately 55% market share in 2025. Schneider Electric led with over 16% share.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted over 120 in-depth interviews with senior executives across the MV switchgear value chain, including switchgear OEMs, component suppliers (vacuum interrupters, relays), EPC contractors, utility procurement heads, and industrial end-users. This primary research accounts for 70-80% of our data inputs.
Interviews were structured to capture technology adoption trends, specification preferences, procurement criteria, and regulatory compliance challenges, with a focus on SF6-free technologies and digitalization.
We also conducted a quantitative survey of 300+ stakeholders to validate market sizing and segment shares.
All primary research is conducted in-house, ensuring data confidentiality and proprietary insights.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Chief Engineer
25%
Product Manager
20%
Operations Manager
15%
Research & Development Lead
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Switchgear OEMs
35%
Component Suppliers
20%
EPC Contractors
15%
Utilities
20%
Industrial End-Users
10%
Secondary Research & Industry Benchmarking
Our secondary research (20-30% of inputs) draws from official multilateral sources, including the International Energy Agency (IEA) grid investment data, IRENA renewable capacity statistics, and BloombergNEF grid investment gap analysis.
We benchmark technology standards and regulatory frameworks from recognized bodies such as the International Electrotechnical Commission (IEC), the European Parliament (EU Regulation 2024/573), and the IEEE Power & Energy Society.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to validate company financials, market shares, and M&A activities.
All secondary sources are cross-referenced with primary interviews for consistency.
Demand Modeling & Market Estimation
We employ a simultaneous top-down and bottom-up approach. The top-down model uses regional grid investment forecasts and utility capex plans to derive MV switchgear spending. The bottom-up model builds market size from unit shipments by voltage class, insulation type, and end-user, validated through multi-level data triangulation.
Quantitative metrics used in the bottom-up calculation include: (1) MV bays installed per new substation (4-12 bays), (2) average selling price per bay by technology type (AIS vs GIS vs SF6-free), (3) replacement rates derived from installed base age profiles, and (4) renewable capacity additions converted to MV connection points.
We model technology substitution curves for SF6-free and digital switchgear, incorporating regulatory timelines and cost premiums.
Data Accuracy & Quality Check
Every data point is subjected to a three-tier validation: (1) comparison with proprietary historical estimates, (2) triangulation with independent primary interviews, and (3) sanity checks against official trade and investment statistics.
Our guaranteed estimated data accuracy level is 85-90%. Reports are updated to the date of purchase, ensuring the latest market developments are reflected.
We maintain a rigorous quality assurance process, including peer review by senior analysts and validation against real-world project pipelines.