Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Regulatory T Cell
Manufacturing Products and Services / MARKET REPORT
Regulatory T Cell | Insight Market Data
Regulatory T Cell by Therapeutic Area (Autoimmune Disorders, Oncological Disorders, Post-Transplant Infection, Neurological Disorders, Metabolic Disorders, Dermatological Disorders), by Products (Tregs, Interleukin 2, Monoclonal Antibodies, Small Molecules, CAR-Treg, Other Products), by Source of T-Cells (Autologous, Allogeneic), by End-User (Hospitals & Clinics, Academic & Research Institutions, Others), by North America (US, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Southeast Asia, Rest of Asia Pacific), by Latin America (Brazil, Mexico, Argentina, Rest of Latin America), by Middle East & Africa (GCC Countries, South Africa, Rest of Middle East & Africa) Forecast 2026-2034
PC industry market to grow at 8.98% CAGR from USD 242.63 Bn in 2026 to USD 372.68 Bn by 2031, fueled by AI-enabled upgrades and Windows 10 EOL refresh.
The Kamado Grill Market is valued at USD 12.04 Billion in 2026, growing at a 5.6% CAGR to reach USD 20.76 Billion by 2036, driven by premium outdoor cooking.
Nov 2026|236 pages
$2900.00
Nursing education market valued at USD 26.6 billion in 2024, growing at 6.4% CAGR to reach USD 49.4 billion by 2034 amid global nurse shortages.
Nov 2026|259 pages
$2900.00
The cellular baseband chips market is valued at USD 1.97 billion in 2025 and is projected to reach USD 3.77 billion by 2032, growing at a CAGR of 9.70%.
Executive Overview: The Regulatory T Cell Market at an Inflection Point
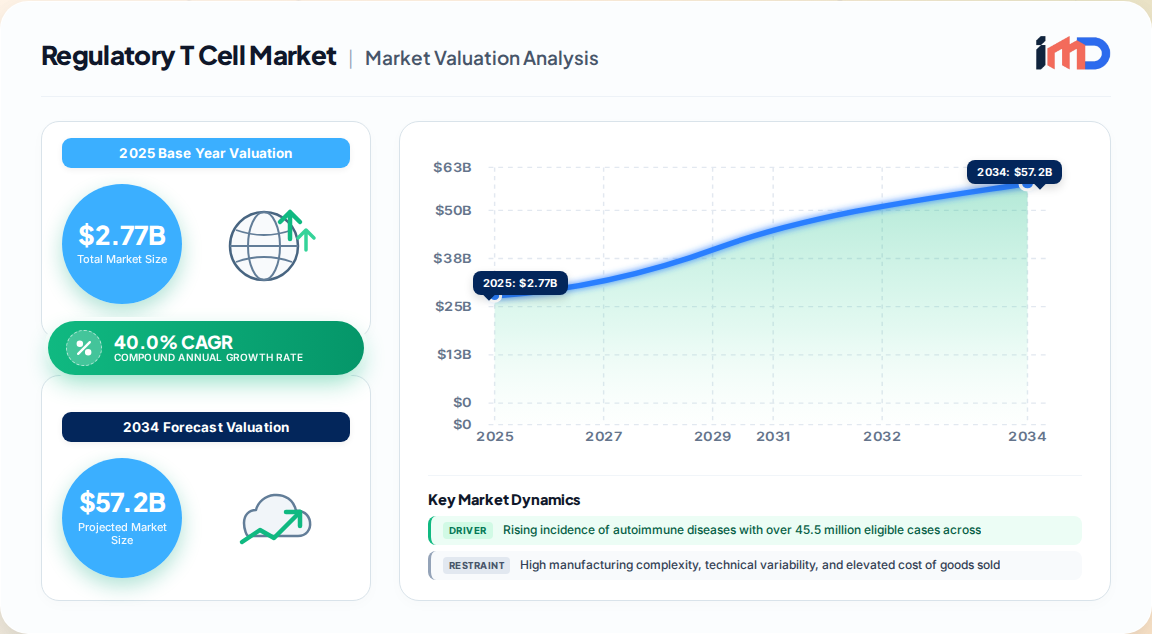
The global regulatory T cell (Treg) market represents one of the most scientifically compelling frontiers in advanced therapeutics. Our proprietary first-party research estimates the market at USD 2.77 Billion in 2025, advancing at a 40.0% CAGR through 2035 as adoptive Treg therapies, IL-2 pathway modulators, and engineered CAR-Treg constructs move from academic proof-of-concept into industrialized clinical development. Unlike conventional small-molecule or antibody modalities, Treg therapies are designed to actively rebuild immune tolerance rather than broadly suppress immunity, a mechanistic advantage that is reshaping treatment paradigms across autoimmune disease, transplant medicine, and inflammatory disorders.
Regulatory T Cell Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
2.770 B
2025
3.878 B
2026
5.429 B
2027
7.601 B
2028
10.64 B
2029
14.90 B
2030
20.86 B
2031
The scientific rationale is now well established. Tregs are a specialized CD4+ subset that suppress pathogenic immune activation while preserving host defense against infection and malignancy. More than 90 pharmaceutical companies and academic institutions have entered the field, and the global pipeline now features close to 95 product candidates, of which more than 15 are in advanced stages of development.
Capital formation has been equally decisive. Strategic investors have deployed approximately USD 3 Billion into Treg-focused developers over the past five years, while the broader cell and gene therapy sector attracted USD 4.4 Billion in the first quarter of 2024 alone. This liquidity is funding the transition from autologous, patient-specific manufacturing toward scalable allogeneic and antigen-specific platforms.
Market Metric
Proprietary Estimate
Base year valuation (2025)
USD 2.77 Billion
Forecast CAGR (2025-2035)
40.0%
Advanced-stage pipeline candidates
15+
Total Treg pipeline products
~95
Treg-focused developers tracked
90+
Cumulative strategic investment (5 years)
~USD 3 Billion
Key Market Drivers
Rising autoimmune disease burden: The eligible patient pool across seven major markets exceeded 45.5 million cases in 2023 across selected Treg indications. Atopic dermatitis alone accounted for nearly 39.0 million eligible cases, establishing dermatology as an immediate commercial beachhead for Treg-based modulation.
Transplant and GVHD demand: With an estimated 62,770 new leukemia cases annually in the United States, hematopoietic stem cell transplantation volumes continue to climb, driving demand for tolerance-inducing therapies that prevent graft rejection without systemic immunosuppression.
IL-2 pathway validation: Low-dose interleukin-2 and engineered IL-2 variants (such as rezpegaldesleukin) have demonstrated clinical activity in atopic dermatitis and psoriasis, providing near-term revenue pathways while adoptive Treg products mature.
Corporate collaboration and licensing: AstraZeneca's collaboration with Quell to develop Treg therapies for Type 1 diabetes and inflammatory bowel disease, and Sonoma Biotherapeutics' USD 45 Million milestone receipt from Regeneron, exemplify the pharma-biotech risk-sharing model now standard in this market.
Policy and reimbursement evolution: Emerging reimbursement frameworks for advanced cell therapies, combined with FDA removal of REMS requirements for certain cell therapy classes, are progressively reducing administrative friction at treatment centers.
Restraints and Structural Challenges
Manufacturing complexity and COGS: Isolating, purifying, and expanding a rare, phenotypically labile cellular subset generates high technical variability and inconsistent yields. This scalability bottleneck is the single greatest constraint on commercial penetration.
Concentration of commercial revenue: Approximately 75% of global advanced therapy revenue is derived from fewer than 10 products, underscoring the disconnect between pipeline volume and commercial reality.
Cost of goods and reimbursement friction: Autologous Treg products carry per-patient manufacturing economics that strain payer budgets, particularly in chronic, non-oncological indications.
Durability and stability risk: Maintaining suppressive function through expansion and cryopreservation remains technically demanding and contributes to elevated clinical failure rates.
Value Chain Analysis
The Treg value chain is vertically fragmented and highly specialized.
Cell sourcing and apheresis: Clinical-grade leukapheresis networks and allogeneic donor banks supply the raw cellular input; donor screening and HLA characterization are critical quality gates.
Cell engineering and expansion: Gene editing (CRISPR, TALEN), lentiviral transduction for CAR-Treg constructs, and GMP-compliant expansion media define the manufacturing core.
Cryopreservation and logistics: Cold-chain infrastructure capable of maintaining cell viability across global distribution remains a binding constraint outside North America and Western Europe.
Clinical administration: Accredited transplant centers, academic medical centers, and specialized cell therapy hospitals form the administration layer.
Analytics and release testing: Potency assays for suppressive function are not yet fully standardized, creating regulatory uncertainty and lengthening release timelines.
Segmentation Outlook
By product type, the Tregs segment is positioned to dominate, supported by expanding adoptive transfer applications. Interleukin-2 agents provide the nearest-term revenue, while CAR-Treg constructs represent the highest-growth, highest-value frontier. Monoclonal antibodies and small molecules address adjacent tolerance pathways with more conventional manufacturing economics.
By therapeutic area, autoimmune disorders constitute the fastest-growing segment, with Type 1 diabetes projected to contribute the largest single indication share of market value by 2034 in major developed markets. Post-transplant infection and GVHD represent the most clinically de-risked applications, while neurological, metabolic, and dermatological indications broaden the addressable population substantially.
By source, autologous therapies currently anchor clinical programs due to regulatory familiarity and reduced immunogenicity risk, but allogeneic off-the-shelf platforms are the principal vector for long-term scalability and margin expansion.
Segment
Strategic Position
Tregs (adoptive)
Dominant share; deepest clinical validation
CAR-Treg
Highest growth; precision targeting
Interleukin 2
Nearest-term commercial revenue
Monoclonal antibodies
Adjacent pathway modulation
Autologous source
Current clinical standard
Allogeneic source
Scalability and margin lever
Regional Outlook
North America commands the largest share of global Treg market value, supported by concentrated R&D expenditure, the highest density of clinical trial activity, and a reimbursement architecture capable of absorbing high-cost cell therapies. The United States alone is projected to account for approximately 76% of the seven-major-market value pool by 2034.
Regulatory T Cell Regional Market Share
Loading chart...
Europe follows, with Germany leading regional market size and Spain representing the smallest of the major EU markets. European growth is anchored by academic transplant networks and a maturing advanced therapy medicinal product regulatory pathway.
Asia-Pacific is the fastest-growing region. Manufacturing cost advantages, expanding trial infrastructure, and active developers in South Korea and China position the region as both a clinical trial destination and a future commercial manufacturing hub. Latin America and the Middle East & Africa remain early-stage but represent meaningful long-term patient pools, particularly in Type 1 diabetes and inflammatory bowel disease.
Competitive Landscape and Strategic White-Space Analysis
The competitive field spans large-cap pharmaceutical entrants, clinical-stage cell therapy specialists, and platform companies. Key participants include Abata Therapeutics, Cellenkos, Coya Therapeutics, Sonoma Biotherapeutics, Nektar Therapeutics, Eli Lilly, Sangamo Therapeutics (TxCell), TRACT Therapeutics, TRexBio, Mozart Therapeutics, PolTREG, Parvus Therapeutics, ILTOO Pharma, GentiBio, Tr1X, Quell Therapeutics, Kyverna Therapeutics, VT Bio, and Roche.
Three white-space opportunities stand out for strategic entrants:
Antigen-specific Treg platforms that deliver targeted suppression without broad immunosuppression, particularly in Type 1 diabetes and autoimmune hepatitis.
Allogeneic manufacturing scale-up as a service and partnership layer, where few credible GMP-capable providers exist.
Standardized potency assay development, which could become a regulatory prerequisite and therefore a defensible technical moat.
Global Trade, Supply Chain and Investment Risk Assessment
Treg therapies are not traded commodities; value flows through cross-border licensing, manufacturing service agreements, and clinical supply chains rather than customs-recorded goods. Consequently, supply chain risk concentrates in three nodes: specialized media and reagent sourcing, viral vector and gene-editing input availability, and cryogenic logistics capacity.
Concentration risk: GMP-grade expansion media and viral vector supply remain concentrated among a small number of qualified suppliers, creating single-point-of-failure exposure.
Cold-chain dependency: Fresh autologous products require vein-to-vein logistics measured in hours, restricting commercial reach to proximate accredited centers and favoring cryopreserved allogeneic models for global scale.
Capital cycle risk: Valuation sensitivity to clinical readouts is acute; developers with unvalidated potency assays face elevated financing risk.
Geographic diversification: Recent activity in Europe and Asia-Pacific, including Kincell Bio's collaboration with RegCell and financing rounds such as TRexBio's USD 50 Million and Zag Bio's USD 80 Million Series A, signals broadening capital geography beyond the United States.
Strategic Recommendations
Prioritize antigen-specific and CAR-Treg assets where mechanistic differentiation supports premium pricing and differentiation from polyclonal approaches.
Invest early in manufacturing scale-up partnerships; industrialization capability, not clinical novelty, will determine which developers capture durable share.
Target dermatological and Type 1 diabetes indications for near-term commercial traction given the scale of eligible populations.
Build standardized potency and release testing capability as a regulatory and competitive differentiator.
Structure pharma-biotech collaborations to share manufacturing risk while retaining indication-level optionality.
Regulatory T Cell Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Regulatory T Cell REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 40.0% from 2020-2034
Segmentation
By Therapeutic Area
Autoimmune Disorders
Oncological Disorders
Post-Transplant Infection
Neurological Disorders
Metabolic Disorders
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising incidence of autoimmune diseases with over 45.5 million eligible cases across seven major markets
3.1.2. Increasing GVHD and transplant tolerance demand tied to growing stem cell transplantation volumes
3.1.3. Strong venture and strategic investment, including roughly USD 3 Billion deployed over five years
3.1.4. Validation of low-dose IL-2 and engineered IL-2 variants in atopic dermatitis and psoriasis
3.2. Market Trends
3.2.1. Shift from polyclonal to antigen-specific and CAR-engineered Treg constructs for precision immune tolerance
3.2.2. Transition from autologous to allogeneic off-the-shelf Treg platforms to improve scalability
3.2.4. Standardization of Treg potency and release assays as a regulatory priority
3.3. Market Restrains
3.3.1. High manufacturing complexity, technical variability, and elevated cost of goods sold
3.3.2. Poor reimbursement frameworks for advanced cell therapies
3.3.3. Phenotypic instability of expanded Treg populations
3.3.4. Concentrated commercial revenue with approximately 75% held by fewer than 10 products
Dermatological Disorders
By Products
Tregs
Interleukin 2
Monoclonal Antibodies
Small Molecules
CAR-Treg
Other Products
By Source of T-Cells
Autologous
Allogeneic
By End-User
Hospitals & Clinics
Academic & Research Institutions
Others
By Geography
North America
US
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Southeast Asia
Rest of Asia Pacific
Latin America
Brazil
Mexico
Argentina
Rest of Latin America
Middle East & Africa
GCC Countries
South Africa
Rest of Middle East & Africa
3.4. Market Restraints
3.4.1. High manufacturing complexity, technical variability, and elevated cost of goods sold
3.4.2. Poor reimbursement frameworks for advanced cell therapies
3.4.3. Phenotypic instability of expanded Treg populations
3.4.4. Concentrated commercial revenue with approximately 75% held by fewer than 10 products
3.5. Market Challenges
3.5.1. Scaling GMP manufacturing while maintaining suppressive function and consistent yields
3.5.2. Reducing vein-to-vein logistics constraints for fresh autologous products
3.5.3. Establishing standardized potency assays acceptable to regulators
3.5.4. Securing durable reimbursement for high-cost chronic indications
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Therapeutic Area
5.1.1. Autoimmune Disorders
5.1.2. Oncological Disorders
5.1.3. Post-Transplant Infection
5.1.4. Neurological Disorders
5.1.5. Metabolic Disorders
5.1.6. Dermatological Disorders
5.2. Market Analysis, Insights and Forecast - by Products
5.2.1. Tregs
5.2.2. Interleukin 2
5.2.3. Monoclonal Antibodies
5.2.4. Small Molecules
5.2.5. CAR-Treg
5.2.6. Other Products
5.3. Market Analysis, Insights and Forecast - by Source of T-Cells
5.3.1. Autologous
5.3.2. Allogeneic
5.4. Market Analysis, Insights and Forecast - by End-User
5.4.1. Hospitals & Clinics
5.4.2. Academic & Research Institutions
5.4.3. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Therapeutic Area
6.1.1. Autoimmune Disorders
6.1.2. Oncological Disorders
6.1.3. Post-Transplant Infection
6.1.4. Neurological Disorders
6.1.5. Metabolic Disorders
6.1.6. Dermatological Disorders
6.2. Market Analysis, Insights and Forecast - by Products
6.2.1. Tregs
6.2.2. Interleukin 2
6.2.3. Monoclonal Antibodies
6.2.4. Small Molecules
6.2.5. CAR-Treg
6.2.6. Other Products
6.3. Market Analysis, Insights and Forecast - by Source of T-Cells
6.3.1. Autologous
6.3.2. Allogeneic
6.4. Market Analysis, Insights and Forecast - by End-User
6.4.1. Hospitals & Clinics
6.4.2. Academic & Research Institutions
6.4.3. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Therapeutic Area
7.1.1. Autoimmune Disorders
7.1.2. Oncological Disorders
7.1.3. Post-Transplant Infection
7.1.4. Neurological Disorders
7.1.5. Metabolic Disorders
7.1.6. Dermatological Disorders
7.2. Market Analysis, Insights and Forecast - by Products
7.2.1. Tregs
7.2.2. Interleukin 2
7.2.3. Monoclonal Antibodies
7.2.4. Small Molecules
7.2.5. CAR-Treg
7.2.6. Other Products
7.3. Market Analysis, Insights and Forecast - by Source of T-Cells
7.3.1. Autologous
7.3.2. Allogeneic
7.4. Market Analysis, Insights and Forecast - by End-User
7.4.1. Hospitals & Clinics
7.4.2. Academic & Research Institutions
7.4.3. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Therapeutic Area
8.1.1. Autoimmune Disorders
8.1.2. Oncological Disorders
8.1.3. Post-Transplant Infection
8.1.4. Neurological Disorders
8.1.5. Metabolic Disorders
8.1.6. Dermatological Disorders
8.2. Market Analysis, Insights and Forecast - by Products
8.2.1. Tregs
8.2.2. Interleukin 2
8.2.3. Monoclonal Antibodies
8.2.4. Small Molecules
8.2.5. CAR-Treg
8.2.6. Other Products
8.3. Market Analysis, Insights and Forecast - by Source of T-Cells
8.3.1. Autologous
8.3.2. Allogeneic
8.4. Market Analysis, Insights and Forecast - by End-User
8.4.1. Hospitals & Clinics
8.4.2. Academic & Research Institutions
8.4.3. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Therapeutic Area
9.1.1. Autoimmune Disorders
9.1.2. Oncological Disorders
9.1.3. Post-Transplant Infection
9.1.4. Neurological Disorders
9.1.5. Metabolic Disorders
9.1.6. Dermatological Disorders
9.2. Market Analysis, Insights and Forecast - by Products
9.2.1. Tregs
9.2.2. Interleukin 2
9.2.3. Monoclonal Antibodies
9.2.4. Small Molecules
9.2.5. CAR-Treg
9.2.6. Other Products
9.3. Market Analysis, Insights and Forecast - by Source of T-Cells
9.3.1. Autologous
9.3.2. Allogeneic
9.4. Market Analysis, Insights and Forecast - by End-User
9.4.1. Hospitals & Clinics
9.4.2. Academic & Research Institutions
9.4.3. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Therapeutic Area
10.1.1. Autoimmune Disorders
10.1.2. Oncological Disorders
10.1.3. Post-Transplant Infection
10.1.4. Neurological Disorders
10.1.5. Metabolic Disorders
10.1.6. Dermatological Disorders
10.2. Market Analysis, Insights and Forecast - by Products
10.2.1. Tregs
10.2.2. Interleukin 2
10.2.3. Monoclonal Antibodies
10.2.4. Small Molecules
10.2.5. CAR-Treg
10.2.6. Other Products
10.3. Market Analysis, Insights and Forecast - by Source of T-Cells
10.3.1. Autologous
10.3.2. Allogeneic
10.4. Market Analysis, Insights and Forecast - by End-User
10.4.1. Hospitals & Clinics
10.4.2. Academic & Research Institutions
10.4.3. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Abata Therapeutics
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Cellenkos Inc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Coya Therapeutics
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Roche
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Lisata Therapeutics
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Sonoma Biotherapeutics
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Nektar Therapeutics
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Eli Lilly and Company
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Baudax Bio
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. TRACT Therapeutics
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. VT Bio
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Sangamo Therapeutics (TxCell)
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. TRexBio
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Mozart Therapeutics
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Pfizer Inc.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. PolTREG S.A.
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Parvus Therapeutics
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. ILTOO Pharma
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. GentiBio
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Tr1X
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Quell Therapeutics
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. AstraZeneca
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Kyverna Therapeutics
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Orca Bio
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Rapa Therapeutics
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Taiwan Bio Therapeutics
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.1.27. REGiMMUNE
11.1.27.1. Company Overview
11.1.27.2. Products
11.1.27.3. Company Financials
11.1.27.4. SWOT Analysis
11.1.28. Georgiamune
11.1.28.1. Company Overview
11.1.28.2. Products
11.1.28.3. Company Financials
11.1.28.4. SWOT Analysis
11.1.29. Egle Therapeutics
11.1.29.1. Company Overview
11.1.29.2. Products
11.1.29.3. Company Financials
11.1.29.4. SWOT Analysis
11.1.30. RAPT Therapeutics
11.1.30.1. Company Overview
11.1.30.2. Products
11.1.30.3. Company Financials
11.1.30.4. SWOT Analysis
11.1.31. Nanjing Immunophage Biotech
11.1.31.1. Company Overview
11.1.31.2. Products
11.1.31.3. Company Financials
11.1.31.4. SWOT Analysis
11.1.32. Incyte
11.1.32.1. Company Overview
11.1.32.2. Products
11.1.32.3. Company Financials
11.1.32.4. SWOT Analysis
11.1.33. Novabio Therapeutics
11.1.33.1. Company Overview
11.1.33.2. Products
11.1.33.3. Company Financials
11.1.33.4. SWOT Analysis
11.1.34. TeraImmune
11.1.34.1. Company Overview
11.1.34.2. Products
11.1.34.3. Company Financials
11.1.34.4. SWOT Analysis
11.1.35. RegCell
11.1.35.1. Company Overview
11.1.35.2. Products
11.1.35.3. Company Financials
11.1.35.4. SWOT Analysis
11.1.36. Zag Bio
11.1.36.1. Company Overview
11.1.36.2. Products
11.1.36.3. Company Financials
11.1.36.4. SWOT Analysis
11.1.37. Kincell Bio
11.1.37.1. Company Overview
11.1.37.2. Products
11.1.37.3. Company Financials
11.1.37.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Regulatory T Cell Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Regulatory T Cell Revenue (Billion), by Therapeutic Area 2026 & 2034
Figure 3: North America Regulatory T Cell Revenue Share (%), by Therapeutic Area 2026 & 2034
Figure 4: North America Regulatory T Cell Revenue (Billion), by Products 2026 & 2034
Figure 5: North America Regulatory T Cell Revenue Share (%), by Products 2026 & 2034
Figure 6: North America Regulatory T Cell Revenue (Billion), by Source of T-Cells 2026 & 2034
Figure 7: North America Regulatory T Cell Revenue Share (%), by Source of T-Cells 2026 & 2034
Figure 8: North America Regulatory T Cell Revenue (Billion), by End-User 2026 & 2034
Figure 9: North America Regulatory T Cell Revenue Share (%), by End-User 2026 & 2034
Figure 10: North America Regulatory T Cell Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Regulatory T Cell Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Regulatory T Cell Revenue (Billion), by Therapeutic Area 2026 & 2034
Figure 13: Europe Regulatory T Cell Revenue Share (%), by Therapeutic Area 2026 & 2034
Figure 14: Europe Regulatory T Cell Revenue (Billion), by Products 2026 & 2034
Figure 15: Europe Regulatory T Cell Revenue Share (%), by Products 2026 & 2034
Figure 16: Europe Regulatory T Cell Revenue (Billion), by Source of T-Cells 2026 & 2034
Figure 17: Europe Regulatory T Cell Revenue Share (%), by Source of T-Cells 2026 & 2034
Figure 18: Europe Regulatory T Cell Revenue (Billion), by End-User 2026 & 2034
Figure 19: Europe Regulatory T Cell Revenue Share (%), by End-User 2026 & 2034
Figure 20: Europe Regulatory T Cell Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Regulatory T Cell Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia Pacific Regulatory T Cell Revenue (Billion), by Therapeutic Area 2026 & 2034
Figure 23: Asia Pacific Regulatory T Cell Revenue Share (%), by Therapeutic Area 2026 & 2034
Figure 24: Asia Pacific Regulatory T Cell Revenue (Billion), by Products 2026 & 2034
Figure 25: Asia Pacific Regulatory T Cell Revenue Share (%), by Products 2026 & 2034
Figure 26: Asia Pacific Regulatory T Cell Revenue (Billion), by Source of T-Cells 2026 & 2034
Figure 27: Asia Pacific Regulatory T Cell Revenue Share (%), by Source of T-Cells 2026 & 2034
Figure 28: Asia Pacific Regulatory T Cell Revenue (Billion), by End-User 2026 & 2034
Figure 29: Asia Pacific Regulatory T Cell Revenue Share (%), by End-User 2026 & 2034
Figure 30: Asia Pacific Regulatory T Cell Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia Pacific Regulatory T Cell Revenue Share (%), by Country 2026 & 2034
Figure 32: Latin America Regulatory T Cell Revenue (Billion), by Therapeutic Area 2026 & 2034
Figure 33: Latin America Regulatory T Cell Revenue Share (%), by Therapeutic Area 2026 & 2034
Figure 34: Latin America Regulatory T Cell Revenue (Billion), by Products 2026 & 2034
Figure 35: Latin America Regulatory T Cell Revenue Share (%), by Products 2026 & 2034
Figure 36: Latin America Regulatory T Cell Revenue (Billion), by Source of T-Cells 2026 & 2034
Figure 37: Latin America Regulatory T Cell Revenue Share (%), by Source of T-Cells 2026 & 2034
Figure 38: Latin America Regulatory T Cell Revenue (Billion), by End-User 2026 & 2034
Figure 39: Latin America Regulatory T Cell Revenue Share (%), by End-User 2026 & 2034
Figure 40: Latin America Regulatory T Cell Revenue (Billion), by Country 2026 & 2034
Figure 41: Latin America Regulatory T Cell Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Regulatory T Cell Revenue (Billion), by Therapeutic Area 2026 & 2034
Figure 43: Middle East & Africa Regulatory T Cell Revenue Share (%), by Therapeutic Area 2026 & 2034
Figure 44: Middle East & Africa Regulatory T Cell Revenue (Billion), by Products 2026 & 2034
Figure 45: Middle East & Africa Regulatory T Cell Revenue Share (%), by Products 2026 & 2034
Figure 46: Middle East & Africa Regulatory T Cell Revenue (Billion), by Source of T-Cells 2026 & 2034
Figure 47: Middle East & Africa Regulatory T Cell Revenue Share (%), by Source of T-Cells 2026 & 2034
Figure 48: Middle East & Africa Regulatory T Cell Revenue (Billion), by End-User 2026 & 2034
Figure 49: Middle East & Africa Regulatory T Cell Revenue Share (%), by End-User 2026 & 2034
Figure 50: Middle East & Africa Regulatory T Cell Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Regulatory T Cell Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Regulatory T Cell Revenue Billion Forecast, by Therapeutic Area 2020 & 2034
Table 2: Global Regulatory T Cell Revenue Billion Forecast, by Products 2020 & 2034
Table 3: Global Regulatory T Cell Revenue Billion Forecast, by Source of T-Cells 2020 & 2034
Table 4: Global Regulatory T Cell Revenue Billion Forecast, by End-User 2020 & 2034
Table 5: Global Regulatory T Cell Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Regulatory T Cell Revenue Billion Forecast, by Therapeutic Area 2020 & 2034
Table 7: North America Regulatory T Cell Revenue Billion Forecast, by Products 2020 & 2034
Table 8: North America Regulatory T Cell Revenue Billion Forecast, by Source of T-Cells 2020 & 2034
Table 9: North America Regulatory T Cell Revenue Billion Forecast, by End-User 2020 & 2034
Table 10: North America Regulatory T Cell Revenue Billion Forecast, by Country 2020 & 2034
Table 11: US Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Regulatory T Cell Revenue Billion Forecast, by Therapeutic Area 2020 & 2034
Table 15: Europe Regulatory T Cell Revenue Billion Forecast, by Products 2020 & 2034
Table 16: Europe Regulatory T Cell Revenue Billion Forecast, by Source of T-Cells 2020 & 2034
Table 17: Europe Regulatory T Cell Revenue Billion Forecast, by End-User 2020 & 2034
Table 18: Europe Regulatory T Cell Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Italy Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Spain Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 24: Rest of Europe Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 25: Asia Pacific Regulatory T Cell Revenue Billion Forecast, by Therapeutic Area 2020 & 2034
Table 26: Asia Pacific Regulatory T Cell Revenue Billion Forecast, by Products 2020 & 2034
Table 27: Asia Pacific Regulatory T Cell Revenue Billion Forecast, by Source of T-Cells 2020 & 2034
Table 28: Asia Pacific Regulatory T Cell Revenue Billion Forecast, by End-User 2020 & 2034
Table 29: Asia Pacific Regulatory T Cell Revenue Billion Forecast, by Country 2020 & 2034
Table 30: China Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: Japan Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 32: India Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 33: South Korea Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 34: Southeast Asia Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 35: Rest of Asia Pacific Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 36: Latin America Regulatory T Cell Revenue Billion Forecast, by Therapeutic Area 2020 & 2034
Table 37: Latin America Regulatory T Cell Revenue Billion Forecast, by Products 2020 & 2034
Table 38: Latin America Regulatory T Cell Revenue Billion Forecast, by Source of T-Cells 2020 & 2034
Table 39: Latin America Regulatory T Cell Revenue Billion Forecast, by End-User 2020 & 2034
Table 40: Latin America Regulatory T Cell Revenue Billion Forecast, by Country 2020 & 2034
Table 41: Brazil Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: Mexico Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Argentina Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 44: Rest of Latin America Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 45: Middle East & Africa Regulatory T Cell Revenue Billion Forecast, by Therapeutic Area 2020 & 2034
Table 46: Middle East & Africa Regulatory T Cell Revenue Billion Forecast, by Products 2020 & 2034
Table 47: Middle East & Africa Regulatory T Cell Revenue Billion Forecast, by Source of T-Cells 2020 & 2034
Table 48: Middle East & Africa Regulatory T Cell Revenue Billion Forecast, by End-User 2020 & 2034
Table 49: Middle East & Africa Regulatory T Cell Revenue Billion Forecast, by Country 2020 & 2034
Table 50: GCC Countries Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: South Africa Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Rest of Middle East & Africa Regulatory T Cell Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1What is the regulatory T cell market size in 2025?
Our proprietary primary research values the global regulatory T cell market at USD 2.77 Billion in 2025, with projections reaching approximately USD 22.75 Billion by 2031 at a 40.0% compound annual growth rate.
2Which region dominates the regulatory T cell market?
North America holds the largest share, accounting for roughly 46% of global market value, and the United States alone is projected to represent about 76% of the seven-major-market value pool by 2034.
3What is the fastest growing segment in the regulatory T cell market?
Autoimmune disorders represent the fastest-growing therapeutic segment, with Type 1 diabetes projected to contribute the largest single indication share of market value by 2034.
4Who are the leading companies developing regulatory T cell therapies?
Key developers include Abata Therapeutics, Coya Therapeutics, Sonoma Biotherapeutics, Quell Therapeutics, Kyverna Therapeutics, Nektar Therapeutics, PolTREG, ILTOO Pharma, TRexBio, and Sangamo Therapeutics (TxCell), alongside large-cap entrants such as Roche, AstraZeneca, and Eli Lilly.
5Why is manufacturing a challenge for regulatory T cell therapies?
Isolating and expanding a rare, phenotypically labile Treg subset produces inconsistent yields and high cost of goods, and approximately 75% of advanced therapy revenue is concentrated in fewer than 10 products, reflecting this scalability bottleneck.
6How many regulatory T cell therapy candidates are in development?
The global pipeline features close to 95 product candidates developed by more than 90 companies and academic institutions, with over 15 therapies in advanced stages of development.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total effort, encompassing structured interviews, physician surveys, and developer briefings across the Treg value chain.
We interview 4-5 specific company types: clinical-stage Treg cell therapy developers, GMP contract development and manufacturing organizations (CDMOs), leukapheresis and cell collection networks, IL-2 and CAR-Treg platform companies, and academic transplant and immunology research centers.
Stakeholder job titles interviewed include Chief Scientific Officer, Head of Cell Therapy Manufacturing, Director of Clinical Development, and Transplant Immunology Principal Investigator.
Validation of field-level pricing, capacity, and adoption data is conducted through direct developer disclosure and blinded physician panels.
All primary inputs are cross-checked against disclosed trial enrollment and disclosed financing events.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Scientific Officer
30%
Head of Cell Therapy Manufacturing
28%
Director of Clinical Development
25%
Transplant Immunology Principal Investigator
17%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Treg Cell Therapy Developers
35%
GMP CDMOs & Manufacturing Partners
20%
IL-2 & CAR-Treg Platform Companies
18%
Academic & Transplant Research Centers
15%
Cell Collection & Logistics Networks
12%
Secondary Research & Industry Benchmarking
Secondary research contributes 20-30% of total effort and draws exclusively on official and non-commercial sources.
Industry benchmarking leverages recognized non-profit technical bodies including the International Society for Cell & Gene Therapy and the Alliance for Regenerative Medicine, alongside WHO, OECD, and World Bank macroeconomic datasets.
Standard financial databases consulted include Bloomberg, Factiva, Hoovers, and PitchBook for financing, valuation, and partnership verification.
Every report is refreshed to the date of purchase, incorporating the most recent clinical readouts and financing events.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up estimation relies on specific quantitative metrics including eligible patient populations by indication, treated-patient penetration rates by accredited center, average annual cost of therapy per patient, and active pipeline candidate counts by phase.
Top-down estimation anchors to national advanced therapy expenditure and transplant procedure volumes, reconciling against company-level revenue disclosures.
Scenario modeling incorporates base, accelerated, and constrained adoption cases tied to manufacturing scale-up and reimbursement timelines.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85-90%, achieved through multi-level triangulation and analyst review.
Hybrid triangulation reconciles bottom-up and top-down outputs, with variance thresholds flagged and re-validated against primary interview evidence.
All figures undergo independent quality review before publication, and regional estimates are internally consistent with the global total.