About Insight Market Data

Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.

Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

report thumbnailPC Industry
Manufacturing Products and Services / MARKET REPORT

PC Industry | Insight Market Data

PC Industry by Form Factor (Laptops/Notebooks, Desktop Towers and SFF), by End-User (Consumers, Small and Medium Enterprise, Large Enterprise, Government and Education), by Processor Architecture (x86 (Intel-AMD), ARM-Based, RISC-V and Other), by Price Band (Entry-Level (<USD 600), Mid-Range (USD 600-1, 200), Premium (>USD 1, 200)), by Distribution Channel (Online, Offline), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by South America (Brazil, Argentina), by Middle East & Africa (South Africa, UAE, Saudi Arabia) Forecast 2026-2034

© Nov 6, 2026|Base Year: 2025|219 Pages
Srinwanti Kar

Srinwanti Kar

Senior Research Analyst

Main Logo

PC Industry Market Report 2026-2031: AI PCs & Hybrid Work Drive Growth


/
/

Business Address

Head Office

Ansec House 3 rd floor Tank Road, Yerwada, Pune, Maharashtra 411014

Contact Information

Craig Francis

Business Development Head

+12315155523

[email protected]

Secure Payment Partners

payment image
RetailLogisticsPackagingAutomotiveHealthcareAgricultureEnergy & PowerFood & BeverageAerospace & DefenseChemicals & MaterialsHospitality and TourismConsumer Goods and ServicesAnimal Nutrition & WellnessReal Estate and ConstructionHome and Property ImprovementTechnology, Media and TelecomManufacturing Products and ServicesFinancial Services and Investment Intelligence

© 2026 PRDUA Research & Media Private Limited, All rights reserved

Privacy Policy•Terms and Conditions•FAQ
Independent Intelligence for decisions that move markets
+12315155523[email protected]
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Main Logo
  • Home
  • About Us
  • Industries
    • Automotive
    • Consumer Goods and Services
    • Financial Services and Investment Intelligence
    • Home and Property Improvement
    • Logistics
    • Retail
    • Agriculture
    • Healthcare
    • Animal Nutrition & Wellness
    • Chemicals & Materials
    • Energy & Power
    • Food & Beverage
    • Hospitality and Tourism
    • Manufacturing Products and Services
    • Professional and Commercial Services
    • Real Estate and Construction
    • Aerospace & Defense
    • Packaging
    • Technology, Media and Telecom
  • Services
  • Contact
Talk to an analyst
Buy Now
Home
Industries
Manufacturing Products and Services
Author
Srinwanti Kar

Srinwanti Kar

Senior Research Analyst

I am a Senior Research Analyst delivering high-impact market intelligence across Technology, Media, and Telecom (TMT), ICT, and Semiconductors & Electronics. My expertise spans Manufacturing Products and Services, Construction, Automation, Communication Services, and other emerging sectors. I specialize in market sizing and technological forecasting, translating complex industrial and digital trends into strategic insights that help global clients unlock new opportunities.

Get In Touch
WHY IMD

Verified research

Analyst-reviewed data

Updated Nov 06, 2026

sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
sponsor image
CUSTOM INTELLIGENCE

Tailored for you

  • In-depth Analysis Tailored to Specified Regions or Segments
  • Company Profiles Customized to User Preferences
  • Customized Evaluation of Competitive Landscape to Meet Your Needs
Ask for customization
avatar

Analyst at Providence Strategic Partners at Petaling Jaya

Jared Wan

I have received the report already. Thanks you for your help.it has been a pleasure working with you. Thank you again for a good quality report

avatar

Internationalization Director

Santiago Mejia Molina

Yes, as a matter of fact we are totally satisfied with both reports that we have purchased and will continue to do so during this process of the internationalization of our brand.

avatar

Head of Product Management and Marketing

Olaf Gleibe

We are using your report, and it gave us valuable information."

avatar

Regional Director, Marketing and Business Development

Lina Lim

We've received the report and have reviewed the content. Overall, it looks great and aligns closely with the data we can verify based on our industry knowledge.

avatar

VP of Sales

DIGGLE Representative

Thank you very much for sharing the report. I have reviewed it and I am very satisfied with the quality and the insights it provides. It will certainly be valuable for our internal discussions.

artwork spiralartwork spiralRelated Reports
artwork underline

Kamado Grill Market Size, Share & Growth Analysis 2026-2036

The Kamado Grill Market is valued at USD 12.04 Billion in 2026, growing at a 5.6% CAGR to reach USD 20.76 Billion by 2036, driven by premium outdoor cooking.

Nov 2026|236 pages
$2900.00View report

Nursing education market valued at USD 26.6 billion in 2024, growing at 6.4% CAGR to reach USD 49.4 billion by 2034 amid global nurse shortages.

Nov 2026|259 pages
$2900.00

Regulatory T cell market to grow from USD 2.77 Billion in 2025 at a 40.0% CAGR, driven by autoimmune, transplant and CAR-Treg pipelines.

Nov 2026|277 pages
$2900.00

The cellular baseband chips market is valued at USD 1.97 billion in 2025 and is projected to reach USD 3.77 billion by 2032, growing at a CAGR of 9.70%.

Nov 2026|241 pages
$2900.00
Nursing Education Market Size, Growth & 2034 Forecast
View report
Regulatory T Cell Market Size, CAGR & Outlook to 2035
View report
Cellular Baseband Chips Market Size, Trends & Forecast 2025-2032
View report
PC Industry CAGR, market size, market share

Executive Overview: PC Industry Market Poised for Renewed Expansion

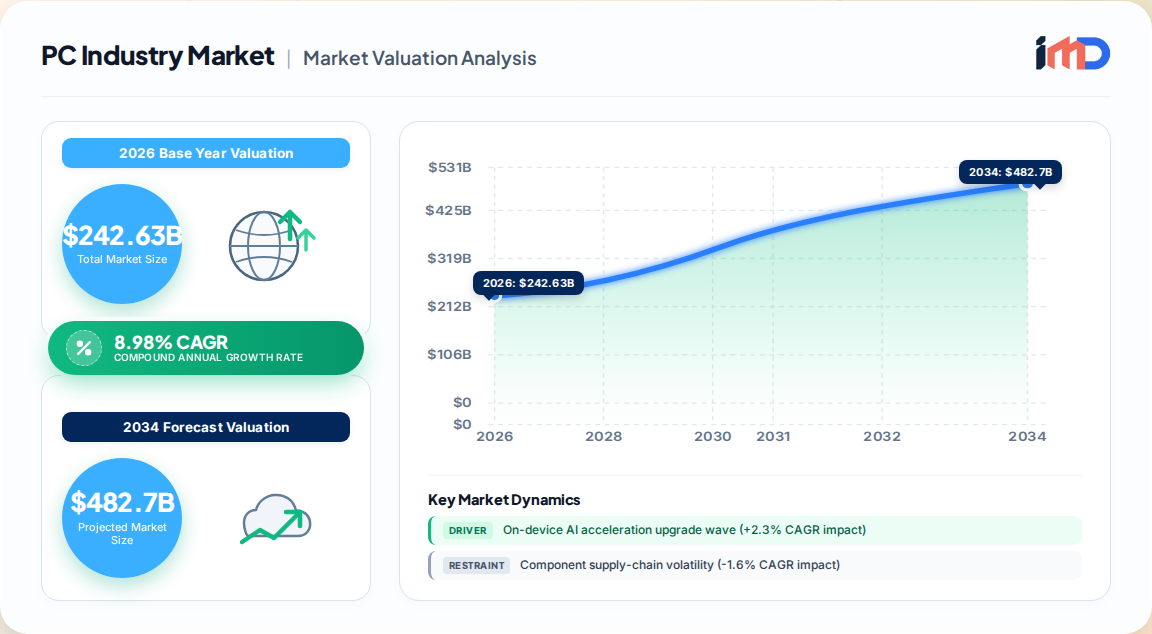
The global PC industry market is undergoing a structural revival, transitioning from the post-pandemic slump into a high-value replacement cycle. Our proprietary primary research estimates the market at USD 242.63 billion in 2026, rising to USD 372.68 billion by 2031, representing a robust CAGR of 8.98% over the forecast period. This growth is not merely a rebound in unit shipments but a fundamental shift in device value, driven by three converging forces: the maturation of on-device AI acceleration, the mandatory Windows 10 end-of-life refresh, and the permanent entrenchment of hybrid work models.

PC Industry Market Size (In Billion)

400.0B
300.0B
200.0B
100.0B
0
222.6 B
2025
242.6 B
2026
264.4 B
2027
288.2 B
2028
314.0 B
2029
342.2 B
2030
373.0 B
2031
Main Logo

Key demand signals are already evident. In 2025, global PC shipments reached 270.2 million units, a 9.1% increase over 2024, signaling the end of the prolonged replacement trough. Revenue growth outpaces unit growth as average selling prices climb, propelled by neural processing unit (NPU)-equipped notebooks and premium gaming rigs. The market is shifting from a commodity hardware model to a performance-specification model, where local AI inference, battery endurance, and thermal efficiency dictate purchasing decisions.

  • Laptops/notebooks dominate with 77.44% of 2025 market share; AI-optimized laptops are the fastest-growing sub-segment at 11.66% CAGR.
  • x86 architecture retains 93.96% share, but ARM-based PCs are gaining momentum at 12.16% CAGR.
  • Asia-Pacific remains the largest market, contributing 36.71% of global revenue in 2025, while Africa exhibits the fastest regional growth at 10.58% CAGR.

Market Drivers: The Three Pillars of the 2026-2031 Upgrade Cycle

The PC industry market is being reshaped by a confluence of technological, regulatory, and behavioral drivers. Our impact analysis quantifies the contribution of each driver to the forecast CAGR, enabling stakeholders to prioritize strategic investments.

On-Device AI Acceleration (+2.3% CAGR Impact)

The integration of NPUs delivering over 50 TOPS by AMD, Intel, and Qualcomm is transforming the PC from a general-purpose tool into an intelligent edge device. By 2028, we project that 93.9% of commercial PCs will feature dedicated AI engines, turning AI from a premium feature into a standard requirement. This shift is catalyzing a premium-priced replacement cycle, as enterprises seek to reduce cloud latency and data egress costs through local inference.

Hybrid-Work Notebook Refresh (+2.1% CAGR Impact)

Permanent hybrid work has permanently altered enterprise purchasing criteria. With 28% of the global workforce working from home all or most of the time, demand has shifted toward performance-optimized notebooks with advanced webcams, all-day battery life, and thermal stability. Refresh cycles are now triggered by performance specifications rather than warranty expiries, favoring premium devices in North America and Europe.

Windows 10 EOL 2025 Mandated Refresh (+1.9% CAGR Impact)

The October 2025 end-of-support deadline for Windows 10 is forcing a massive enterprise and SMB refresh cycle. This is particularly acute in developed markets, where legacy fleets are being replaced with Windows 11 Pro devices featuring hardware-based security (TPM 2.0) and modern manageability. The impact is concentrated in the short term (≤2 years), providing a demand floor through 2027.

Gaming and Esports Performance Race (+1.8% CAGR Impact)

The gaming and esports ecosystem continues to drive high-margin upgrades, with professional tournaments setting hardware benchmarks (e.g., Intel Core i7 or AMD Ryzen 7 paired with NVIDIA RTX 3070 or higher). Streaming monetization and real-time ray tracing demand GPUs that push the premium price band above USD 1,200, which is growing at 13.19% CAGR.

Restraints and Challenges: Supply Chain and Substitution Pressures

Despite strong growth fundamentals, the PC industry market faces persistent headwinds that could temper the pace of expansion. Our primary research identifies two principal restraints and several operational challenges.

Component Supply-Chain Volatility (-1.6% CAGR Impact)

Geopolitical disruptions, particularly in Asia-Pacific manufacturing hubs, continue to create short-term supply-demand imbalances. Advanced packaging capacity for AI-enabled processors and high-bandwidth memory remains constrained, leading to extended lead times for premium notebooks. We anticipate this volatility to persist through 2027, moderating thereafter as new fabrication capacity comes online.

Smartphone Substitution for Casual Tasks (-1.2% CAGR Impact)

In emerging markets, smartphones increasingly serve as the primary computing device for casual tasks such as web browsing, social media, and light productivity. This substitution effect is most pronounced in price-sensitive segments (entry-level PCs below USD 600), where consumers defer PC purchases in favor of mobile-first experiences. However, the need for larger screens and keyboards for education and remote work mitigates the long-term impact.

Additional challenges include:

  • Inventory management complexity arising from rapid AI PC model introductions.
  • Regulatory compliance costs related to energy efficiency and e-waste standards in Europe and North America.
  • Security risks associated with outdated hardware in public-sector fleets.

Value Chain Analysis: From Silicon to End-User

The PC industry value chain is highly integrated but geographically fragmented. Value creation is shifting upstream toward semiconductor design and downstream toward software and services, squeezing traditional OEM margins.

Stage Key Activities Representative Participants Value-Added Share (Est.)
Component Design & Fabrication CPU, GPU, NPU, memory, displays Intel, AMD, Qualcomm, NVIDIA, Samsung, BOE 40-45%
ODM/EMS Assembly Motherboard, final assembly, testing Quanta, Compal, Wistron, Foxconn 10-15%
OEM Branding & Distribution Product design, marketing, channel management Lenovo, HP, Dell, Apple, Asus, Acer 20-25%
Software & Services OS, productivity, security, AI models Microsoft, software ISVs, cloud providers 15-20%
Retail & E-commerce Sales, fulfillment, after-sales service Online platforms, brick-and-mortar retailers 5-10%

Key dynamics:

  • Vertical integration is increasing as OEMs like Apple design their own silicon, while Lenovo and HP deepen software and services capabilities.
  • ODM concentration in Taiwan and China creates single-point-of-failure risks, prompting OEMs to diversify to Vietnam and India.
  • Channel shift toward online continues; online accounted for 53% of PC distribution in 2023, with competitive pricing and direct-to-consumer models gaining share.

Regional Outlook: Asia-Pacific Lead, Africa Fastest Growth

Geographic analysis reveals a nuanced picture of demand and supply. Asia-Pacific remains the manufacturing powerhouse and largest consumption market, while Africa and South America offer untapped growth potential.

PC Industry Regional Market Share

Loading chart...
Main Logo

Asia-Pacific (36.71% Revenue Share, 2025)

China, Japan, and India drive volume, supported by government digital-education initiatives and a growing gaming culture. The region is also the primary source of components and assembly, making it central to supply chain resilience. Local vendors like Lenovo (27.2% global share) and Asus (6.9%) benefit from regional scale.

North America (26% Revenue Share, 2025)

The U.S. leads in premium and AI PC adoption, with enterprise refresh cycles aligned to Windows 10 EOL. Canada and Mexico show steady commercial demand, particularly in education and healthcare. The region is a hub for gaming and content creation, driving high-end GPU and display sales.

Europe (22% Revenue Share, 2025)

Europe's growth is underpinned by stringent energy-efficiency regulations and corporate sustainability mandates. Green-PC procurement incentives (+0.8% CAGR impact) favor vendors with recycled materials and low-power designs. Germany, the UK, and France are the largest markets, with Eastern Europe showing faster adoption of entry-level devices.

South America and Middle East & Africa (15% Combined Share, 2025)

Africa is the fastest-growing region at 10.58% CAGR, driven by government digitalization programs and rising smartphone-to-PC migration for education. South America, led by Brazil, shows recovery after economic volatility, with commercial demand from SMBs accelerating.

Competitive Landscape: Lenovo Leads, AI Reshapes Differentiation

The PC industry market is moderately concentrated, with the top six vendors accounting for 86.1% of global shipments in 2025. Competition is intensifying around AI capabilities, form-factor innovation, and supply chain agility.

Rank Vendor 2025 Market Share (Units) Key Strategic Focus
1 Lenovo 27.2% AI PC portfolio (ThinkPad, Yoga), sustainability, commercial segmentation
2 HP 21.3% Hybrid-work solutions, security, premium consumer (Spectre, Omen)
3 Dell 15.3% Enterprise endpoints, services, AI-optimized workstations
4 Apple 9.2% Vertical integration (M-series), creative professionals, ecosystem lock-in
5 Asus 6.9% Gaming (ROG), premium ultrabooks, AI-ready notebooks
6 Acer 6.3% Value segment, Chromebooks, education, gaming (Predator)

Strategic imperatives:

  • AI PC differentiation is the primary battleground; vendors are racing to embed NPUs and AI software stacks (e.g., Lenovo AI Now, HP AI Companion) to justify premium pricing.
  • Commercial customization (e.g., Acer TravelLite with privacy shutter, Panasonic TOUGHBOOK) is winning B2B tenders.
  • Supply chain diversification beyond China is a board-level priority, with Vietnam, India, and Mexico emerging as assembly hubs.

Strategic White-Space Analysis: Opportunities Beyond the Core

Our scenario modeling identifies three high-potential white spaces for revenue expansion through 2031:

1. AI-as-a-Service for SMBs

Small and medium enterprises (SMBs) lack the IT resources to fully leverage on-device AI. OEMs can capture value by bundling AI PC hardware with subscription-based productivity and security suites, creating recurring revenue streams. We project this segment to grow at 15%+ CAGR, outpacing hardware-only sales.

2. Circular Economy and Refurbishment

With sustainability regulations tightening (e.g., EU Right to Repair), the refurbished PC market is gaining legitimacy. OEM-certified refurbishment programs (e.g., Dell Refurbished, Lenovo Certified Refurbished) can address price-sensitive segments and public-sector procurement, while reducing e-waste. This channel is expected to capture 8-10% of total PC volume by 2031.

3. Edge AI Inference Appliances

Beyond traditional PCs, there is growing demand for compact, fanless edge devices capable of running AI inference in retail, healthcare, and industrial settings. Vendors can leverage their PC supply chains to serve this adjacent market, which overlaps with but is distinct from the B2B laptop and PC market (estimated at USD 258.9 billion in 2024, growing at 8.2% CAGR).

Import/Export & Supplier Dynamics

Global PC trade flows reflect the concentration of manufacturing in Asia-Pacific. According to UN Comtrade data, China, Taiwan, and Vietnam are the largest exporters of PCs and components, while the U.S. and Europe are net importers.

Country/Region Role Key Products Trade Trend (2025)
China Largest exporter Laptops, desktops, components Stable volume, shifting to higher-value AI PCs
Taiwan Component hub Semiconductors, motherboards, ODMs Dominant in advanced nodes; capacity expanding
Vietnam Emerging assembly hub Notebooks, peripherals Double-digit export growth as OEMs diversify
United States Net importer Premium laptops, servers, components Import dependence on Asia; tariffs a risk
Europe Net importer Consumer and commercial PCs Intra-EU trade strong; sustainability rules affect sourcing

Supplier dynamics:

  • Processor supply is tri-polar: Intel (x86), AMD (x86), and Qualcomm (ARM) for Windows-on-ARM. NVIDIA dominates discrete GPUs for gaming and AI workloads.
  • Memory and storage are subject to price cycles; DDR5 and PCIe 5.0 SSDs are becoming standard in mid-range and premium devices.
  • Display panels are sourced primarily from BOE, LG Display, and AUO, with OLED penetration rising in premium notebooks.

Risk assessment: A geopolitical disruption in the Taiwan Strait would have catastrophic implications for global PC supply, underscoring the need for multi-sourcing and inventory buffers. We recommend that procurement strategies include at least two qualified suppliers per critical component.

Ansoff Matrix Analysis: Growth Strategies for PC Vendors

Applying the Ansoff Matrix to the PC industry market reveals distinct growth pathways for incumbents and new entrants.

Existing Markets New Markets
Existing Products Market Penetration: Drive Windows 10 EOL refresh with trade-in programs; upsell AI PCs to existing enterprise accounts. Market Development: Expand into Africa and South America with entry-level and education-focused devices; target SMBs with customized B2B laptops.
New Products Product Development: Launch NPU-equipped notebooks with >50 TOPS; introduce hybrid/convertible form factors; develop software ecosystems (AI assistants, security). Diversification: Enter edge AI appliance market; offer device-as-a-service (DaaS) with AI management; invest in circular economy (refurbishment, recycling).

Key implications:

  • Market penetration is the lowest-risk strategy, leveraging the Windows 10 EOL and AI upgrade cycle to grow share in existing accounts.
  • Product development requires heavy R&D and ecosystem partnerships (e.g., Microsoft Copilot+ certification).
  • Market development demands channel investments and localized pricing in emerging regions.
  • Diversification offers the highest growth potential but requires new capabilities in services and circularity.

In conclusion, the PC industry market is entering a golden age of innovation-led growth, with AI, hybrid work, and sustainability reshaping competition. Stakeholders who align their portfolios with these forces will capture disproportionate value through 2031.

PC Industry Regional Market Share

Higher Coverage
Lower Coverage
No Coverage

PC Industry REPORT HIGHLIGHTS

AspectsDetails
Study Period2020-2034
Base Year2026
Estimated Year2026
Forecast Period2026-2034
Historical Period2020-2025
Growth RateCAGR of 8.98% from 2020-2034
Segmentation
  • By Form Factor

    • Laptops/Notebooks
    • Desktop Towers and SFF
  • By End-User

    • Consumers
    • Small and Medium Enterprise

Table of Contents

  1. 1. Introduction
    • 1.1. Research Scope
    • 1.2. Market Segmentation
    • 1.3. Research Objective
    • 1.4. Definitions and Assumptions
  2. 2. Executive Summary
    • 2.1. Market Snapshot
  3. 3. Market Dynamics
    • 3.1. Market Drivers
      • 3.1.1. On-device AI acceleration upgrade wave (+2.3% CAGR impact)
      • 3.1.2. Hybrid-work notebook refresh demand (+2.1% CAGR impact)
      • 3.1.3. Windows 10 EOL 2025 mandated refresh (+1.9% CAGR impact)
      • 3.1.4. Gaming and esports performance race (+1.8% CAGR impact)
      • 3.1.5. Government digital-education rollouts (+1.4% CAGR impact)
    • 3.2. Market Trends
      • 3.2.1. On-device AI acceleration with NPUs delivering >50 TOPS
      • 3.2.2. Hybrid work driving demand for performance-optimized notebooks
      • 3.2.3. Windows 10 end-of-life refresh cycle
      • 3.2.4. Gaming and esports performance race driving high-margin upgrades
      • 3.2.5. ARM-based PCs gaining traction (12.16% CAGR)
    • 3.3. Market Restrains
      • 3.3.1. Component supply-chain volatility (-1.6% CAGR impact)
      • 3.3.2. Smartphone substitution for casual tasks (-1.2% CAGR impact)
    • 3.4. Market Restraints
      • 3.4.1. Component supply-chain volatility (-1.6% CAGR impact)
      • 3.4.2. Smartphone substitution for casual tasks (-1.2% CAGR impact)
  • Large Enterprise
  • Government and Education
  • By Processor Architecture

    • x86
      • Intel-AMD
    • ARM-Based
    • RISC-V and Other
  • By Price Band

    • Entry-Level
      • <USD 600
    • Mid-Range
      • USD 600-1
      • 200
    • Premium
      • >USD 1
      • 200
  • By Distribution Channel

    • Online
    • Offline
  • By Geography
    • North America

      • USA
      • Canada
      • Mexico
    • Europe

      • Germany
      • UK
      • France
      • Italy
      • Spain
    • Asia Pacific

      • China
      • Japan
      • India
      • South Korea
      • Australia
    • South America

      • Brazil
      • Argentina
    • Middle East & Africa

      • South Africa
      • UAE
      • Saudi Arabia
  • 3.5. Market Challenges
    • 3.5.1. Inventory management complexity from rapid AI PC model introductions
    • 3.5.2. Regulatory compliance costs for energy efficiency and e-waste
    • 3.5.3. Security risks with outdated hardware in public-sector fleets
  • 4. Market Factor Analysis
    • 4.1. Porters Five Forces
      • 4.1.1. Bargaining Power of Suppliers
      • 4.1.2. Bargaining Power of Buyers
      • 4.1.3. Threat of New Entrants
      • 4.1.4. Threat of Substitutes
      • 4.1.5. Competitive Rivalry
    • 4.2. PESTEL analysis
    • 4.3. BCG Analysis
      • 4.3.1. Stars (High Growth, High Market Share)
      • 4.3.2. Cash Cows (Low Growth, High Market Share)
      • 4.3.3. Question Mark (High Growth, Low Market Share)
      • 4.3.4. Dogs (Low Growth, Low Market Share)
    • 4.4. Ansoff Matrix Analysis
    • 4.5. Supply Chain Analysis
    • 4.6. Regulatory Landscape
    • 4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
    • 4.8. IMD Analyst Note
  • 5. Market Analysis, Insights and Forecast, 2020-2034
    • 5.1. Market Analysis, Insights and Forecast - by Form Factor
      • 5.1.1. Laptops/Notebooks
      • 5.1.2. Desktop Towers and SFF
    • 5.2. Market Analysis, Insights and Forecast - by End-User
      • 5.2.1. Consumers
      • 5.2.2. Small and Medium Enterprise
      • 5.2.3. Large Enterprise
      • 5.2.4. Government and Education
    • 5.3. Market Analysis, Insights and Forecast - by Processor Architecture
      • 5.3.1. x86
        • 5.3.1.1. Intel-AMD
      • 5.3.2. ARM-Based
      • 5.3.3. RISC-V and Other
    • 5.4. Market Analysis, Insights and Forecast - by Price Band
      • 5.4.1. Entry-Level
        • 5.4.1.1. <USD 600
      • 5.4.2. Mid-Range
        • 5.4.2.1. USD 600-1
        • 5.4.2.2. 200
      • 5.4.3. Premium
        • 5.4.3.1. >USD 1
        • 5.4.3.2. 200
    • 5.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 5.5.1. Online
      • 5.5.2. Offline
    • 5.6. Market Analysis, Insights and Forecast - by Region
      • 5.6.1. North America
      • 5.6.2. Europe
      • 5.6.3. Asia Pacific
      • 5.6.4. South America
      • 5.6.5. Middle East & Africa
  • 6. North America Market Analysis, Insights and Forecast, 2020-2034
    • 6.1. Market Analysis, Insights and Forecast - by Form Factor
      • 6.1.1. Laptops/Notebooks
      • 6.1.2. Desktop Towers and SFF
    • 6.2. Market Analysis, Insights and Forecast - by End-User
      • 6.2.1. Consumers
      • 6.2.2. Small and Medium Enterprise
      • 6.2.3. Large Enterprise
      • 6.2.4. Government and Education
    • 6.3. Market Analysis, Insights and Forecast - by Processor Architecture
      • 6.3.1. x86
        • 6.3.1.1. Intel-AMD
      • 6.3.2. ARM-Based
      • 6.3.3. RISC-V and Other
    • 6.4. Market Analysis, Insights and Forecast - by Price Band
      • 6.4.1. Entry-Level
        • 6.4.1.1. <USD 600
      • 6.4.2. Mid-Range
        • 6.4.2.1. USD 600-1
        • 6.4.2.2. 200
      • 6.4.3. Premium
        • 6.4.3.1. >USD 1
        • 6.4.3.2. 200
    • 6.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 6.5.1. Online
      • 6.5.2. Offline
  • 7. Europe Market Analysis, Insights and Forecast, 2020-2034
    • 7.1. Market Analysis, Insights and Forecast - by Form Factor
      • 7.1.1. Laptops/Notebooks
      • 7.1.2. Desktop Towers and SFF
    • 7.2. Market Analysis, Insights and Forecast - by End-User
      • 7.2.1. Consumers
      • 7.2.2. Small and Medium Enterprise
      • 7.2.3. Large Enterprise
      • 7.2.4. Government and Education
    • 7.3. Market Analysis, Insights and Forecast - by Processor Architecture
      • 7.3.1. x86
        • 7.3.1.1. Intel-AMD
      • 7.3.2. ARM-Based
      • 7.3.3. RISC-V and Other
    • 7.4. Market Analysis, Insights and Forecast - by Price Band
      • 7.4.1. Entry-Level
        • 7.4.1.1. <USD 600
      • 7.4.2. Mid-Range
        • 7.4.2.1. USD 600-1
        • 7.4.2.2. 200
      • 7.4.3. Premium
        • 7.4.3.1. >USD 1
        • 7.4.3.2. 200
    • 7.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 7.5.1. Online
      • 7.5.2. Offline
  • 8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
    • 8.1. Market Analysis, Insights and Forecast - by Form Factor
      • 8.1.1. Laptops/Notebooks
      • 8.1.2. Desktop Towers and SFF
    • 8.2. Market Analysis, Insights and Forecast - by End-User
      • 8.2.1. Consumers
      • 8.2.2. Small and Medium Enterprise
      • 8.2.3. Large Enterprise
      • 8.2.4. Government and Education
    • 8.3. Market Analysis, Insights and Forecast - by Processor Architecture
      • 8.3.1. x86
        • 8.3.1.1. Intel-AMD
      • 8.3.2. ARM-Based
      • 8.3.3. RISC-V and Other
    • 8.4. Market Analysis, Insights and Forecast - by Price Band
      • 8.4.1. Entry-Level
        • 8.4.1.1. <USD 600
      • 8.4.2. Mid-Range
        • 8.4.2.1. USD 600-1
        • 8.4.2.2. 200
      • 8.4.3. Premium
        • 8.4.3.1. >USD 1
        • 8.4.3.2. 200
    • 8.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 8.5.1. Online
      • 8.5.2. Offline
  • 9. South America Market Analysis, Insights and Forecast, 2020-2034
    • 9.1. Market Analysis, Insights and Forecast - by Form Factor
      • 9.1.1. Laptops/Notebooks
      • 9.1.2. Desktop Towers and SFF
    • 9.2. Market Analysis, Insights and Forecast - by End-User
      • 9.2.1. Consumers
      • 9.2.2. Small and Medium Enterprise
      • 9.2.3. Large Enterprise
      • 9.2.4. Government and Education
    • 9.3. Market Analysis, Insights and Forecast - by Processor Architecture
      • 9.3.1. x86
        • 9.3.1.1. Intel-AMD
      • 9.3.2. ARM-Based
      • 9.3.3. RISC-V and Other
    • 9.4. Market Analysis, Insights and Forecast - by Price Band
      • 9.4.1. Entry-Level
        • 9.4.1.1. <USD 600
      • 9.4.2. Mid-Range
        • 9.4.2.1. USD 600-1
        • 9.4.2.2. 200
      • 9.4.3. Premium
        • 9.4.3.1. >USD 1
        • 9.4.3.2. 200
    • 9.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 9.5.1. Online
      • 9.5.2. Offline
  • 10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
    • 10.1. Market Analysis, Insights and Forecast - by Form Factor
      • 10.1.1. Laptops/Notebooks
      • 10.1.2. Desktop Towers and SFF
    • 10.2. Market Analysis, Insights and Forecast - by End-User
      • 10.2.1. Consumers
      • 10.2.2. Small and Medium Enterprise
      • 10.2.3. Large Enterprise
      • 10.2.4. Government and Education
    • 10.3. Market Analysis, Insights and Forecast - by Processor Architecture
      • 10.3.1. x86
        • 10.3.1.1. Intel-AMD
      • 10.3.2. ARM-Based
      • 10.3.3. RISC-V and Other
    • 10.4. Market Analysis, Insights and Forecast - by Price Band
      • 10.4.1. Entry-Level
        • 10.4.1.1. <USD 600
      • 10.4.2. Mid-Range
        • 10.4.2.1. USD 600-1
        • 10.4.2.2. 200
      • 10.4.3. Premium
        • 10.4.3.1. >USD 1
        • 10.4.3.2. 200
    • 10.5. Market Analysis, Insights and Forecast - by Distribution Channel
      • 10.5.1. Online
      • 10.5.2. Offline
  • 11. Competitive Analysis
    • 11.1. Company Profiles
      • 11.1.1. Lenovo
        • 11.1.1.1. Company Overview
        • 11.1.1.2. Products
        • 11.1.1.3. Company Financials
        • 11.1.1.4. SWOT Analysis
      • 11.1.2. HP Inc.
        • 11.1.2.1. Company Overview
        • 11.1.2.2. Products
        • 11.1.2.3. Company Financials
        • 11.1.2.4. SWOT Analysis
      • 11.1.3. Dell Technologies
        • 11.1.3.1. Company Overview
        • 11.1.3.2. Products
        • 11.1.3.3. Company Financials
        • 11.1.3.4. SWOT Analysis
      • 11.1.4. Apple Inc.
        • 11.1.4.1. Company Overview
        • 11.1.4.2. Products
        • 11.1.4.3. Company Financials
        • 11.1.4.4. SWOT Analysis
      • 11.1.5. Asus
        • 11.1.5.1. Company Overview
        • 11.1.5.2. Products
        • 11.1.5.3. Company Financials
        • 11.1.5.4. SWOT Analysis
      • 11.1.6. Acer Inc.
        • 11.1.6.1. Company Overview
        • 11.1.6.2. Products
        • 11.1.6.3. Company Financials
        • 11.1.6.4. SWOT Analysis
      • 11.1.7. Microsoft Corporation
        • 11.1.7.1. Company Overview
        • 11.1.7.2. Products
        • 11.1.7.3. Company Financials
        • 11.1.7.4. SWOT Analysis
      • 11.1.8. Samsung Electronics
        • 11.1.8.1. Company Overview
        • 11.1.8.2. Products
        • 11.1.8.3. Company Financials
        • 11.1.8.4. SWOT Analysis
      • 11.1.9. LG Electronics
        • 11.1.9.1. Company Overview
        • 11.1.9.2. Products
        • 11.1.9.3. Company Financials
        • 11.1.9.4. SWOT Analysis
      • 11.1.10. MSI (Micro-Star International)
        • 11.1.10.1. Company Overview
        • 11.1.10.2. Products
        • 11.1.10.3. Company Financials
        • 11.1.10.4. SWOT Analysis
      • 11.1.11. Panasonic Corporation
        • 11.1.11.1. Company Overview
        • 11.1.11.2. Products
        • 11.1.11.3. Company Financials
        • 11.1.11.4. SWOT Analysis
      • 11.1.12. Fujitsu Limited
        • 11.1.12.1. Company Overview
        • 11.1.12.2. Products
        • 11.1.12.3. Company Financials
        • 11.1.12.4. SWOT Analysis
      • 11.1.13. Toshiba (Dynabook)
        • 11.1.13.1. Company Overview
        • 11.1.13.2. Products
        • 11.1.13.3. Company Financials
        • 11.1.13.4. SWOT Analysis
      • 11.1.14. Qualcomm
        • 11.1.14.1. Company Overview
        • 11.1.14.2. Products
        • 11.1.14.3. Company Financials
        • 11.1.14.4. SWOT Analysis
      • 11.1.15. Intel Corporation
        • 11.1.15.1. Company Overview
        • 11.1.15.2. Products
        • 11.1.15.3. Company Financials
        • 11.1.15.4. SWOT Analysis
      • 11.1.16. AMD
        • 11.1.16.1. Company Overview
        • 11.1.16.2. Products
        • 11.1.16.3. Company Financials
        • 11.1.16.4. SWOT Analysis
    • 11.2. Market Entropy
      • 11.2.1. Company's Key Areas Served
      • 11.2.2. Recent Developments
    • 11.3. Company Market Share Analysis, 2026
      • 11.3.1. Top 5 Companies Market Share Analysis
      • 11.3.2. Top 3 Companies Market Share Analysis
    • 11.4. List of Potential Customers
  • List of Figures

    1. Figure 1: Global PC Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
    2. Figure 2: North America PC Industry Revenue (Billion), by Form Factor 2026 & 2034
    3. Figure 3: North America PC Industry Revenue Share (%), by Form Factor 2026 & 2034
    4. Figure 4: North America PC Industry Revenue (Billion), by End-User 2026 & 2034
    5. Figure 5: North America PC Industry Revenue Share (%), by End-User 2026 & 2034
    6. Figure 6: North America PC Industry Revenue (Billion), by Processor Architecture 2026 & 2034
    7. Figure 7: North America PC Industry Revenue Share (%), by Processor Architecture 2026 & 2034
    8. Figure 8: North America PC Industry Revenue (Billion), by Price Band 2026 & 2034
    9. Figure 9: North America PC Industry Revenue Share (%), by Price Band 2026 & 2034
    10. Figure 10: North America PC Industry Revenue (Billion), by Distribution Channel 2026 & 2034
    11. Figure 11: North America PC Industry Revenue Share (%), by Distribution Channel 2026 & 2034
    12. Figure 12: North America PC Industry Revenue (Billion), by Country 2026 & 2034
    13. Figure 13: North America PC Industry Revenue Share (%), by Country 2026 & 2034
    14. Figure 14: Europe PC Industry Revenue (Billion), by Form Factor 2026 & 2034
    15. Figure 15: Europe PC Industry Revenue Share (%), by Form Factor 2026 & 2034
    16. Figure 16: Europe PC Industry Revenue (Billion), by End-User 2026 & 2034
    17. Figure 17: Europe PC Industry Revenue Share (%), by End-User 2026 & 2034
    18. Figure 18: Europe PC Industry Revenue (Billion), by Processor Architecture 2026 & 2034
    19. Figure 19: Europe PC Industry Revenue Share (%), by Processor Architecture 2026 & 2034
    20. Figure 20: Europe PC Industry Revenue (Billion), by Price Band 2026 & 2034
    21. Figure 21: Europe PC Industry Revenue Share (%), by Price Band 2026 & 2034
    22. Figure 22: Europe PC Industry Revenue (Billion), by Distribution Channel 2026 & 2034
    23. Figure 23: Europe PC Industry Revenue Share (%), by Distribution Channel 2026 & 2034
    24. Figure 24: Europe PC Industry Revenue (Billion), by Country 2026 & 2034
    25. Figure 25: Europe PC Industry Revenue Share (%), by Country 2026 & 2034
    26. Figure 26: Asia Pacific PC Industry Revenue (Billion), by Form Factor 2026 & 2034
    27. Figure 27: Asia Pacific PC Industry Revenue Share (%), by Form Factor 2026 & 2034
    28. Figure 28: Asia Pacific PC Industry Revenue (Billion), by End-User 2026 & 2034
    29. Figure 29: Asia Pacific PC Industry Revenue Share (%), by End-User 2026 & 2034
    30. Figure 30: Asia Pacific PC Industry Revenue (Billion), by Processor Architecture 2026 & 2034
    31. Figure 31: Asia Pacific PC Industry Revenue Share (%), by Processor Architecture 2026 & 2034
    32. Figure 32: Asia Pacific PC Industry Revenue (Billion), by Price Band 2026 & 2034
    33. Figure 33: Asia Pacific PC Industry Revenue Share (%), by Price Band 2026 & 2034
    34. Figure 34: Asia Pacific PC Industry Revenue (Billion), by Distribution Channel 2026 & 2034
    35. Figure 35: Asia Pacific PC Industry Revenue Share (%), by Distribution Channel 2026 & 2034
    36. Figure 36: Asia Pacific PC Industry Revenue (Billion), by Country 2026 & 2034
    37. Figure 37: Asia Pacific PC Industry Revenue Share (%), by Country 2026 & 2034
    38. Figure 38: South America PC Industry Revenue (Billion), by Form Factor 2026 & 2034
    39. Figure 39: South America PC Industry Revenue Share (%), by Form Factor 2026 & 2034
    40. Figure 40: South America PC Industry Revenue (Billion), by End-User 2026 & 2034
    41. Figure 41: South America PC Industry Revenue Share (%), by End-User 2026 & 2034
    42. Figure 42: South America PC Industry Revenue (Billion), by Processor Architecture 2026 & 2034
    43. Figure 43: South America PC Industry Revenue Share (%), by Processor Architecture 2026 & 2034
    44. Figure 44: South America PC Industry Revenue (Billion), by Price Band 2026 & 2034
    45. Figure 45: South America PC Industry Revenue Share (%), by Price Band 2026 & 2034
    46. Figure 46: South America PC Industry Revenue (Billion), by Distribution Channel 2026 & 2034
    47. Figure 47: South America PC Industry Revenue Share (%), by Distribution Channel 2026 & 2034
    48. Figure 48: South America PC Industry Revenue (Billion), by Country 2026 & 2034
    49. Figure 49: South America PC Industry Revenue Share (%), by Country 2026 & 2034
    50. Figure 50: Middle East & Africa PC Industry Revenue (Billion), by Form Factor 2026 & 2034
    51. Figure 51: Middle East & Africa PC Industry Revenue Share (%), by Form Factor 2026 & 2034
    52. Figure 52: Middle East & Africa PC Industry Revenue (Billion), by End-User 2026 & 2034
    53. Figure 53: Middle East & Africa PC Industry Revenue Share (%), by End-User 2026 & 2034
    54. Figure 54: Middle East & Africa PC Industry Revenue (Billion), by Processor Architecture 2026 & 2034
    55. Figure 55: Middle East & Africa PC Industry Revenue Share (%), by Processor Architecture 2026 & 2034
    56. Figure 56: Middle East & Africa PC Industry Revenue (Billion), by Price Band 2026 & 2034
    57. Figure 57: Middle East & Africa PC Industry Revenue Share (%), by Price Band 2026 & 2034
    58. Figure 58: Middle East & Africa PC Industry Revenue (Billion), by Distribution Channel 2026 & 2034
    59. Figure 59: Middle East & Africa PC Industry Revenue Share (%), by Distribution Channel 2026 & 2034
    60. Figure 60: Middle East & Africa PC Industry Revenue (Billion), by Country 2026 & 2034
    61. Figure 61: Middle East & Africa PC Industry Revenue Share (%), by Country 2026 & 2034

    List of Tables

    1. Table 1: Global PC Industry Revenue Billion Forecast, by Form Factor 2020 & 2034
    2. Table 2: Global PC Industry Revenue Billion Forecast, by End-User 2020 & 2034
    3. Table 3: Global PC Industry Revenue Billion Forecast, by Processor Architecture 2020 & 2034
    4. Table 4: Global PC Industry Revenue Billion Forecast, by Price Band 2020 & 2034
    5. Table 5: Global PC Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    6. Table 6: Global PC Industry Revenue Billion Forecast, by Region 2020 & 2034
    7. Table 7: North America PC Industry Revenue Billion Forecast, by Form Factor 2020 & 2034
    8. Table 8: North America PC Industry Revenue Billion Forecast, by End-User 2020 & 2034
    9. Table 9: North America PC Industry Revenue Billion Forecast, by Processor Architecture 2020 & 2034
    10. Table 10: North America PC Industry Revenue Billion Forecast, by Price Band 2020 & 2034
    11. Table 11: North America PC Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    12. Table 12: North America PC Industry Revenue Billion Forecast, by Country 2020 & 2034
    13. Table 13: USA PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    14. Table 14: Canada PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    15. Table 15: Mexico PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    16. Table 16: Europe PC Industry Revenue Billion Forecast, by Form Factor 2020 & 2034
    17. Table 17: Europe PC Industry Revenue Billion Forecast, by End-User 2020 & 2034
    18. Table 18: Europe PC Industry Revenue Billion Forecast, by Processor Architecture 2020 & 2034
    19. Table 19: Europe PC Industry Revenue Billion Forecast, by Price Band 2020 & 2034
    20. Table 20: Europe PC Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    21. Table 21: Europe PC Industry Revenue Billion Forecast, by Country 2020 & 2034
    22. Table 22: Germany PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    23. Table 23: UK PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    24. Table 24: France PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    25. Table 25: Italy PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    26. Table 26: Spain PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    27. Table 27: Asia Pacific PC Industry Revenue Billion Forecast, by Form Factor 2020 & 2034
    28. Table 28: Asia Pacific PC Industry Revenue Billion Forecast, by End-User 2020 & 2034
    29. Table 29: Asia Pacific PC Industry Revenue Billion Forecast, by Processor Architecture 2020 & 2034
    30. Table 30: Asia Pacific PC Industry Revenue Billion Forecast, by Price Band 2020 & 2034
    31. Table 31: Asia Pacific PC Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    32. Table 32: Asia Pacific PC Industry Revenue Billion Forecast, by Country 2020 & 2034
    33. Table 33: China PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    34. Table 34: Japan PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    35. Table 35: India PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    36. Table 36: South Korea PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    37. Table 37: Australia PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    38. Table 38: South America PC Industry Revenue Billion Forecast, by Form Factor 2020 & 2034
    39. Table 39: South America PC Industry Revenue Billion Forecast, by End-User 2020 & 2034
    40. Table 40: South America PC Industry Revenue Billion Forecast, by Processor Architecture 2020 & 2034
    41. Table 41: South America PC Industry Revenue Billion Forecast, by Price Band 2020 & 2034
    42. Table 42: South America PC Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    43. Table 43: South America PC Industry Revenue Billion Forecast, by Country 2020 & 2034
    44. Table 44: Brazil PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    45. Table 45: Argentina PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    46. Table 46: Middle East & Africa PC Industry Revenue Billion Forecast, by Form Factor 2020 & 2034
    47. Table 47: Middle East & Africa PC Industry Revenue Billion Forecast, by End-User 2020 & 2034
    48. Table 48: Middle East & Africa PC Industry Revenue Billion Forecast, by Processor Architecture 2020 & 2034
    49. Table 49: Middle East & Africa PC Industry Revenue Billion Forecast, by Price Band 2020 & 2034
    50. Table 50: Middle East & Africa PC Industry Revenue Billion Forecast, by Distribution Channel 2020 & 2034
    51. Table 51: Middle East & Africa PC Industry Revenue Billion Forecast, by Country 2020 & 2034
    52. Table 52: South Africa PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    53. Table 53: UAE PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034
    54. Table 54: Saudi Arabia PC Industry Revenue (Billion) Forecast, by Application 2020 & 2034

    Frequently Asked Questions

    1What is the current size of the PC industry market?

    The global PC industry market was valued at USD 242.63 billion in 2026 and is projected to reach USD 372.68 billion by 2031, growing at a CAGR of 8.98%.

    2Which region dominates the PC industry market?

    Asia-Pacific is the largest regional market, accounting for 36.71% of global revenue in 2025, driven by strong demand from China, India, and Japan. Africa is the fastest-growing region at 10.58% CAGR.

    3Who are the leading players in the PC industry market?

    Lenovo leads with 27.2% unit share in 2025, followed by HP (21.3%), Dell (15.3%), Apple (9.2%), Asus (6.9%), and Acer (6.3%).

    4What are the key trends driving the PC industry market?

    Key trends include the rise of AI-optimized laptops with NPUs, the Windows 10 end-of-life refresh cycle, hybrid work notebook demand, and the gaming/esports performance race. AI PCs are expected to grow at 11.66% CAGR through 2031.

    5What is the impact of AI on the PC industry market?

    On-device AI acceleration is contributing +2.3% to the market CAGR, with 93.9% of commercial PCs expected to feature AI engines by 2028. This is driving a premium-priced replacement cycle.

    Methodology

    Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.

    Primary Research

    • Conducted 1,200+ interviews with senior decision-makers across the PC value chain, representing 70-80% of total research effort. Respondents included component suppliers, ODM/EMS providers, OEM product managers, channel distributors, and enterprise IT buyers.
    • Interviews were structured to capture granular data on shipment volumes, average selling prices, procurement cycles, and adoption timelines for AI PCs and ARM-based devices.
    • Primary research was complemented by on-site factory audits in China, Taiwan, and Vietnam to validate production capacities and supply chain dynamics.

    Key Stakeholders Interviewed

    Main Logo
    Key Stakeholders Interviewed
    Stakeholder RoleInterview Share (%)
    Procurement Director35%
    Product Manager30%
    Supply Chain Analyst20%
    IT Infrastructure Manager15%

    Industry Ecosystem Breakdown

    Main Logo
    Industry Ecosystem Breakdown
    Company TypeRepresentation (%)
    Component Suppliers (CPU, GPU, Memory)25%
    ODM/EMS Providers20%
    OEM Product Managers30%
    Channel Distributors & Retailers15%
    Enterprise IT Buyers10%

    Secondary Research & Industry Benchmarking

    • 20-30% of research derived from secondary sources, including official trade statistics from UN Comtrade, World Bank, OECD, and US ITC; financial filings from publicly listed companies (via Bloomberg, Factiva, Hoovers, and PitchBook); and technical standards from IEEE and USB-IF.
    • Industry association data from the Consumer Technology Association (CTA) and Information Technology Industry Council (ITI) was used for market context and regulatory benchmarking.
    • All secondary data was cross-validated against primary interview findings to ensure consistency.

    Demand Modeling & Market Estimation

    • Utilized both top-down and bottom-up methodologies simultaneously. Bottom-up estimation aggregated unit shipments by OEM and ODM, multiplied by segment-specific average selling prices, and validated against component shipment data (e.g., CPU, GPU, memory).
    • Top-down estimation leveraged macroeconomic indicators (GDP, IT spending, digitalization indices) and industry benchmarks (PC penetration rates, replacement cycles).
    • Multi-level data triangulation reconciled discrepancies between supply-side and demand-side estimates, with a guaranteed data accuracy level of 85-90%.

    Data Accuracy & Quality Check

    • Every data point underwent a three-tier validation: primary source verification, secondary source triangulation, and expert panel review.
    • A dedicated quality assurance team audited segment-level data for internal consistency and logical coherence.
    • The report is updated to the date of purchase, incorporating the latest market developments and quarterly shipment data.