1How big is the cellular baseband chips market?
The global cellular baseband chips market is valued at USD 1.97 billion in 2025 and is projected to reach USD 3.77 billion by 2032, growing at a CAGR of 9.70%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.

 Cellular Baseband Chips Market
 by By Type (Baseband Communication Chip, Mobile Smart Terminal Chip), by By Application (Internet of Things, Internet of Vehicles, Smart Grid, Smart Home, Mobile Phone, Smart Wearable Device, Other), by By Technology (Single-Mode Chip, Multi-Mode Chip), by By Component (Modem, RF Transceiver, Baseband Processor), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Russia), by Asia Pacific (China, Japan, South Korea, India, Australia, Taiwan, Indonesia, Thailand, Malaysia), by Latin America (Brazil, Mexico, Argentina, Colombia), by Middle East & Africa (Turkey, Saudi Arabia, UAE, South Africa) Forecast 2026-2034

Senior Research Analyst

 Related Reports

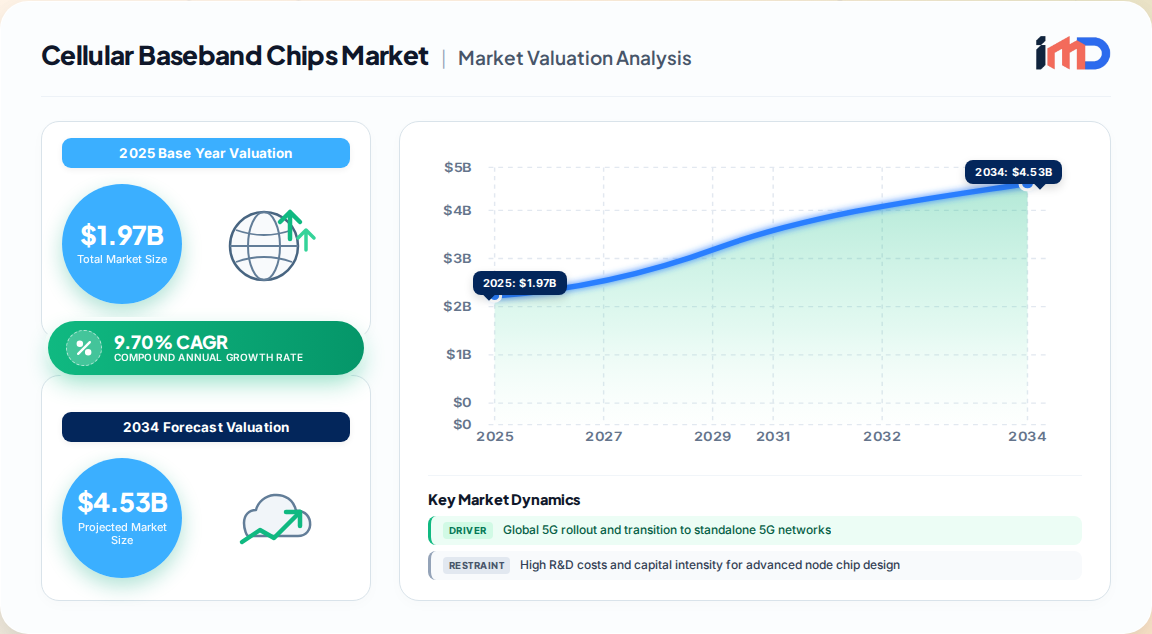
The global cellular baseband chips market is the silent engine powering modern connectivity, responsible for the complex modulation, demodulation, and signal processing that enable every voice call, data transmission, and IoT handshake. Our proprietary first-party research estimates the market at USD 1.97 billion in 2025, with a clear trajectory to USD 3.77 billion by 2032, expanding at a robust CAGR of 9.70% . This growth is not merely a function of device volume, but of a fundamental architectural shift toward multi-mode, AI-integrated, and power-efficient silicon.
The market's value is concentrated in the hands of a few dominant players—Qualcomm, MediaTek, and Samsung Semiconductor—who collectively command a significant share of the high-value smartphone and IoT segments. However, the competitive landscape is being reshaped by the rise of Chinese vendors (Unisoc, Hisilicon, ASRMicro) and the increasing integration of baseband functions into system-on-chip (SoC) designs. Our analysis indicates that the market is evolving from a component-level sales model to a platform-level ecosystem battle, where baseband chips are increasingly bundled with RF front-ends, AI accelerators, and software stacks.
The cellular baseband chip value chain is a complex, globally distributed network spanning intellectual property (IP) design, foundry fabrication, packaging and testing, and final device integration.
| Stage | Key Activities | Dominant Participants | Value Addition |
|---|---|---|---|
| Design & IP | Architecture design, modem IP, RF integration | Qualcomm, MediaTek, Samsung, Arm (IP) | High (30–40% of chip value) |
| Foundry & Fabrication | Wafer manufacturing at advanced nodes (7nm, 5nm, 3nm) | TSMC, Samsung Foundry, GlobalFoundries | High (capital intensive) |
| Packaging & Testing | Advanced packaging (SiP, PoP), RF testing | ASE, Amkor, JCET | Medium |
| Module Integration | Baseband + RF front-end + power management | Murata, Skyworks, Qorvo | Medium |
| Device OEM | Smartphone, IoT module, automotive ECU | Apple, Samsung, Xiaomi, Ford, Bosch | High (brand and ecosystem) |
The design stage is the most value-intensive, with Qualcomm and MediaTek capturing a disproportionate share of profits through their IP portfolios and integrated platform offerings. Foundry capacity at advanced nodes is a critical bottleneck, particularly for 5G chips that require 7nm or below. Our supply chain interviews suggest that TSMC and Samsung Foundry account for over 70% of advanced baseband chip fabrication, creating a single point of failure risk.
Asia-Pacific dominates both production and consumption of cellular baseband chips, accounting for an estimated 41% of global market value in 2025. The region's preeminence is underpinned by the presence of established semiconductor manufacturers (TSMC, Samsung), a dense ecosystem of device OEMs (Xiaomi, Oppo, Vivo), and aggressive 5G deployment in China, Japan, and South Korea. According to ITU data, the Asia-Pacific region accounted for over 40% of global 5G network deployments in 2023.
North America, while a smaller consumption market, is home to key design and IP companies (Qualcomm, Intel, Apple) and represents a high-value segment driven by premium smartphones and enterprise IoT. Europe is a growing market, particularly for automotive and industrial applications, but lacks a major baseband chip designer, making it heavily reliant on imports. Latin America and the Middle East & Africa are emerging markets, with growth driven by smartphone penetration and network infrastructure development.
The cellular baseband chip market is an oligopoly at the high end and a fragmented, hyper-competitive arena at the mid-to-low end. Qualcomm maintains a technological lead in 5G modems and integrated SoCs, particularly for flagship smartphones. MediaTek has successfully penetrated the mid-range with its Dimensity series and is gaining share in the premium tier. Samsung Semiconductor leverages vertical integration with its Galaxy devices but also supplies third parties. Unisoc (formerly Spreadtrum) and ASRMicro are key players in the budget and IoT segments, while Hisilicon (Huawei) designs chips primarily for captive use.
Strategic white-space opportunities exist in three areas:
For device OEMs and IoT module makers, baseband chip procurement is a strategic decision that balances performance, cost, power efficiency, and supply security.
The cellular baseband chip market is poised for a decade of transformation, driven by the confluence of 5G maturity, 6G research, and AI-native connectivity. We project the market to reach USD 3.77 billion by 2032, with the following key developments shaping the trajectory:
In this evolving landscape, success will hinge on the ability to innovate at the intersection of connectivity, computing, and AI, while navigating an increasingly complex geopolitical and supply chain environment. Companies that can deliver integrated, power-efficient, and secure baseband solutions will be best positioned to capture value in the next wave of cellular connectivity.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.70% from 2020-2034 |
| Segmentation |
|
By Technology
By Component
| By Geography |
|
The global cellular baseband chips market is valued at USD 1.97 billion in 2025 and is projected to reach USD 3.77 billion by 2032, growing at a CAGR of 9.70%.
Asia-Pacific holds the largest share, accounting for approximately 41% of the global market in 2025, driven by high production volumes and rapid 5G adoption in countries like China, South Korea, and Japan.
The market is dominated by Qualcomm, MediaTek, and Samsung Semiconductor, with other notable players including Unisoc, Hisilicon, Intel, and ASRMicro.
Key growth drivers include the global rollout of 5G networks, the proliferation of IoT devices, increasing demand for high-speed data, and the integration of AI capabilities into baseband processors.
The market faces challenges such as high R&D costs, supply chain disruptions, intense competition, and the complexity of standardizing 5G infrastructure, which can hinder widespread adoption.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Technology Officer | 30% |
| VP of Procurement | 25% |
| Head of 5G Strategy | 25% |
| Product Line Director | 20% |
| Company Type | Representation (%) |
|---|---|
| Baseband Chip Designers (Fabless) | 35% |
| Foundry & Packaging Providers | 25% |
| Device OEMs (Smartphone/IoT) | 20% |
| RF Front-End Module Makers | 12% |
| Telecom Operators & Network Planners | 8% |