Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Medical Propellants Market Size, CAGR & Forecast 2025-2035
Independent Intelligence for decisions that move markets
Medical Propellants Market by Propellant Type (HFA 134A, HFA 227EA, HFA 152A, HFO-1234ze(E), Emerging Alternatives(CO2, Hydrocarbons, Compressed Air)), by Application (Press Metered Dose Inhalers, Breath Actuated Metered Dose Inhalers), by End User (Medical Device Companies, Contract Manufacturing Organizations (CMO), Research Laboratories), by Inhaler Therapy Class (SABA, ICS Monotherapy, ICS/LABA Combinations, ICS/LABA/LAMA Triple Therapy, SABA/ICS Rescue Combinations), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia-Pacific (China, India, Japan), by South America, by Middle East & Africa Forecast 2026-2034
Medical experiment monkey market at $1.27B in 2025, rising to $2.29B by 2032 at 9.5% CAGR. Cynomolgus macaques hold 79% share; CROs drive 52% of demand.
Nov 2026|190 pages
$2900.00
Medical Examination Service market to reach $23.5B by 2034, growing at 9.5% CAGR. In-depth analysis, segment insights, and regional outlook.
Nov 2026|216 pages
$2900.00
NAFLD market valued at USD 20.33 Billion in 2026, growing at 15.79% CAGR to USD 42.32 Billion by 2031, driven by Rezdiffra and GLP-1 therapies.
Nov 2026|187 pages
$2900.00
The global tele-ultrasound solution market is valued at USD 350 million in 2025 and is projected to reach USD 773 million by 2032, growing at a CAGR of 12.0%.
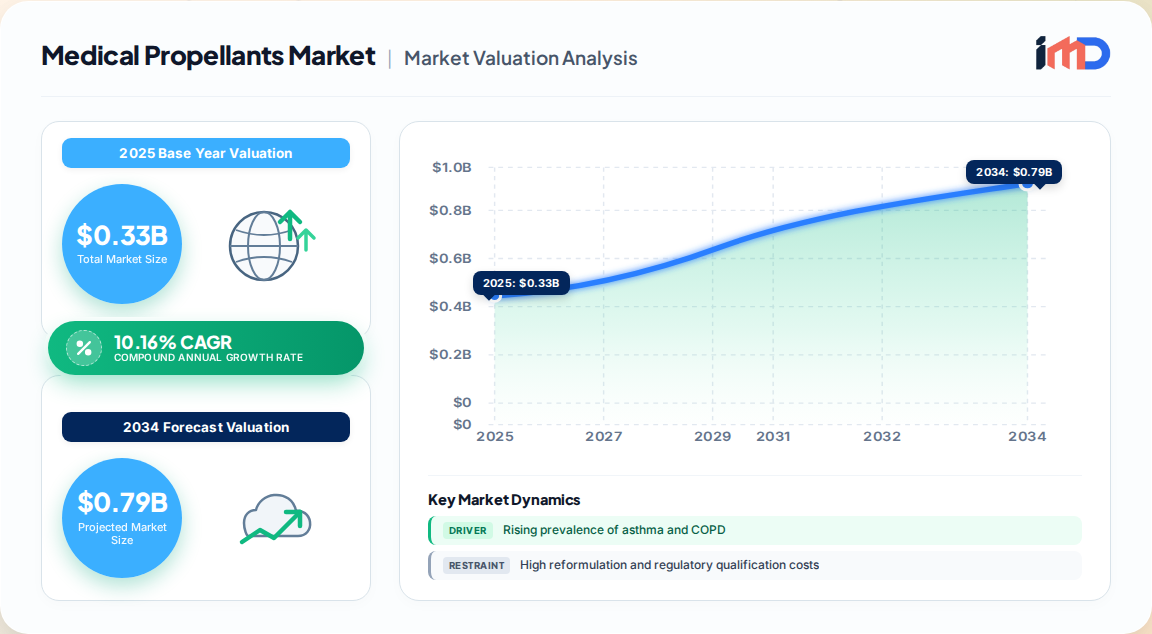
The global medical propellants market is undergoing a structural transformation as the pharmaceutical industry executes its second major propellant reformulation cycle in three decades. Our proprietary primary research estimates the market at USD 0.33 Billion in 2025, expanding to USD 0.87 Billion by 2035 at a 10.16% CAGR (2025–2035).
Medical Propellants Market Market Size (In Million)
750.0M
600.0M
450.0M
300.0M
150.0M
0
330.0 M
2025
364.0 M
2026
400.0 M
2027
441.0 M
2028
486.0 M
2029
535.0 M
2030
590.0 M
2031
Unlike the commodity aerosol propellant complex, medical propellants are defined by pharmacopeia-grade purity, device compatibility validation, and multi-year regulatory qualification. This creates a concentrated value pool where inhalation-grade suppliers command 15–25% higher contribution margins than standard household propellant suppliers.
Metric
2024 (Base)
2025
2035 (Forecast)
CAGR (2025–2035)
Market Value (USD Billion)
0.30
0.33
0.87
10.16%
Dominant Propellant
HFA-134a
HFA-134a
HFA-152a / HFO-1234ze(E)
—
Dominant Device Class
Pressurized MDI
Pressurized MDI
Pressurized MDI
—
Fastest End User
—
CMOs
CMOs
—
Key Market Drivers & Restraints
The demand architecture for medical propellants is anchored in three converging forces: chronic respiratory disease burden, environmental regulation, and device-level innovation.
Drivers
Rising inhalation therapy demand: Asthma and COPD prevalence growth supports an inhalation therapy segment expanding at approximately 7% CAGR, directly pulling propellant volumes through pMDI channels.
Regulatory phase-down of high-GWP HFCs: The Kigali Amendment, the EU revised F-Gas Regulation, and the U.S. AIM Act are imposing binding substitution timelines, converting HFA-134a (GWP 1,430) and HFA-227ea (GWP 3,220) displacement into a compliance-driven demand floor for next-generation propellants.
Patient-centric device redesign: Breath-actuated MDIs and intuitive dose counters are broadening the addressable patient base and accelerating replacement cycles.
Formulation science advances: HFA-grade propellant compatibility with biologics-adjacent and combination therapies is widening the pallet of inhalable actives.
Restraints & Challenges
Reformulation cost and timeline risk: Device redesign, extractable/leachable testing, stability programs, and new drug-device combination approvals can extend transition timelines by multiple years, with 150–300 basis point gross-margin pressure during transition years.
Qualification bottlenecks: Pre-validated drug-device compatibility packages can cut customer qualification timelines by an estimated 20–30%, yet such packages remain scarce for emerging low-GWP molecules.
Supply chain volatility: Quarterly input-cost swings can widen by 10–15% during volatility episodes, with procurement lead times stretching by 1–3 weeks.
Value Chain & Supplier Dynamics
The medical propellant value chain is a tightly qualified, multi-tier ecosystem where switching costs are deliberately high.
Tier
Function
Representative Participants
Fluorochemical Synthesis
Propellant molecule production (HFA-134a, HFA-152a, HFO-1234ze(E))
A pivotal structural event was Honeywell's October 2025 spin-off of its Advanced Materials business into Solstice Advanced Materials, creating a dedicated low-GWP propellant franchise. In May 2025, Honeywell partnered with Lupin to develop inhalers using Solstice Air HFO-1234ze(E), signaling a shift from molecule supply to co-development partnership models.
Import/Export & Trade Flow Analysis
Medical propellants are specialty fluorochemicals traded under dual-use-adjacent chemical control frameworks. Although finished pMDIs move under pharmaceutical goods classifications, bulk propellant gases are subject to chemical export licensing and environmental quota regimes.
The EU's Regulation (EU) 2021/821 governs export controls on dual-use items, and its chemicals annex is periodically updated (most recently via Delegated Regulation (EU) 2025/2003, September 2025). HFC quota allocations under the EU F-Gas Regulation function as a de facto trade barrier, favoring suppliers with pre-existing EU quota rights.
Europe is the largest low-GWP propellant production and consumption hub, with aerosol production reaching 3.460 billion units in 2024.
North America retains the largest medical propellant demand base, supported by U.S. EPA restrictions on higher-GWP HFCs effective January 1, 2025.
Asia-Pacific is the fastest-growing import destination, with India and China expanding pMDI manufacturing capacity for both domestic respiratory programs and multinational contract supply.
Segmentation Analysis
By Propellant Type
HFA-134a remains the largest revenue segment in 2025 but faces structural decline as transition programs mature.
HFA-152a is positioned as the volume driver of the transition, offering a GWP of approximately 138 — a greater than 90% reduction versus HFA-134a — with compatibility closest to existing pMDI technology.
HFO-1234ze(E) is the premium ultra-low-GWP option, favored where hydrocarbon flammability is unacceptable and near-zero GWP is mandated.
HFA-227ea serves niche high-vapor-pressure applications and is the fastest-shrinking incumbent.
By Application
Pressurized MDIs hold the dominant share and remain the anchor application.
Breath-actuated MDIs represent the fastest-growing device class, supported by patient-adherence outcomes.
By End User
Medical device companies constitute the largest buyer group.
Contract manufacturing organizations (CMOs) are the fastest-growing end user as originators externalize fill-finish and transition risk.
Research laboratories provide the innovation pipeline for next-generation propellant-device combinations.
India/China CMO capacity for multinational low-GWP programs
South America
~6%
Emerging
Regulatory harmonization and local fill-finish
Middle East & Africa
~6%
Emerging
Medical gas and propellant distribution infrastructure
Europe's leadership is regulatory-driven: the EU F-Gas Regulation imposes binding substitution timelines ahead of Kigali schedules. Asia-Pacific's growth is volume-driven, with China's aerosol manufacturing scale and India's expanding respiratory portfolio creating a two-track demand profile.
Medical Propellants Market Regional Market Share
Loading chart...
The most defensible white-space lies in pre-validated drug-device compatibility packages for HFA-152a and HFO-1234ze(E). Suppliers that codify extractables/leachables datasets, valve elastomer compatibility, and stability protocols can compress customer qualification timelines by 20–30%, converting technical services into recurring propellant offtake.
Competitive Landscape & Strategic Developments
The market exhibits moderate concentration in propellant synthesis (Honeywell/Solstice, Koura, Daikin, Arkema) and high fragmentation in device components and CDMO services.
2025: Honeywell completed the spin-off of Advanced Materials into Solstice Advanced Materials, focused on low-GWP propellants and fluorinated specialty materials.
May 2025: Honeywell partnered with Lupin to develop inhalers using Solstice Air HFO-1234ze(E) propellant.
2025: U.S. EPA confirmed restrictions on higher-GWP HFCs in aerosols; EU revised F-Gas Regulation began cutting quota availability.
2025–2026: AstraZeneca, GSK, and Chiesi advanced clinical programs for next-generation MDI formulations with near-zero GWP propellant systems.
Conclusion & Forecast Synthesis
The medical propellants market is a USD 0.87 Billion opportunity by 2035, but its strategic value exceeds its absolute size. Propellant selection now determines device architecture, regulatory pathway, and corporate scope-3 emissions accounting.
Suppliers that combine fluorochemical synthesis capability, pre-validated compatibility data, and quota-secured regional supply will capture disproportionate margin. Conversely, late movers face 150–300 basis point gross-margin compression during transition years and accelerated incumbent displacement.
The 2025–2030 window is the decisive qualification period. Propellant suppliers that secure device-partner design-ins before 2028 will lock in offtake through the 2035 forecast horizon.
Medical Propellants Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Medical Propellants Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.16% from 2020-2034
Segmentation
By Propellant Type
HFA 134A
HFA 227EA
HFA 152A
HFO-1234ze
E
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. Rising prevalence of asthma and COPD
3.1.2. Regulatory phase-down of high-GWP HFCs
3.1.3. Growing focus on patient-centric inhalation devices
3.1.4. Advancements in pharmaceutical formulations
3.1.5. Increasing regulatory support for innovative products
3.1.6. Expanding healthcare infrastructure in emerging markets
3.2. Market Trends
3.2.1. Shift towards eco-friendly low-GWP propellants
3.2.2. Technological advancements in aerosol delivery systems
3.5.2. 150-300 basis point margin pressure during transition years
3.5.3. Limited pre-validated compatibility data for emerging propellants
3.5.4. Procurement lead time variability of 1-3 weeks during volatility
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Propellant Type
5.1.1. HFA 134A
5.1.2. HFA 227EA
5.1.3. HFA 152A
5.1.4. HFO-1234ze
5.1.4.1. E
5.1.5. Emerging Alternatives
5.1.5.1. CO2
5.1.5.2. Hydrocarbons
5.1.5.3. Compressed Air
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Press Metered Dose Inhalers
5.2.2. Breath Actuated Metered Dose Inhalers
5.3. Market Analysis, Insights and Forecast - by End User
5.3.1. Medical Device Companies
5.3.2. Contract Manufacturing Organizations
5.3.2.1. CMO
5.3.3. Research Laboratories
5.4. Market Analysis, Insights and Forecast - by Inhaler Therapy Class
5.4.1. SABA
5.4.2. ICS Monotherapy
5.4.3. ICS/LABA Combinations
5.4.4. ICS/LABA/LAMA Triple Therapy
5.4.5. SABA/ICS Rescue Combinations
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia-Pacific
5.5.4. South America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Propellant Type
6.1.1. HFA 134A
6.1.2. HFA 227EA
6.1.3. HFA 152A
6.1.4. HFO-1234ze
6.1.4.1. E
6.1.5. Emerging Alternatives
6.1.5.1. CO2
6.1.5.2. Hydrocarbons
6.1.5.3. Compressed Air
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Press Metered Dose Inhalers
6.2.2. Breath Actuated Metered Dose Inhalers
6.3. Market Analysis, Insights and Forecast - by End User
6.3.1. Medical Device Companies
6.3.2. Contract Manufacturing Organizations
6.3.2.1. CMO
6.3.3. Research Laboratories
6.4. Market Analysis, Insights and Forecast - by Inhaler Therapy Class
6.4.1. SABA
6.4.2. ICS Monotherapy
6.4.3. ICS/LABA Combinations
6.4.4. ICS/LABA/LAMA Triple Therapy
6.4.5. SABA/ICS Rescue Combinations
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Propellant Type
7.1.1. HFA 134A
7.1.2. HFA 227EA
7.1.3. HFA 152A
7.1.4. HFO-1234ze
7.1.4.1. E
7.1.5. Emerging Alternatives
7.1.5.1. CO2
7.1.5.2. Hydrocarbons
7.1.5.3. Compressed Air
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Press Metered Dose Inhalers
7.2.2. Breath Actuated Metered Dose Inhalers
7.3. Market Analysis, Insights and Forecast - by End User
7.3.1. Medical Device Companies
7.3.2. Contract Manufacturing Organizations
7.3.2.1. CMO
7.3.3. Research Laboratories
7.4. Market Analysis, Insights and Forecast - by Inhaler Therapy Class
7.4.1. SABA
7.4.2. ICS Monotherapy
7.4.3. ICS/LABA Combinations
7.4.4. ICS/LABA/LAMA Triple Therapy
7.4.5. SABA/ICS Rescue Combinations
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Propellant Type
8.1.1. HFA 134A
8.1.2. HFA 227EA
8.1.3. HFA 152A
8.1.4. HFO-1234ze
8.1.4.1. E
8.1.5. Emerging Alternatives
8.1.5.1. CO2
8.1.5.2. Hydrocarbons
8.1.5.3. Compressed Air
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Press Metered Dose Inhalers
8.2.2. Breath Actuated Metered Dose Inhalers
8.3. Market Analysis, Insights and Forecast - by End User
8.3.1. Medical Device Companies
8.3.2. Contract Manufacturing Organizations
8.3.2.1. CMO
8.3.3. Research Laboratories
8.4. Market Analysis, Insights and Forecast - by Inhaler Therapy Class
8.4.1. SABA
8.4.2. ICS Monotherapy
8.4.3. ICS/LABA Combinations
8.4.4. ICS/LABA/LAMA Triple Therapy
8.4.5. SABA/ICS Rescue Combinations
9. South America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Propellant Type
9.1.1. HFA 134A
9.1.2. HFA 227EA
9.1.3. HFA 152A
9.1.4. HFO-1234ze
9.1.4.1. E
9.1.5. Emerging Alternatives
9.1.5.1. CO2
9.1.5.2. Hydrocarbons
9.1.5.3. Compressed Air
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Press Metered Dose Inhalers
9.2.2. Breath Actuated Metered Dose Inhalers
9.3. Market Analysis, Insights and Forecast - by End User
9.3.1. Medical Device Companies
9.3.2. Contract Manufacturing Organizations
9.3.2.1. CMO
9.3.3. Research Laboratories
9.4. Market Analysis, Insights and Forecast - by Inhaler Therapy Class
9.4.1. SABA
9.4.2. ICS Monotherapy
9.4.3. ICS/LABA Combinations
9.4.4. ICS/LABA/LAMA Triple Therapy
9.4.5. SABA/ICS Rescue Combinations
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Propellant Type
10.1.1. HFA 134A
10.1.2. HFA 227EA
10.1.3. HFA 152A
10.1.4. HFO-1234ze
10.1.4.1. E
10.1.5. Emerging Alternatives
10.1.5.1. CO2
10.1.5.2. Hydrocarbons
10.1.5.3. Compressed Air
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Press Metered Dose Inhalers
10.2.2. Breath Actuated Metered Dose Inhalers
10.3. Market Analysis, Insights and Forecast - by End User
10.3.1. Medical Device Companies
10.3.2. Contract Manufacturing Organizations
10.3.2.1. CMO
10.3.3. Research Laboratories
10.4. Market Analysis, Insights and Forecast - by Inhaler Therapy Class
10.4.1. SABA
10.4.2. ICS Monotherapy
10.4.3. ICS/LABA Combinations
10.4.4. ICS/LABA/LAMA Triple Therapy
10.4.5. SABA/ICS Rescue Combinations
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Honeywell International (Solstice Advanced Materials)
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Koura (Orbia Fluor & Energy Materials)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Daikin Industries
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Arkema S.A.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Linde plc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Air Products and Chemicals
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. AptarGroup
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Propelair
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. 3M
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Kraton Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. BASF SE
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Solvay SA
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. AstraZeneca plc
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. GSK plc
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Chiesi Farmaceutici S.p.A.
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Boehringer Ingelheim
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. Sanofi S.A.
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.1.18. Cipla Limited
11.1.18.1. Company Overview
11.1.18.2. Products
11.1.18.3. Company Financials
11.1.18.4. SWOT Analysis
11.1.19. Lupin Limited
11.1.19.1. Company Overview
11.1.19.2. Products
11.1.19.3. Company Financials
11.1.19.4. SWOT Analysis
11.1.20. Glenmark Pharmaceuticals
11.1.20.1. Company Overview
11.1.20.2. Products
11.1.20.3. Company Financials
11.1.20.4. SWOT Analysis
11.1.21. Teva Pharmaceutical Industries
11.1.21.1. Company Overview
11.1.21.2. Products
11.1.21.3. Company Financials
11.1.21.4. SWOT Analysis
11.1.22. Viatris Inc.
11.1.22.1. Company Overview
11.1.22.2. Products
11.1.22.3. Company Financials
11.1.22.4. SWOT Analysis
11.1.23. Hikma Pharmaceuticals plc
11.1.23.1. Company Overview
11.1.23.2. Products
11.1.23.3. Company Financials
11.1.23.4. SWOT Analysis
11.1.24. Bespak
11.1.24.1. Company Overview
11.1.24.2. Products
11.1.24.3. Company Financials
11.1.24.4. SWOT Analysis
11.1.25. Kindeva Drug Delivery
11.1.25.1. Company Overview
11.1.25.2. Products
11.1.25.3. Company Financials
11.1.25.4. SWOT Analysis
11.1.26. Recipharm AB
11.1.26.1. Company Overview
11.1.26.2. Products
11.1.26.3. Company Financials
11.1.26.4. SWOT Analysis
11.1.27. Catalent Inc.
11.1.27.1. Company Overview
11.1.27.2. Products
11.1.27.3. Company Financials
11.1.27.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
List of Figures
Figure 1: Global Medical Propellants Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Medical Propellants Market Revenue (Billion), by Propellant Type 2026 & 2034
Figure 3: North America Medical Propellants Market Revenue Share (%), by Propellant Type 2026 & 2034
Figure 4: North America Medical Propellants Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Medical Propellants Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Medical Propellants Market Revenue (Billion), by End User 2026 & 2034
Figure 7: North America Medical Propellants Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Medical Propellants Market Revenue (Billion), by Inhaler Therapy Class 2026 & 2034
Figure 9: North America Medical Propellants Market Revenue Share (%), by Inhaler Therapy Class 2026 & 2034
Figure 10: North America Medical Propellants Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Medical Propellants Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Medical Propellants Market Revenue (Billion), by Propellant Type 2026 & 2034
Figure 13: Europe Medical Propellants Market Revenue Share (%), by Propellant Type 2026 & 2034
Figure 14: Europe Medical Propellants Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Medical Propellants Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Medical Propellants Market Revenue (Billion), by End User 2026 & 2034
Figure 17: Europe Medical Propellants Market Revenue Share (%), by End User 2026 & 2034
Figure 18: Europe Medical Propellants Market Revenue (Billion), by Inhaler Therapy Class 2026 & 2034
Figure 19: Europe Medical Propellants Market Revenue Share (%), by Inhaler Therapy Class 2026 & 2034
Figure 20: Europe Medical Propellants Market Revenue (Billion), by Country 2026 & 2034
Figure 21: Europe Medical Propellants Market Revenue Share (%), by Country 2026 & 2034
Figure 22: Asia-Pacific Medical Propellants Market Revenue (Billion), by Propellant Type 2026 & 2034
Figure 23: Asia-Pacific Medical Propellants Market Revenue Share (%), by Propellant Type 2026 & 2034
Figure 24: Asia-Pacific Medical Propellants Market Revenue (Billion), by Application 2026 & 2034
Figure 25: Asia-Pacific Medical Propellants Market Revenue Share (%), by Application 2026 & 2034
Figure 26: Asia-Pacific Medical Propellants Market Revenue (Billion), by End User 2026 & 2034
Figure 27: Asia-Pacific Medical Propellants Market Revenue Share (%), by End User 2026 & 2034
Figure 28: Asia-Pacific Medical Propellants Market Revenue (Billion), by Inhaler Therapy Class 2026 & 2034
Figure 29: Asia-Pacific Medical Propellants Market Revenue Share (%), by Inhaler Therapy Class 2026 & 2034
Figure 30: Asia-Pacific Medical Propellants Market Revenue (Billion), by Country 2026 & 2034
Figure 31: Asia-Pacific Medical Propellants Market Revenue Share (%), by Country 2026 & 2034
Figure 32: South America Medical Propellants Market Revenue (Billion), by Propellant Type 2026 & 2034
Figure 33: South America Medical Propellants Market Revenue Share (%), by Propellant Type 2026 & 2034
Figure 34: South America Medical Propellants Market Revenue (Billion), by Application 2026 & 2034
Figure 35: South America Medical Propellants Market Revenue Share (%), by Application 2026 & 2034
Figure 36: South America Medical Propellants Market Revenue (Billion), by End User 2026 & 2034
Figure 37: South America Medical Propellants Market Revenue Share (%), by End User 2026 & 2034
Figure 38: South America Medical Propellants Market Revenue (Billion), by Inhaler Therapy Class 2026 & 2034
Figure 39: South America Medical Propellants Market Revenue Share (%), by Inhaler Therapy Class 2026 & 2034
Figure 40: South America Medical Propellants Market Revenue (Billion), by Country 2026 & 2034
Figure 41: South America Medical Propellants Market Revenue Share (%), by Country 2026 & 2034
Figure 42: Middle East & Africa Medical Propellants Market Revenue (Billion), by Propellant Type 2026 & 2034
Figure 43: Middle East & Africa Medical Propellants Market Revenue Share (%), by Propellant Type 2026 & 2034
Figure 44: Middle East & Africa Medical Propellants Market Revenue (Billion), by Application 2026 & 2034
Figure 45: Middle East & Africa Medical Propellants Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Middle East & Africa Medical Propellants Market Revenue (Billion), by End User 2026 & 2034
Figure 47: Middle East & Africa Medical Propellants Market Revenue Share (%), by End User 2026 & 2034
Figure 48: Middle East & Africa Medical Propellants Market Revenue (Billion), by Inhaler Therapy Class 2026 & 2034
Figure 49: Middle East & Africa Medical Propellants Market Revenue Share (%), by Inhaler Therapy Class 2026 & 2034
Figure 50: Middle East & Africa Medical Propellants Market Revenue (Billion), by Country 2026 & 2034
Figure 51: Middle East & Africa Medical Propellants Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Medical Propellants Market Revenue Billion Forecast, by Propellant Type 2020 & 2034
Table 2: Global Medical Propellants Market Revenue Billion Forecast, by Application 2020 & 2034
Table 3: Global Medical Propellants Market Revenue Billion Forecast, by End User 2020 & 2034
Table 4: Global Medical Propellants Market Revenue Billion Forecast, by Inhaler Therapy Class 2020 & 2034
Table 5: Global Medical Propellants Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Medical Propellants Market Revenue Billion Forecast, by Propellant Type 2020 & 2034
Table 7: North America Medical Propellants Market Revenue Billion Forecast, by Application 2020 & 2034
Table 8: North America Medical Propellants Market Revenue Billion Forecast, by End User 2020 & 2034
Table 9: North America Medical Propellants Market Revenue Billion Forecast, by Inhaler Therapy Class 2020 & 2034
Table 10: North America Medical Propellants Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Medical Propellants Market Revenue Billion Forecast, by Propellant Type 2020 & 2034
Table 15: Europe Medical Propellants Market Revenue Billion Forecast, by Application 2020 & 2034
Table 16: Europe Medical Propellants Market Revenue Billion Forecast, by End User 2020 & 2034
Table 17: Europe Medical Propellants Market Revenue Billion Forecast, by Inhaler Therapy Class 2020 & 2034
Table 18: Europe Medical Propellants Market Revenue Billion Forecast, by Country 2020 & 2034
Table 19: Germany Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 20: UK Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 21: France Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 22: Italy Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 23: Asia-Pacific Medical Propellants Market Revenue Billion Forecast, by Propellant Type 2020 & 2034
Table 24: Asia-Pacific Medical Propellants Market Revenue Billion Forecast, by Application 2020 & 2034
Table 25: Asia-Pacific Medical Propellants Market Revenue Billion Forecast, by End User 2020 & 2034
Table 26: Asia-Pacific Medical Propellants Market Revenue Billion Forecast, by Inhaler Therapy Class 2020 & 2034
Table 27: Asia-Pacific Medical Propellants Market Revenue Billion Forecast, by Country 2020 & 2034
Table 28: China Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: India Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Japan Medical Propellants Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 31: South America Medical Propellants Market Revenue Billion Forecast, by Propellant Type 2020 & 2034
Table 32: South America Medical Propellants Market Revenue Billion Forecast, by Application 2020 & 2034
Table 33: South America Medical Propellants Market Revenue Billion Forecast, by End User 2020 & 2034
Table 34: South America Medical Propellants Market Revenue Billion Forecast, by Inhaler Therapy Class 2020 & 2034
Table 35: South America Medical Propellants Market Revenue Billion Forecast, by Country 2020 & 2034
Table 36: Middle East & Africa Medical Propellants Market Revenue Billion Forecast, by Propellant Type 2020 & 2034
Table 37: Middle East & Africa Medical Propellants Market Revenue Billion Forecast, by Application 2020 & 2034
Table 38: Middle East & Africa Medical Propellants Market Revenue Billion Forecast, by End User 2020 & 2034
Table 39: Middle East & Africa Medical Propellants Market Revenue Billion Forecast, by Inhaler Therapy Class 2020 & 2034
Table 40: Middle East & Africa Medical Propellants Market Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1What is the medical propellants market size in 2025?
The global medical propellants market is estimated at **USD 0.33 Billion in 2025** and is projected to reach **USD 0.87 Billion by 2035**, expanding at a **10.16% CAGR**, driven by the transition from HFA-134a to HFA-152a and HFO-1234ze(E) in pressurized metered-dose inhalers.
2Which propellant type is expected to drive the medical propellants market?
HFA-152a (1,1-difluoroethane) is positioned as the volume driver, offering a GWP of approximately **138** versus 1,430 for HFA-134a, while maintaining compatibility with existing pMDI technology. HFO-1234ze(E) serves the ultra-low-GWP premium segment where near-zero GWP is mandated.
3Why is Europe a leading region in low-GWP medical propellants?
Europe leads because the EU revised F-Gas Regulation imposes HFC phase-down timelines ahead of Kigali Amendment schedules. European aerosol production reached **3.460 billion units in 2024**, providing the industrial base and quota framework that favor early low-GWP propellant adoption.
4What are the main challenges in transitioning to low-GWP medical propellants?
Transition requires inhaler component redesign, extractables and leachables testing, stability programs, and new drug-device combination approvals. These factors can extend timelines by multiple years and cause **150–300 basis point gross-margin pressure** during transition years for manufacturers.
5Who are the leading companies in the medical propellants market?
Key participants include Honeywell (Solstice Advanced Materials), Koura (Orbia), Daikin, Arkema, Linde plc, Air Products and Chemicals, AptarGroup, and Propelair on the supply side, with AstraZeneca, GSK, Chiesi, Cipla, and Lupin driving demand through inhaler portfolios.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of total research effort is allocated to primary research, including structured interviews and surveys with executives across the medical propellant value chain.
Target respondent companies include fluorochemical propellant manufacturers, pressurized metered-dose inhaler device OEMs, inhalation contract development and manufacturing organizations (CDMOs), and originator and generic respiratory pharmaceutical companies.
Stakeholder job titles interviewed include Procurement Directors, Inhalation Formulation Scientists, Regulatory Affairs Managers, and Supply Chain Heads.
Interviews are conducted across North America, Europe, and Asia-Pacific, with sample quotas weighted to reflect regional production and consumption intensity.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Procurement Director
30%
Inhalation Formulation Scientist
25%
Regulatory Affairs Manager
25%
Supply Chain Head
20%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Fluorochemical Propellant Manufacturers
30%
pMDI Device & Component OEMs
25%
Inhalation CDMOs
25%
Originator & Generic Pharma
20%
Secondary Research & Industry Benchmarking
20–30% of effort is dedicated to secondary research, triangulating company filings, pharmacopeia standards, and regulatory dockets.
Data sources include Bloomberg, Factiva, Hoovers, and PitchBook for corporate financials and transaction data.
Official institutional sources include the European Commission (Regulation (EU) 2021/821 dual-use export controls), the U.S. Environmental Protection Agency (AIM Act and HFC restrictions), the UNEP Ozone Secretariat (Kigali Amendment), and recognized non-profit technical standards bodies such as the International Pharmaceutical Aerosol Consortium (IPAC) and European Aerosol Federation (FEA).
Regulatory benchmarking covers EU F-Gas Regulation quotas, U.S. EPA HFC restrictions, and pharmacopeia-grade propellant monographs.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously, validated via multi-level data triangulation.
Bottom-up calculation relies on specific quantitative metrics: global pMDI unit production volumes by device class, average propellant fill weight per canister (grams), propellant price per kilogram adjusted for pharmacopeia grade, and regional propellant substitution rates by molecule.
Demand is modeled by therapy class including SABA, ICS monotherapy, ICS/LABA combinations, and ICS/LABA/LAMA triple therapy, with propellant intensity coefficients applied per inhaler category.
Supply-side capacity is cross-checked against announced HFA-152a and HFO-1234ze(E) production investments.
Data Accuracy & Quality Check
The report maintains a guaranteed estimated data accuracy level of 85–90%, with error bands disclosed for forward projections.
Multi-level triangulation is performed across primary interviews, trade statistics, corporate disclosures, and regulatory quota data.
Every report is updated to the date of purchase, ensuring alignment with the latest regulatory and commercial developments.
Quality checks include respondent validation, outlier detection in survey data, and reconciliation of propellant volume estimates with device shipment data.