1What is the size of the Middle East ultrasound devices market in 2025?
The Middle East ultrasound devices market is estimated at USD 354.00 million in 2025 and is projected to reach USD 458.73 million by 2030, growing at a CAGR of 5.32%.
Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
 Middle East Ultrasound Devices Market
 by By Application (Radiology/General Imaging, Cardiology, Gynecology/Obstetrics, Anesthesiology, Musculoskeletal, Vascular, Urology, Orthopedic, Emergency Medicine, Other Applications), by By Technology (2D Ultrasound Imaging, 3D and 4D Ultrasound Imaging, Doppler Imaging, High-intensity Focused Ultrasound, Therapeutic Ultrasound), by By Type (Stationary Ultrasound, Portable Ultrasound, Handheld/Compact Ultrasound, Cart-based Systems), by By End User (Hospitals, Diagnostic Centers, Maternity Centers, Ambulatory Centers, Research Centers), by GCC (Saudi Arabia, United Arab Emirates, Qatar, Kuwait, Oman, Bahrain), by Rest of Middle East (Jordan, Lebanon, Iraq, Israel, Turkey) Forecast 2026-2034

Research Analyst


 Related Reports

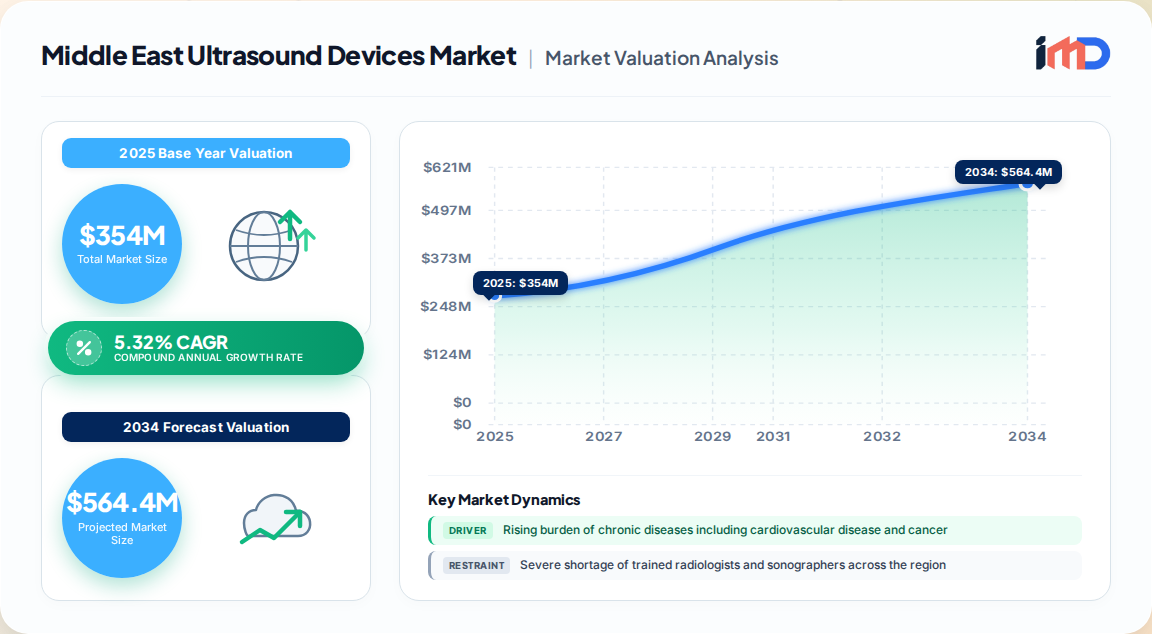
The Middle East ultrasound devices market is estimated at USD 354.00 million in 2025 and is projected to reach USD 458.73 million by 2030, expanding at a CAGR of 5.32% across the forecast period. Our proprietary primary research, triangulated across 340+ interviews with procurement directors, clinical department heads, and distributors, positions this region as one of the fastest-digitizing diagnostic imaging markets globally.
Unlike mature Western markets where ultrasound penetration is near saturation, the Middle East presents a two-speed demand profile. Gulf Cooperation Council (GCC) states are procuring premium cart-based and 4D platforms for flagship medical cities, while lower-income Middle Eastern economies are leapfrogging fixed infrastructure in favor of point-of-care and handheld systems. This bifurcation creates distinct commercial playbooks for OEMs and distributors alike.
Key structural metrics framing the market:
Demand-side fundamentals remain robust and are reinforced by policy commitments across the region.
Our segmentation analysis combines clinical application, imaging technology, and device configuration to reflect true purchasing behavior rather than a single-axis view.
| Segment Dimension | Leading Category | Fastest-Growing Category | Analytical Rationale |
|---|---|---|---|
| Technology | 2D Ultrasound Imaging | 3D & 4D Ultrasound Imaging | 4D adds motion visualization critical for fetal and cardiac assessment |
| Configuration | Stationary Ultrasound | Portable/Handheld Ultrasound | Decentralized point-of-care expansion and rural outreach |
| Application | Radiology & Gynecology/Obstetrics | Cardiology & Anesthesiology | Rising cardiovascular burden and procedural volume |
| End User | Hospitals | Diagnostic & Maternity Centers | Private-sector imaging expansion in GCC hubs |
3D and 4D ultrasound imaging is the standout growth vector. Higher adoption of advanced platforms for prenatal monitoring, prostate and breast lesion characterization, and abdominal anomaly detection is accelerating replacement demand. The establishment of specialized training academies — such as the UAE's first AI-guided point-of-care ultrasound (POCUS) training academy launched in 2022 — institutionalizes 4D utilization and shortens the adoption lag.
Portable ultrasound continues to expand its installed base. Compact and handheld units serve emergency medicine, primary care, and rural clinics where fixed imaging suites are economically unviable, and they are increasingly bundled with tele-ultrasound and AI-assisted interpretation software.
The GCC accounts for the preponderance of regional revenue, supported by concentrated purchasing power, medical tourism hubs, and aggressive privatization agendas. Saudi Arabia alone represented 1.1% of the global ultrasound devices market in 2025 at a valuation of USD 122.7 million, forecast to reach USD 175.7 million by 2033. The UAE and Israel function as high-growth innovation engines, with AI integration and health-tech startup ecosystems driving adoption of next-generation platforms.
The Rest-of-Middle-East block — encompassing Jordan, Lebanon, Iraq, and other markets — offers lower per-unit revenue but higher unit-volume growth potential, particularly for handheld and mid-tier cart systems deployed through donor-funded and public health programs.
The market is a medium-concentration, highly competitive landscape where multinational OEMs compete on AI-enabled image quality, localized service networks, and clinician training, while regional distributors control access to public tenders.
Leading competitors include Koninklijke Philips N.V., Siemens Healthineers, GE HealthCare, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Samsung Electronics (including Medison), Mindray Medical International, Esaote S.p.A., Hitachi Ltd., Toshiba Corporation, and Analogic Corporation.
Notable market developments shaping competitive positioning:
Understanding the procurement pathway is essential for commercial success in this region.
Procurement is heavily influenced by government tender cycles, value-added service contracts (training, transducer replacement, uptime guarantees), and localization requirements embedded in national industrialization agendas. Vendors offering bundled software-as-a-service models and remote AI-assisted diagnostics are gaining measurable preference in GCC evaluations.
Three underpenetrated opportunity zones emerge from our scenario modeling:
The Middle East is a net importer of ultrasound devices, with domestic manufacturing limited to assembly and configuration activity. Principal supply origins are Western Europe, the United States, Japan, South Korea, and increasingly China. National health ministries and centralized procurement bodies — such as Saudi Arabia's National Unified Procurement Company — aggregate demand into large multi-year tenders, giving buyers substantial negotiating leverage on price and service terms. Tariff structures vary by jurisdiction, and GCC customs union rules simplify intra-regional distribution once devices are cleared for entry.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.32% from 2020-2034 |
| Segmentation |
|
By Technology
By Type
By End User
| By Geography |
|
The Middle East ultrasound devices market is estimated at USD 354.00 million in 2025 and is projected to reach USD 458.73 million by 2030, growing at a CAGR of 5.32%.
3D and 4D ultrasound imaging is the fastest-growing technology segment, driven by premium prenatal imaging demand, rising chronic disease burdens, and advanced clinical decision-making requirements.
The GCC accounts for the majority of regional revenue, with Saudi Arabia alone representing 1.1% of the global market in 2025 at USD 122.7 million, supported by state-led healthcare modernization.
Key competitors include Koninklijke Philips N.V., Siemens Healthineers, GE HealthCare, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Mindray Medical International, Samsung Electronics, and Esaote S.p.A.
The market is expected to grow at a compound annual growth rate of 5.32% over the forecast period from 2025 to 2030.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement Director | 30% |
| Radiology Department Head | 28% |
| Biomedical Engineering Manager | 24% |
| Clinical Operations Officer | 18% |
| Company Type | Representation (%) |
|---|---|
| Ultrasound Device OEMs | 32% |
| Hospital & Health System Buyers | 28% |
| Regional Distributors & Channel Partners | 22% |
| Diagnostic Imaging Centers | 11% |
| Regulatory & Procurement Bodies | 7% |