Insight Market Data is a premier market research and business consulting firm headquartered in Pune, India, providing syndicated research reports, customized intelligence studies, and strategic advisory services. Renowned academic institutions and Fortune 500 corporations worldwide rely on Insight Market Data's research repository to navigate evolving global and regional business environments. Covering 46 diverse industries across 25 major international economies, our comprehensive database delivers thousands of verified statistics and granular market evaluations. By combining industry-leading analytical methodologies with the direct insights of seasoned industry leaders and subject-matter experts, we deliver actionable intelligence spanning historical performance benchmarks to rigorous multi-year forecasts. We empower organizations to make confident, data-driven decisions across pivotal domains including Machinery & Equipment, Chemicals & Materials, Pharmaceuticals & Healthcare, Food & Beverages, Consumer Goods, Energy & Power, Automotive & Transportation, Electronics & Semiconductors, Medical Devices, Telecommunications, Emerging Technologies, Agriculture, and Packaging. Our multidisciplinary analyst teams provide an objective 360-degree perspective, tailoring every engagement to address complex strategic challenges with exceptional analytical rigor.
Leveraging advanced BI-powered analytics and predictive modeling, Insight Market Data uncovers high-impact market opportunities and competitive differentiators for ambitious enterprises. We continuously refine our research methodologies in accordance with global industry standards, tracking real-time market shifts to ensure our reports are consistently accurate, actionable, and delivered on schedule. Our analysts conduct methodical data validation, rigorous compliance checks, and exhaustive primary and secondary research to maintain the highest levels of data integrity and transparency. We partner closely with corporate strategists, investment groups, and business executives to translate intricate market intelligence into clear, actionable roadmaps for sustainable growth. With operational presence across Washington, USA, and Vimannagar, Pune, India, Insight Market Data ensures direct access to dedicated research specialists and responsive customer support to answer your most strategic questions.
Canada Road Freight Transport Industry Market Report 2025
Canada Road Freight Transport Industry
Logistics / MARKET REPORT
Canada Road Freight Transport Industry | Insight Market Data
Canada Road Freight Transport Industry by Service Type (Full Truckload, Less-Than-Truckload, Final-Mile & Parcel, Dedicated Contract Carriage, Temperature-Controlled, Bulk & Tanker, Cross-Border), by End-Use Vertical (Retail & Consumer Goods, Automotive & Industrial Manufacturing, Agriculture & Food, Energy & Chemicals, Construction Materials, Healthcare & Pharmaceuticals), by Ownership (For-Hire, Private Fleet, Asset-Light Brokerage), by Ontario, by Quebec, by British Columbia, by Alberta, by Prairies (Manitoba, Saskatchewan), by Atlantic Canada Forecast 2026-2034
Executive Overview: The Backbone of Canadian Commerce
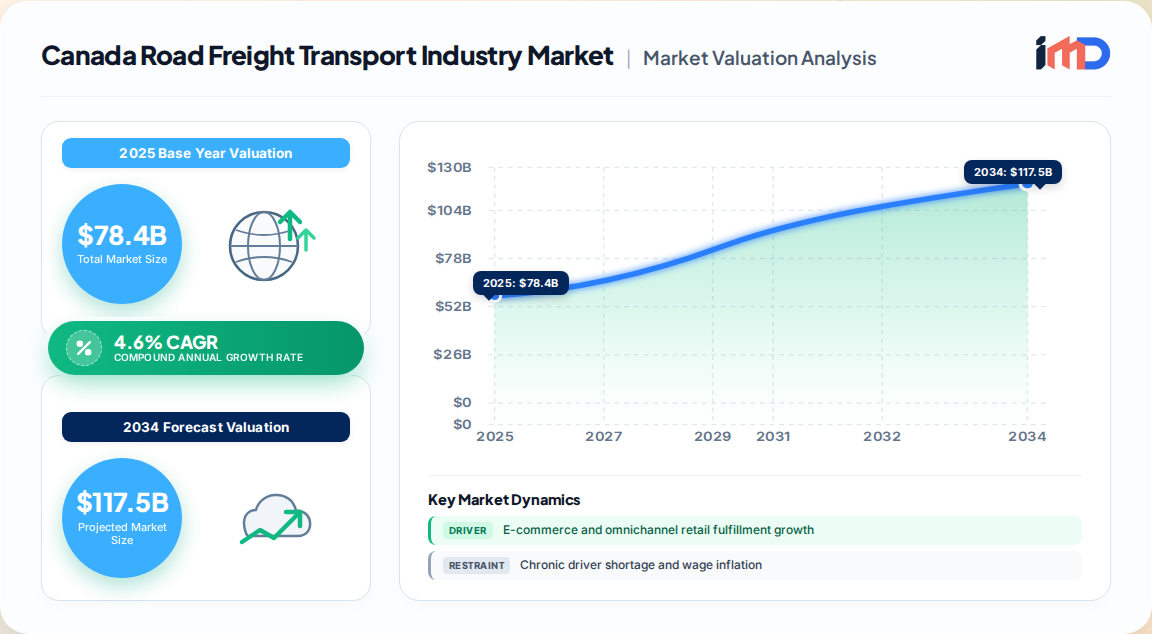
The Canada road freight transport industry market is the circulatory system of the world's second-largest country by landmass, moving an estimated 78.4 Billion in annual revenue in 2025 and expanding at a resilient 4.6% CAGR through 2030. Road transport carries the majority of Canada's domestic tonnage and remains the dominant mode for trade with the United States, Canada's largest trading partner.
Canada Road Freight Transport Industry Market Size (In Billion)
150.0B
100.0B
50.0B
0
78.40 B
2025
82.01 B
2026
85.78 B
2027
89.72 B
2028
93.85 B
2029
98.17 B
2030
102.7 B
2031
Our proprietary primary research, drawing on interviews with carriers, shippers, and logistics intermediaries across all provinces, positions the market on a moderate-growth, margin-compressed trajectory. The structural driver is simple geography: a population of roughly 41 million dispersed across 9.98 million square kilometers creates long-haul density that rail cannot fully absorb and that trucking serves at scale.
Key structural characteristics define the landscape:
Highly fragmented supply base: Thousands of for-hire carriers coexist with a deep in-house private fleet segment, especially in grocery, building materials, and manufacturing.
Cross-border exposure: A large share of sector revenue is tied to Canada–US trade flows, exposing carriers to tariff and FX volatility.
Labor-constrained capacity: Driver recruitment and retention remains the single most binding constraint on fleet expansion.
Market Metric
2025 Estimate
Outlook
Market Size (Revenue)
78.4 Billion
4.6% CAGR to 2030
Dominant Mode
Full Truckload (TL)
Stable share
Fastest-Growing Segment
LTL & Final-Mile
High single-digit growth
Key Trade Corridor
Ontario–Quebec–US Midwest
Concentration risk
Market Drivers and Restraints
Demand for road freight in Canada is anchored in three durable engines: e-commerce fulfillment density, resource-sector output (agriculture, energy, forestry), and cross-border manufacturing integration in the auto and industrial corridors.
Drivers include:
E-commerce and omnichannel retail: Final-mile and LTL demand growth outpaces overall freight growth, pushing carriers toward denser urban delivery networks.
Nearshoring and supply-chain diversification: Manufacturers relocating capacity to Mexico and the US Southeast are reshaping corridor flows, creating new north–south and east–west lane demand.
Infrastructure investment: Federal and provincial highway programs, including corridor upgrades around the Greater Toronto Area and Quebec, improve productivity but arrive slowly.
Restraints and challenges:
Chronic driver shortage: Ageing workforce demographics and long-haul lifestyle attrition constrain capacity, sustaining upward pressure on wages and sign-on incentives.
Fuel and carbon pricing exposure: Carbon pricing mechanisms and diesel volatility compress operating margins, particularly for small fleets lacking hedging capability.
Regulatory fragmentation: Provincial weight, hours-of-service, and permit variation adds administrative cost to multi-provincial operations.
The Canadian road freight market segments most usefully by service type, load configuration, and end-use vertical. Our primary interviews confirm that full truckload remains the revenue anchor, but value growth is migrating toward asset-light and time-definite services.
Segment
Characteristics
Growth Trajectory
Full Truckload (TL)
High volume, lane-based, fuel-sensitive
Moderate
Less-Than-Truckload (LTL)
Hub-and-spoke, higher yield per pound
High
Final-Mile & Parcel
Urban density, tech-enabled
High
Dedicated Contract Carriage
Predictable, shipper-integrated
Stable-moderate
Temperature-Controlled
Food and pharma, compliance-heavy
Moderate-high
Bulk & Tanker
Resource and chemical flows
Cyclical
Cross-Border
Customs-intensive, US-linked
Trade-policy sensitive
End-use verticals include retail and consumer goods, automotive and industrial manufacturing, agriculture and food, energy and chemicals, construction materials, and healthcare and pharmaceuticals. Temperature-controlled capacity is structurally tight, and shippers increasingly demand validated cold-chain documentation.
Competitive Landscape and Strategic Positioning
The market is bifurcated between a small tier of large national and cross-border carriers and a long tail of regional and owner-operator fleets. Scale advantages concentrate in fuel purchasing, technology investment, and shipper contract access.
Competitive strategy clusters we observe:
National network consolidation: Large carriers expand through tuck-in acquisitions to build density in LTL and dedicated lanes.
Technology differentiation: Telematics, dynamic routing, and load-matching platforms reduce empty miles and improve asset utilization.
Niche specialization: Temperature-controlled, bulk, and heavy-haul operators defend margin through compliance expertise and specialized equipment.
Asset-light brokerage models: Digital freight brokers and 3PL intermediaries capture share in spot and small-shipper segments.
Import/Export & Supplier Dynamics
The Canadian road freight market is inseparable from cross-border trade. Road carriers move the majority of Canada–US merchandise by value, with the Ontario–Michigan, British Columbia–Washington, and Quebec–New York/New England gateways dominating flow concentration.
Supply-side dynamics to monitor:
Equipment supply: Class 8 tractor and trailer availability, OEM lead times, and used-equipment values influence fleet renewal economics.
Intermodal competition: Rail competes aggressively on long-haul bulk and container flows, capping truck pricing on dense corridors.
Regional Outlook
Ontario and Quebec together represent the largest share of freight revenue, driven by population density, manufacturing concentration, and US-border proximity. Western provinces, led by Alberta and British Columbia, exhibit resource-cyclical demand with strong agriculture and energy linkages. Atlantic Canada remains smaller and more dependent on public-sector and food distribution flows.
Canada Road Freight Transport Industry Regional Market Share
Loading chart...
Ontario: Largest market, cross-border gateway concentration, high LTL density.
Quebec: Manufacturing and consumer goods corridors, strong regional carriers.
British Columbia: Port-linked drayage and Asia-Pacific trade exposure.
Alberta and Prairies: Resource, agriculture, and energy-driven bulk flows.
Strategic White-Space and Investment Opportunity
Our analysis identifies several under-served opportunity areas for carriers and investors:
Cold-chain capacity in secondary cities: Temperature-controlled availability lags demand outside major metros.
Digital brokerage in francophone and rural markets: Technology penetration remains uneven.
Fleet electrification pilots on short-haul urban lanes: Total cost of ownership is approaching parity in dense delivery applications.
Cross-border compliance-as-a-service: Shippers seek integrated customs and carrier solutions.
Investors should weigh labor cost inflation and trade-policy sensitivity against the durable structural demand for road capacity in a geographically vast, trade-dependent economy.
Canada Road Freight Transport Industry Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Canada Road Freight Transport Industry REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.6% from 2020-2034
Segmentation
By Service Type
Full Truckload
Less-Than-Truckload
Final-Mile & Parcel
Dedicated Contract Carriage
Temperature-Controlled
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.1.1. E-commerce and omnichannel retail fulfillment growth
3.1.2. Cross-border manufacturing integration with the US
3.1.3. Resource-sector output in agriculture, energy, and forestry
3.1.4. Federal and provincial highway infrastructure investment
3.2. Market Trends
3.2.1. Digital freight brokerage and load-matching platform adoption
3.2.2. Fleet electrification pilots on short-haul urban lanes
3.2.4. Cold-chain capacity investment in secondary cities
3.3. Market Restrains
3.3.1. Chronic driver shortage and wage inflation
3.3.2. Carbon pricing and diesel fuel volatility
3.3.3. Provincial regulatory fragmentation
3.3.4. Canada-US trade-policy uncertainty
3.4. Market Restraints
3.4.1. Chronic driver shortage and wage inflation
3.4.2. Carbon pricing and diesel fuel volatility
3.4.3. Provincial regulatory fragmentation
Bulk & Tanker
Cross-Border
By End-Use Vertical
Retail & Consumer Goods
Automotive & Industrial Manufacturing
Agriculture & Food
Energy & Chemicals
Construction Materials
Healthcare & Pharmaceuticals
By Ownership
For-Hire
Private Fleet
Asset-Light Brokerage
By Geography
Ontario
Quebec
British Columbia
Alberta
Prairies
Manitoba
Saskatchewan
Atlantic Canada
3.4.4. Canada-US trade-policy uncertainty
3.5. Market Challenges
3.5.1. Ageing driver workforce demographics
3.5.2. Small-fleet margin compression from fuel and insurance costs
3.5.3. Intermodal rail competition on long-haul corridors
3.5.4. Customs compliance complexity at major gateways
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. IMD Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Service Type
5.1.1. Full Truckload
5.1.2. Less-Than-Truckload
5.1.3. Final-Mile & Parcel
5.1.4. Dedicated Contract Carriage
5.1.5. Temperature-Controlled
5.1.6. Bulk & Tanker
5.1.7. Cross-Border
5.2. Market Analysis, Insights and Forecast - by End-Use Vertical
5.2.1. Retail & Consumer Goods
5.2.2. Automotive & Industrial Manufacturing
5.2.3. Agriculture & Food
5.2.4. Energy & Chemicals
5.2.5. Construction Materials
5.2.6. Healthcare & Pharmaceuticals
5.3. Market Analysis, Insights and Forecast - by Ownership
5.3.1. For-Hire
5.3.2. Private Fleet
5.3.3. Asset-Light Brokerage
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. Ontario
5.4.2. Quebec
5.4.3. British Columbia
5.4.4. Alberta
5.4.5. Prairies
5.4.6. Atlantic Canada
6. Ontario Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Service Type
6.1.1. Full Truckload
6.1.2. Less-Than-Truckload
6.1.3. Final-Mile & Parcel
6.1.4. Dedicated Contract Carriage
6.1.5. Temperature-Controlled
6.1.6. Bulk & Tanker
6.1.7. Cross-Border
6.2. Market Analysis, Insights and Forecast - by End-Use Vertical
6.2.1. Retail & Consumer Goods
6.2.2. Automotive & Industrial Manufacturing
6.2.3. Agriculture & Food
6.2.4. Energy & Chemicals
6.2.5. Construction Materials
6.2.6. Healthcare & Pharmaceuticals
6.3. Market Analysis, Insights and Forecast - by Ownership
6.3.1. For-Hire
6.3.2. Private Fleet
6.3.3. Asset-Light Brokerage
7. Quebec Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Service Type
7.1.1. Full Truckload
7.1.2. Less-Than-Truckload
7.1.3. Final-Mile & Parcel
7.1.4. Dedicated Contract Carriage
7.1.5. Temperature-Controlled
7.1.6. Bulk & Tanker
7.1.7. Cross-Border
7.2. Market Analysis, Insights and Forecast - by End-Use Vertical
7.2.1. Retail & Consumer Goods
7.2.2. Automotive & Industrial Manufacturing
7.2.3. Agriculture & Food
7.2.4. Energy & Chemicals
7.2.5. Construction Materials
7.2.6. Healthcare & Pharmaceuticals
7.3. Market Analysis, Insights and Forecast - by Ownership
7.3.1. For-Hire
7.3.2. Private Fleet
7.3.3. Asset-Light Brokerage
8. British Columbia Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Service Type
8.1.1. Full Truckload
8.1.2. Less-Than-Truckload
8.1.3. Final-Mile & Parcel
8.1.4. Dedicated Contract Carriage
8.1.5. Temperature-Controlled
8.1.6. Bulk & Tanker
8.1.7. Cross-Border
8.2. Market Analysis, Insights and Forecast - by End-Use Vertical
8.2.1. Retail & Consumer Goods
8.2.2. Automotive & Industrial Manufacturing
8.2.3. Agriculture & Food
8.2.4. Energy & Chemicals
8.2.5. Construction Materials
8.2.6. Healthcare & Pharmaceuticals
8.3. Market Analysis, Insights and Forecast - by Ownership
8.3.1. For-Hire
8.3.2. Private Fleet
8.3.3. Asset-Light Brokerage
9. Alberta Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Service Type
9.1.1. Full Truckload
9.1.2. Less-Than-Truckload
9.1.3. Final-Mile & Parcel
9.1.4. Dedicated Contract Carriage
9.1.5. Temperature-Controlled
9.1.6. Bulk & Tanker
9.1.7. Cross-Border
9.2. Market Analysis, Insights and Forecast - by End-Use Vertical
9.2.1. Retail & Consumer Goods
9.2.2. Automotive & Industrial Manufacturing
9.2.3. Agriculture & Food
9.2.4. Energy & Chemicals
9.2.5. Construction Materials
9.2.6. Healthcare & Pharmaceuticals
9.3. Market Analysis, Insights and Forecast - by Ownership
9.3.1. For-Hire
9.3.2. Private Fleet
9.3.3. Asset-Light Brokerage
10. Prairies Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Service Type
10.1.1. Full Truckload
10.1.2. Less-Than-Truckload
10.1.3. Final-Mile & Parcel
10.1.4. Dedicated Contract Carriage
10.1.5. Temperature-Controlled
10.1.6. Bulk & Tanker
10.1.7. Cross-Border
10.2. Market Analysis, Insights and Forecast - by End-Use Vertical
10.2.1. Retail & Consumer Goods
10.2.2. Automotive & Industrial Manufacturing
10.2.3. Agriculture & Food
10.2.4. Energy & Chemicals
10.2.5. Construction Materials
10.2.6. Healthcare & Pharmaceuticals
10.3. Market Analysis, Insights and Forecast - by Ownership
10.3.1. For-Hire
10.3.2. Private Fleet
10.3.3. Asset-Light Brokerage
11. Atlantic Canada Market Analysis, Insights and Forecast, 2020-2034
11.1. Market Analysis, Insights and Forecast - by Service Type
11.1.1. Full Truckload
11.1.2. Less-Than-Truckload
11.1.3. Final-Mile & Parcel
11.1.4. Dedicated Contract Carriage
11.1.5. Temperature-Controlled
11.1.6. Bulk & Tanker
11.1.7. Cross-Border
11.2. Market Analysis, Insights and Forecast - by End-Use Vertical
11.2.1. Retail & Consumer Goods
11.2.2. Automotive & Industrial Manufacturing
11.2.3. Agriculture & Food
11.2.4. Energy & Chemicals
11.2.5. Construction Materials
11.2.6. Healthcare & Pharmaceuticals
11.3. Market Analysis, Insights and Forecast - by Ownership
11.3.1. For-Hire
11.3.2. Private Fleet
11.3.3. Asset-Light Brokerage
12. Competitive Analysis
12.1. Company Profiles
12.1.1. TFI International
12.1.1.1. Company Overview
12.1.1.2. Products
12.1.1.3. Company Financials
12.1.1.4. SWOT Analysis
12.1.2. Bison Transport
12.1.2.1. Company Overview
12.1.2.2. Products
12.1.2.3. Company Financials
12.1.2.4. SWOT Analysis
12.1.3. Mullen Group
12.1.3.1. Company Overview
12.1.3.2. Products
12.1.3.3. Company Financials
12.1.3.4. SWOT Analysis
12.1.4. Canada Cartage
12.1.4.1. Company Overview
12.1.4.2. Products
12.1.4.3. Company Financials
12.1.4.4. SWOT Analysis
12.1.5. Day & Ross
12.1.5.1. Company Overview
12.1.5.2. Products
12.1.5.3. Company Financials
12.1.5.4. SWOT Analysis
12.1.6. Challenger Motor Freight
12.1.6.1. Company Overview
12.1.6.2. Products
12.1.6.3. Company Financials
12.1.6.4. SWOT Analysis
12.1.7. Rosenau Transport
12.1.7.1. Company Overview
12.1.7.2. Products
12.1.7.3. Company Financials
12.1.7.4. SWOT Analysis
12.1.8. Manitoulin Transport
12.1.8.1. Company Overview
12.1.8.2. Products
12.1.8.3. Company Financials
12.1.8.4. SWOT Analysis
12.1.9. TransX Group of Companies
12.1.9.1. Company Overview
12.1.9.2. Products
12.1.9.3. Company Financials
12.1.9.4. SWOT Analysis
12.1.10. SLH Transport
12.1.10.1. Company Overview
12.1.10.2. Products
12.1.10.3. Company Financials
12.1.10.4. SWOT Analysis
12.1.11. Kriska Holdings
12.1.11.1. Company Overview
12.1.11.2. Products
12.1.11.3. Company Financials
12.1.11.4. SWOT Analysis
12.1.12. Groupe Robert
12.1.12.1. Company Overview
12.1.12.2. Products
12.1.12.3. Company Financials
12.1.12.4. SWOT Analysis
12.1.13. Vitran Corporation
12.1.13.1. Company Overview
12.1.13.2. Products
12.1.13.3. Company Financials
12.1.13.4. SWOT Analysis
12.2. Market Entropy
12.2.1. Company's Key Areas Served
12.2.2. Recent Developments
12.3. Company Market Share Analysis, 2026
12.3.1. Top 5 Companies Market Share Analysis
12.3.2. Top 3 Companies Market Share Analysis
12.4. List of Potential Customers
List of Figures
Figure 1: Global Canada Road Freight Transport Industry Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Ontario Canada Road Freight Transport Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 3: Ontario Canada Road Freight Transport Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 4: Ontario Canada Road Freight Transport Industry Revenue (Billion), by End-Use Vertical 2026 & 2034
Figure 5: Ontario Canada Road Freight Transport Industry Revenue Share (%), by End-Use Vertical 2026 & 2034
Figure 6: Ontario Canada Road Freight Transport Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 7: Ontario Canada Road Freight Transport Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 8: Ontario Canada Road Freight Transport Industry Revenue (Billion), by Country 2026 & 2034
Figure 9: Ontario Canada Road Freight Transport Industry Revenue Share (%), by Country 2026 & 2034
Figure 10: Quebec Canada Road Freight Transport Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 11: Quebec Canada Road Freight Transport Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 12: Quebec Canada Road Freight Transport Industry Revenue (Billion), by End-Use Vertical 2026 & 2034
Figure 13: Quebec Canada Road Freight Transport Industry Revenue Share (%), by End-Use Vertical 2026 & 2034
Figure 14: Quebec Canada Road Freight Transport Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 15: Quebec Canada Road Freight Transport Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 16: Quebec Canada Road Freight Transport Industry Revenue (Billion), by Country 2026 & 2034
Figure 17: Quebec Canada Road Freight Transport Industry Revenue Share (%), by Country 2026 & 2034
Figure 18: British Columbia Canada Road Freight Transport Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 19: British Columbia Canada Road Freight Transport Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 20: British Columbia Canada Road Freight Transport Industry Revenue (Billion), by End-Use Vertical 2026 & 2034
Figure 21: British Columbia Canada Road Freight Transport Industry Revenue Share (%), by End-Use Vertical 2026 & 2034
Figure 22: British Columbia Canada Road Freight Transport Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 23: British Columbia Canada Road Freight Transport Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 24: British Columbia Canada Road Freight Transport Industry Revenue (Billion), by Country 2026 & 2034
Figure 25: British Columbia Canada Road Freight Transport Industry Revenue Share (%), by Country 2026 & 2034
Figure 26: Alberta Canada Road Freight Transport Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 27: Alberta Canada Road Freight Transport Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 28: Alberta Canada Road Freight Transport Industry Revenue (Billion), by End-Use Vertical 2026 & 2034
Figure 29: Alberta Canada Road Freight Transport Industry Revenue Share (%), by End-Use Vertical 2026 & 2034
Figure 30: Alberta Canada Road Freight Transport Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 31: Alberta Canada Road Freight Transport Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 32: Alberta Canada Road Freight Transport Industry Revenue (Billion), by Country 2026 & 2034
Figure 33: Alberta Canada Road Freight Transport Industry Revenue Share (%), by Country 2026 & 2034
Figure 34: Prairies Canada Road Freight Transport Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 35: Prairies Canada Road Freight Transport Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 36: Prairies Canada Road Freight Transport Industry Revenue (Billion), by End-Use Vertical 2026 & 2034
Figure 37: Prairies Canada Road Freight Transport Industry Revenue Share (%), by End-Use Vertical 2026 & 2034
Figure 38: Prairies Canada Road Freight Transport Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 39: Prairies Canada Road Freight Transport Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 40: Prairies Canada Road Freight Transport Industry Revenue (Billion), by Country 2026 & 2034
Figure 41: Prairies Canada Road Freight Transport Industry Revenue Share (%), by Country 2026 & 2034
Figure 42: Atlantic Canada Canada Road Freight Transport Industry Revenue (Billion), by Service Type 2026 & 2034
Figure 43: Atlantic Canada Canada Road Freight Transport Industry Revenue Share (%), by Service Type 2026 & 2034
Figure 44: Atlantic Canada Canada Road Freight Transport Industry Revenue (Billion), by End-Use Vertical 2026 & 2034
Figure 45: Atlantic Canada Canada Road Freight Transport Industry Revenue Share (%), by End-Use Vertical 2026 & 2034
Figure 46: Atlantic Canada Canada Road Freight Transport Industry Revenue (Billion), by Ownership 2026 & 2034
Figure 47: Atlantic Canada Canada Road Freight Transport Industry Revenue Share (%), by Ownership 2026 & 2034
Figure 48: Atlantic Canada Canada Road Freight Transport Industry Revenue (Billion), by Country 2026 & 2034
Figure 49: Atlantic Canada Canada Road Freight Transport Industry Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Global Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 2: Global Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 3: Global Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 4: Global Canada Road Freight Transport Industry Revenue Billion Forecast, by Region 2020 & 2034
Table 5: Ontario Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 6: Ontario Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 7: Ontario Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 8: Ontario Canada Road Freight Transport Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 9: Quebec Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 10: Quebec Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 11: Quebec Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 12: Quebec Canada Road Freight Transport Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 13: British Columbia Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 14: British Columbia Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 15: British Columbia Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 16: British Columbia Canada Road Freight Transport Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 17: Alberta Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 18: Alberta Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 19: Alberta Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 20: Alberta Canada Road Freight Transport Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 21: Prairies Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 22: Prairies Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 23: Prairies Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 24: Prairies Canada Road Freight Transport Industry Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Manitoba Canada Road Freight Transport Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: Saskatchewan Canada Road Freight Transport Industry Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: Atlantic Canada Canada Road Freight Transport Industry Revenue Billion Forecast, by Service Type 2020 & 2034
Table 28: Atlantic Canada Canada Road Freight Transport Industry Revenue Billion Forecast, by End-Use Vertical 2020 & 2034
Table 29: Atlantic Canada Canada Road Freight Transport Industry Revenue Billion Forecast, by Ownership 2020 & 2034
Table 30: Atlantic Canada Canada Road Freight Transport Industry Revenue Billion Forecast, by Country 2020 & 2034
Frequently Asked Questions
1How large is the Canada road freight transport industry market?
Our proprietary primary research estimates the Canada road freight transport industry market at approximately 78.4 Billion in 2025, expanding at a 4.6% CAGR through 2030. Growth is driven by e-commerce fulfillment, resource-sector output, and cross-border trade with the United States.
2Which segment dominates the Canada road freight market?
Full truckload (TL) remains the largest revenue segment, but LTL and final-mile services are growing fastest, reflecting e-commerce density and shipper demand for time-definite delivery.
3What is the biggest challenge facing Canadian road freight carriers?
The chronic driver shortage is the single most binding constraint on capacity expansion. Ageing workforce demographics, long-haul attrition, and rising wage costs limit fleet growth and sustain upward pressure on rates.
4Which regions drive the most road freight revenue in Canada?
Ontario and Quebec account for the largest share of revenue due to population density, manufacturing concentration, and US-border proximity. Alberta and British Columbia contribute resource-cyclical demand tied to energy and agriculture.
5How does cross-border trade affect the Canadian trucking market?
A significant share of sector revenue is tied to Canada–US merchandise flows, making carriers sensitive to tariff policy, currency movements, and customs compliance requirements at major gateways such as Ontario–Michigan and British Columbia–Washington.
Methodology
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of our research input derives from primary sources, including structured interviews with carrier executives, shipper logistics leaders, and fleet operators across all Canadian provinces.
We conduct direct outreach to five specific company types in this value chain: national for-hire truckload and LTL carriers; private fleet operators in retail and manufacturing; digital freight brokerages and 3PL intermediaries; temperature-controlled and specialized haulage operators; and fleet equipment lessors and telematics vendors.
Stakeholder interviews target roles including Vice President of Fleet Operations, Director of Logistics and Transportation Procurement, Cross-Border Compliance Manager, and Chief Operating Officer at regional carriers.
We engage recognized industry associations and regulatory bodies for validation, including the Canadian Trucking Alliance, the Ontario Trucking Association, Transport Canada, and the Canadian Transportation Agency.
Every report is updated to the date of purchase, incorporating the latest interview findings and market conditions.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Vice President of Fleet Operations
35%
Director of Logistics and Transportation Procurement
30%
Cross-Border Compliance Manager
20%
Chief Operating Officer
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
National for-hire TL and LTL carriers
38%
Private fleet operators (retail, manufacturing)
22%
Digital freight brokerages and 3PL intermediaries
16%
Temperature-controlled and specialized haulage operators
14%
Fleet equipment lessors and telematics vendors
10%
Secondary Research & Industry Benchmarking
20–30% of research input comes from secondary benchmarking against official governmental and multilateral datasets, including Statistics Canada, Transport Canada, the US Bureau of Transportation Statistics Freight Analysis Framework, and OECD International Transport Forum publications.
We reference recognized non-profit trade associations and standards bodies to validate tonnage, modal share, and safety-compliance parameters.
Standard financial databases, including Bloomberg, Factiva, Hoovers, and PitchBook, are used to triangulate carrier revenue, merger activity, and equipment investment trends.
We employ top-down and bottom-up methodologies simultaneously, reconciling national freight revenue aggregates with bottom-up fleet-level build-ups.
Bottom-up calculation uses specific quantitative metrics: registered heavy-duty tractor and trailer counts by province, average revenue per power unit, tonnage moved per lane, and loaded-mile utilization rates.
Multi-level data triangulation cross-checks provincial fleet registries, carrier financial disclosures, and shipper freight-spend surveys to converge on a single market estimate.
Forecasts are scenario-weighted across base, upside, and downside cases reflecting trade-policy and fuel-price sensitivity.
Data Accuracy & Quality Check
We guarantee an estimated data accuracy level of 85–90%, achieved through multi-source validation and analyst review.
Every market-size figure is stress-tested against at least three independent data streams before publication.
Outlier interviews and inconsistent carrier disclosures are flagged, re-verified, and excluded where reliability thresholds are not met.
Final estimates undergo senior analyst sign-off and are refreshed to the date of purchase to reflect current market conditions.
Independent Intelligence for decisions that move markets
Vietnam CEP market valued at USD 1.88 billion in 2026, growing at 7.2% CAGR to reach USD 2.66 billion by 2031. Explore key trends, drivers, and competitive landscape.
Nov 2026|241 pages
$2900.00
The Asia Pacific FMCG logistics market is valued at $328.8 billion in 2025, growing at 6.4% CAGR to reach $580.1 billion by 2034, driven by e-commerce and cold chain.
Nov 2026|219 pages
$2900.00
Malaysia freight logistics market to reach USD 54.30 Bn by 2035 at 5.52% CAGR. Explore drivers, segmentation, and regional analysis.